
Hydrogen Storage Tanks and Transportation Market Report Scope & Overview:
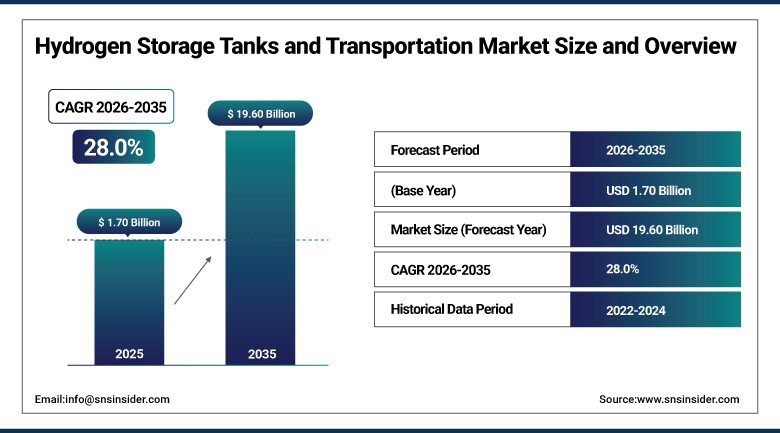
The Hydrogen Storage Tanks and Transportation Market was valued at USD 1.70 billion in 2025 and is projected to reach USD 19.60 billion by 2035, expanding at a CAGR of 28.0% during the forecast period.
Hydrogen storage vessels and transportation networks ensure the storage and transport of hydrogen in its compressed gaseous form, cryogenic liquid state, or solid-state storage medium from hydrogen production sites to distribution centers and finally to their point of use in applications like fuel cell electric vehicle refueling stations and stationary industrial storage. Hydrogen in fuel cell electric vehicles is stored inside the vehicles in high-pressure Type III and Type IV composite cylinders designed to store hydrogen at very high pressure in a weight-efficient way. The pressure on the transportation industry to meet zero-emissions goals by various governments worldwide has been growing due to stringent net-zero emission targets set by them.
Hydrogen distribution through modular trailer tube systems continues to be an area of growth in increasing the flexibility of delivery without the need for fixed pipeline systems, an ability that is quite useful especially when it comes to areas in which the hydrogen refueling network is still under construction. The cryogenic tankers are also becoming more common as a means of delivering liquid hydrogen on long distances due to their increased energy density compared to the compressed hydrogen trailers in long-distance cases. Hydrogen suppliers are becoming increasingly likely to provide logistics solutions that combine storage and logistics services in one contract as opposed to just selling hydrogen-related equipment, in line with the trends in the industrial gas sector of favoring service contracts over hardware-only purchases.
Various governments around the world are providing more capital investment programs meant to create hydrogen infrastructure since hydrogen will play an important role in helping them achieve sustainability goals.
To Get more information Hydrogen Storage Tanks and Transportation Market - Request Free Sample Report
Hydrogen Storage Tanks and Transportation Market Trends
-
Rising adoption of Type IV composite storage tanks offering superior weight-to-capacity ratios for fuel cell vehicles
-
Growing deployment of modular tube trailers enabling flexible hydrogen distribution without fixed pipeline infrastructure
-
Increasing investment in cryogenic liquid hydrogen tanker technology for long-distance transport applications
-
Rising government capital funding for hydrogen refueling and storage infrastructure development
-
Growing adoption of hydrogen storage in transit buses, delivery vans, and long-haul trucking fleets
U.S. Hydrogen Storage Tanks and Transportation Market Outlook
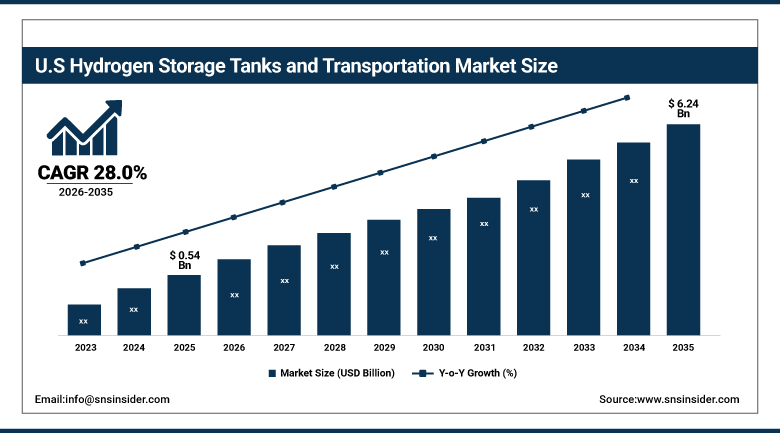
The U.S. hydrogen storage tanks and transportation market was valued at USD 0.54 billion in 2025 and is projected to reach USD 6.24 billion by 2035, growing at a CAGR of 28.0% during 2026-2035.
The U.S. market is supported by Department of Energy Regional Clean Hydrogen Hubs funding and growing fuel cell electric vehicle and heavy-duty truck deployment across California and other early-adopter states with established hydrogen refueling networks. California continues to lead domestic demand given its combination of zero-emission vehicle mandates and an already-established base of hydrogen refueling stations serving both passenger and commercial fleet vehicles.
U.S. tank manufacturers are increasingly investing in domestic carbon fiber production capacity to reduce reliance on imported composite materials, both to strengthen supply chain resilience and to qualify for domestic content provisions under federal clean energy manufacturing incentive programs. Several U.S. states beyond California, including Texas and states within the Midwest hydrogen hub region, are beginning to develop complementary refueling infrastructure aimed at supporting broader commercial fleet hydrogen adoption over the coming decade.
Growing production of hydrogen fuel cell vehicles across passenger, transit, and commercial fleet segments continues to expand U.S. demand for high-pressure composite storage tanks, with commercial fleet operators increasingly viewing hydrogen as a viable alternative to battery electric power for long-haul and heavy-duty applications requiring rapid refueling and extended range.
Hydrogen Storage Tanks and Transportation Market Segment Analysis
-
By Tank Type, the Type III segment dominated the Hydrogen Storage Tanks and Transportation Market with approximately 48.6% share in 2025, while the Type IV segment is the fastest growing with a CAGR of approximately 33.4%.
-
By Material, the Metal segment dominated the Hydrogen Storage Tanks and Transportation Market with approximately 57.4% share in 2025, while the Carbon Fiber segment is the fastest growing with a CAGR of approximately 34.8%.
-
By Application, the Stationary Storage segment dominated the Hydrogen Storage Tanks and Transportation Market with approximately 41.2% share in 2025, while the Fuel Cell Vehicles segment is the fastest growing with a CAGR of approximately 35.6%.
By Tank Type, Type III Dominates the Hydrogen Storage Tanks and Transportation Market While Type IV Registers the Fastest Growth
Type III dominated the Hydrogen Storage Tanks and Transportation Market in 2025 due to the fact that its metal-lined, composite-wrapped construction offers a proven balance of weight reduction and pressure capacity that has already achieved wide commercial deployment across existing fuel cell vehicle platforms and industrial gas cylinder fleets, giving it the largest installed base and most established manufacturing supply chain of any composite tank design.
Type IV is the fastest-growing segment in the Hydrogen Storage Tanks and Transportation Market due to the fact that its fully polymer-lined, carbon-fiber-wrapped construction delivers superior weight-to-capacity performance essential for maximizing vehicle range and payload in passenger vehicles and commercial fleets. There is increasing demand from next-generation fuel cell vehicle platforms specifically engineered around Type IV tank geometry to optimize onboard storage efficiency.
By Material, Metal Dominates the Hydrogen Storage Tanks and Transportation Market While Carbon Fiber Registers the Fastest Growth
Metal dominated the Hydrogen Storage Tanks and Transportation Market in 2025 due to the fact that steel and aluminum tanks offer proven durability, strength, and capacity to withstand high pressures at a substantially lower cost than composite alternatives, making them the default choice for bulk stationary storage and industrial gas cylinder applications where weight is a secondary consideration relative to cost and reliability.
Carbon Fiber is the fastest-growing segment in the Hydrogen Storage Tanks and Transportation Market due to the fact that this premium material offers the highest strength-to-weight ratio of any available tank construction material, a critical advantage for mobile applications including fuel cell vehicles and portable hydrogen transport where minimizing tank weight directly improves vehicle range and payload capacity.
By Application, Stationary Storage Dominates the Hydrogen Storage Tanks and Transportation Market While Fuel Cell Vehicles Register the Fastest Growth
Stationary Storage dominated the Hydrogen Storage Tanks and Transportation Market in 2025 due to the fact that hydrogen production facilities, refueling stations, and industrial users all require substantial on-site storage capacity to buffer supply and demand fluctuations, an established and continuously expanding infrastructure category that predates the current wave of fuel cell vehicle-driven demand growth.
Fuel Cell Vehicles is the fastest-growing segment in the Hydrogen Storage Tanks and Transportation Market due to the fact that expanding hydrogen refueling infrastructure investment and growing commercial fleet adoption of fuel cell technology for long-haul trucking and transit bus applications continue to drive rapid growth in onboard vehicle storage tank demand, a category still in the early stages of its adoption curve relative to more mature stationary storage infrastructure.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.0% |
|
Europe |
Germany |
29.0% |
|
Asia Pacific |
China |
45.0% |
|
Middle East & Africa |
Saudi Arabia |
32.0% |
|
Latin America |
Chile |
30.0% |
North America Hydrogen Storage Tanks and Transportation Market Insights
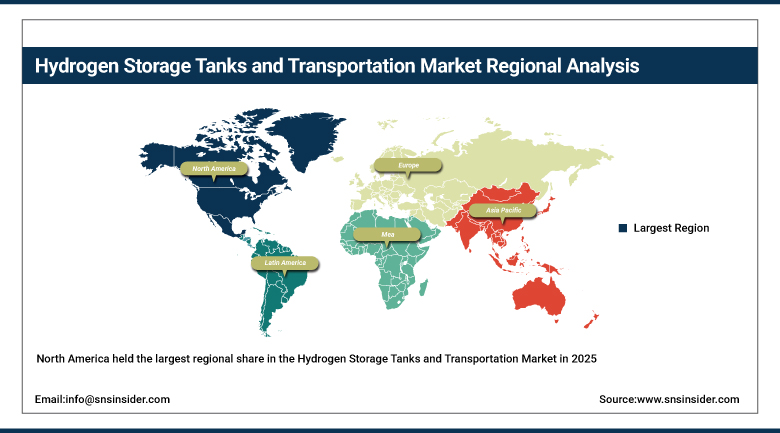
North America held the largest regional share in the Hydrogen Storage Tanks and Transportation Market in 2025, supported by Department of Energy Regional Clean Hydrogen Hubs funding and California's established hydrogen refueling network serving both passenger and commercial fleet vehicles.
Canadian hydrogen storage infrastructure investment continues to expand in British Columbia and Quebec, supported by low-cost renewable electricity availability that improves the economics of co-locating hydrogen production and storage facilities near renewable generation sites.
Mexican industrial hydrogen storage demand remains at an early stage, though growing cross-border supply chain integration with U.S. hydrogen hub development is gradually expanding regional interest in complementary storage and transportation infrastructure.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Hydrogen Storage Tanks and Transportation Market Insights
Europe's market benefits from strong government policy frameworks, including the EU Green Deal and national hydrogen strategies in Germany and the Netherlands, that continue to fund hydrogen storage and transportation infrastructure buildout across major industrial corridors.
German and Dutch industrial hubs continue to lead European stationary hydrogen storage investment, supported by the region's dense concentration of steel, chemical, and refining facilities pursuing industrial decarbonization through green hydrogen substitution.
French and Italian hydrogen mobility programs continue to expand, supported by national funding for hydrogen bus and truck fleet pilot projects that are driving incremental demand for both onboard and refueling station storage infrastructure.
Asia Pacific Hydrogen Storage Tanks and Transportation Market Insights
The Hydrogen Storage Tanks and Transportation Market is being driven by rapid expansion in Asia Pacific, which is led by China, Japan, and South Korea, due to the ambitious goals for deployment of fuel cell vehicles and increasing capacity for manufacturing of hydrogen storage tanks in these countries.
Japanese and South Korean manufacturers of automobiles are leading the commercialization of fuel cell vehicles around the globe, contributing significantly to the demand for vehicle-mounted hydrogen storage tanks and hydrogen refueling stations infrastructure. Chinese manufactures are scaling up their production of hydrogen storage tanks to serve their fuel cell buses and hydrogen infrastructure needs.
Middle East & Africa and Latin America Hydrogen Storage Tanks and Transportation Market Insights
The Middle East & Africa region is growing steadily as Gulf state green hydrogen export mega-projects, including developments in Saudi Arabia and Oman, drive demand for large-scale stationary storage and transportation infrastructure supporting future hydrogen export logistics. Saudi Arabia's NEOM green hydrogen project continues to drive demand for large-scale ammonia-based hydrogen transportation infrastructure, positioning the kingdom as a future major hydrogen export hub serving Asian and European import markets.
Latin America is gradually developing as the Chilean green hydrogen projects’ developers focus on storage and transportation infrastructure development in order to decarbonize the local industries as well as prepare for the eventual export of hydrogen to Asian and European markets. On the other hand, the Brazilian hydrogen projects’ developers, who are mostly in the wind-rich regions of the country, are still studying investments in storage and transportation infrastructure development.
Market Dynamics
Growth Drivers: Fuel cell vehicle adoption and government hydrogen infrastructure funding fueling demand
Growing adoption of hydrogen-powered vehicles across passenger, transit, and commercial fleet segments remains the primary structural driver of storage tank demand, as governments worldwide set ambitious net-zero emissions targets that place transportation decarbonization under intense policy pressure.
Expanding government capital funding for hydrogen refueling and storage infrastructure, including regional clean hydrogen hub programs across North America, Europe, and Asia, continues to provide the project financing certainty needed to move storage and transportation infrastructure from planning into commercial deployment.
Rising commercial fleet interest in hydrogen fuel cell technology for long-haul trucking and transit bus applications is expanding demand beyond passenger vehicles into heavier-duty use cases requiring larger, more sophisticated onboard storage systems.
Continued technology improvements in storage density and tank manufacturing cost reduction are steadily improving the economics of hydrogen storage relative to competing zero-emission technologies, broadening the range of applications for which hydrogen storage investment is commercially justified.
Growing corporate fleet decarbonization commitments among logistics and transportation companies continue to expand pilot and early commercial deployment of hydrogen fuel cell trucks, creating incremental demand for both onboard storage tanks and supporting refueling infrastructure.
Restraints: High-pressure infrastructure costs and hydrogen embrittlement risk limiting broader adoption
The storage of hydrogen gas in a pressurized form necessitates the use of pressurized tanks, which significantly raises the cost of refueling and storage compared to other fuel storage systems, leading to a permanent cost obstacle that hampers further infrastructure development even with constant financial backing by governments.
The embrittlement properties of hydrogen make some metals brittle, posing an engineering challenge with respect to choosing appropriate materials and regular maintenance.
Limited existing hydrogen refueling and distribution infrastructure in most regions outside early-adopter markets continues to create a chicken-and-egg problem, where insufficient infrastructure slows vehicle adoption while insufficient vehicle demand slows infrastructure investment.
Competing battery electric vehicle technology continues to capture a larger share of near-term commercial fleet decarbonization investment in many markets, given battery technology's more mature charging infrastructure and lower current total cost of ownership for shorter-range applications.
Opportunities: Heavy-duty fleet electrification and export infrastructure development widening addressable demand
Rapid growth in heavy-duty and long-haul trucking fleet interest in hydrogen fuel cell technology presents a significant opportunity for storage tank manufacturers, as this application requires substantially larger and more sophisticated onboard storage systems than passenger vehicles.
Expanding green hydrogen export corridor development between low-cost renewable resource regions and hydrogen-importing markets in Europe and Asia presents a substantial opportunity for large-scale stationary storage and cryogenic transportation infrastructure providers.
Continued technology development in solid-state and metal hydride storage presents a longer-term opportunity for manufacturers to offer higher-density storage alternatives to conventional compressed gas and cryogenic liquid systems, particularly for space-constrained mobile applications.
Growing interest in hydrogen rail and maritime applications presents an emerging opportunity for storage tank manufacturers beyond road vehicle applications, as rail operators and shipping companies evaluate hydrogen fuel cell propulsion for routes where full electrification remains impractical.
Growing interest among industrial gas companies in offering hydrogen-as-a-service subscription models presents an opportunity for storage and transportation equipment suppliers to secure long-term equipment leasing contracts rather than relying solely on one-time equipment sales.
Recent Developments
-
In 2024, Hexagon Purus expanded its Type IV composite tank manufacturing capacity in Norway and the United States to serve growing fuel cell vehicle and mobile storage demand.
-
In 2023, Worthington Industries announced expanded hydrogen storage tank production capacity targeting both stationary industrial storage and mobile transportation applications in North America.
-
In 2024, Plastic Omnium expanded its hydrogen storage systems division, introducing new Type IV tank platforms for commercial vehicle manufacturers transitioning fleet segments to fuel cell power.
-
In 2024, NPROXX expanded its high-pressure hydrogen storage tank manufacturing facility in the Netherlands to serve growing European fuel cell bus and heavy-duty vehicle fleet demand.
-
In 2023, Doosan Mobility Innovation announced expanded hydrogen fuel cell drone and portable storage system development, targeting defense and industrial inspection applications requiring lightweight, high-density hydrogen storage.
-
In 2023, BayoTech Inc. announced expanded modular hydrogen production and storage system deployment aimed at serving distributed, on-site hydrogen generation applications for industrial and transportation customers.
Hydrogen Storage Tanks and Transportation key players are:
-
Hexagon Purus
-
Worthington Industries
-
Plastic Omnium
-
Luxfer Gas Cylinders
-
NPROXX
-
Quantum Fuel Systems
-
Steelhead Composites
-
BayoTech Inc.
-
Composite Advanced Technologies
-
Doosan Mobility Innovation
-
Tenaris S.A.
-
Umoe Advanced Composites
-
Weldship Corporation
-
Mahytec
-
Pragma Industries
-
ECS GmbH & Co. KG
-
Marine Service Noord
-
Hensoldt AG
-
Faber Industrie S.p.A.
-
Everest Kanto Cylinder Ltd.
Hydrogen Storage Tanks and Transportation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.70 Billion |
| Market Size by 2035 | USD 19.60 Billion |
| CAGR | CAGR of 28.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Tank Type (Type I, Type II, Type III, Type IV) • By Material (Metal, Glass Fiber, Carbon Fiber) • By Application (Fuel Cell Vehicles, Stationary Storage, Transportation & Distribution) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Hexagon Purus, Worthington Industries, Plastic Omnium, Luxfer Gas Cylinders, NPROXX, Quantum Fuel Systems, Steelhead Composites, BayoTech Inc., Composite Advanced Technologies, Doosan Mobility Innovation, Tenaris S.A., Umoe Advanced Composites, Weldship Corporation, Mahytec, Pragma Industries, ECS GmbH & Co. KG, Marine Service Noord, Hensoldt AG, Faber Industrie S.p.A., Everest Kanto Cylinder Ltd. |
Frequently Asked Questions
Leading companies include Hexagon Purus, Worthington Industries, Plastic Omnium, Luxfer Gas Cylinders, and NPROXX, among other major composite tank and industrial gas storage manufacturers.
Opportunities include rapid growth in heavy-duty and long-haul trucking fleet interest in hydrogen fuel cell technology, expanding green hydrogen export corridor infrastructure development, and continued technology development in solid-state and metal hydride storage systems.
Growth is driven by growing adoption of hydrogen-powered vehicles, expanding government capital funding for hydrogen infrastructure, and rising commercial fleet interest in hydrogen fuel cell technology for long-haul trucking and transit applications.
Type III dominates by tank type with approximately 48.6% share, Metal dominates by material with roughly 57.4% share, and Stationary Storage dominates by application with about 41.2% share; Type IV, Carbon Fiber, and Fuel Cell Vehicles are the fastest-growing segments within their respective categories.
North America is the largest regional market, led by the United States, while Asia Pacific, led by China, is the fastest-growing region through 2035.
