
Immunotherapy Drugs Market Report Scope & Overview:
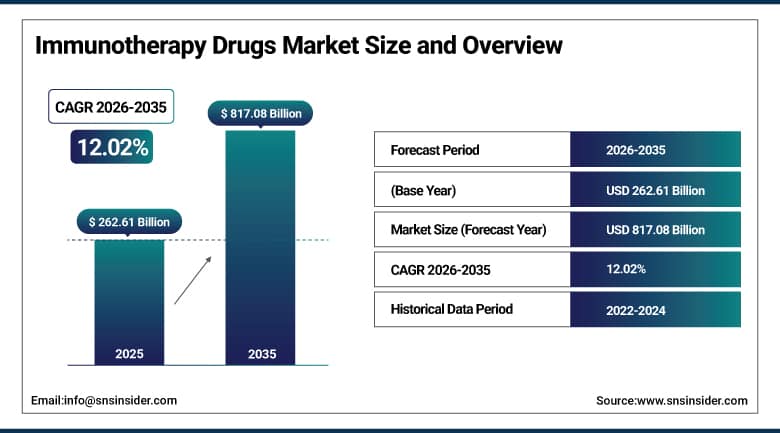
The Immunotherapy Drugs Market was valued at USD 262.61 Billion in 2025 and is expected to reach USD 817.08 Billion by 2035, growing at a CAGR of 12.02% from 2026-2035.
The Immunotherapy Drugs Market is expanding as drugs that train the immune system become standard care in cancer and autoimmune disease. Checkpoint inhibitors and other monoclonal antibodies account for most sales. Cell therapies such as CAR-T are growing from a small base, and bispecific antibodies are entering earlier lines of treatment. Subcutaneous versions of leading antibodies shorten infusion visits and widen access. Biomarker testing helps match patients to treatment. Cost, side effects and patent expiry create pricing pressure, yet new combinations keep adding indications. Approvals in China and Europe are broadening the patient pool. The market is expected to grow at a steady double-digit pace.
⮞In February 2024, the International Agency for Research on Cancer reported about 20 million new cancer cases and 9.7 million cancer deaths worldwide in 2022. The burden shows the scale of patient need that immune-based treatments aim to address.
To Get More Information On Immunotherapy Drugs Market - Request Free Sample Report
Immunotherapy Drugs Market Trends:
-
Subcutaneous formulations of checkpoint inhibitors replacing hospital infusions
-
Bispecific antibodies and T-cell engagers moving into earlier treatment lines
-
CAR-T and cell therapies expanding into autoimmune disease
-
Personalized cancer vaccines combined with checkpoint inhibitors in late-stage trials
-
Chinese-developed immunotherapies gaining approvals and global licensing deals
U.S. Immunotherapy Drugs Market Outlook:
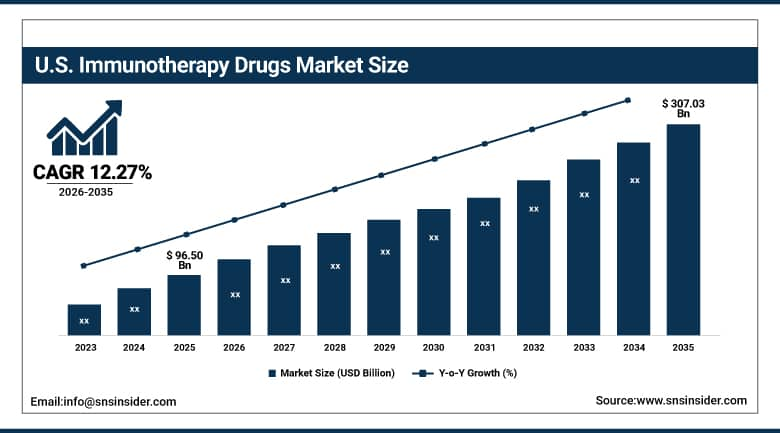
The U.S. Immunotherapy Drugs Market was valued at USD 96.50 Billion in 2025 and is expected to reach USD 307.03 Billion by 2035, growing at a CAGR of 12.27% from 2026-2035.
The U.S. Immunotherapy Drugs Market is the largest national market, supported by high cancer incidence, early access to new drugs and strong insurance coverage. The Food and Drug Administration approves new indications at a steady pace, often through accelerated pathways. Checkpoint inhibitors lead sales, and cell therapies and bispecifics are growing. Oncology centers have the staff to deliver complex treatments. Medicare coverage supports use among older patients. Drug pricing reform and biosimilar entry will add pressure later in the decade. Treatment cost and safety monitoring remain hurdles. Growth is expected to stay strong as new combinations reach the clinic. The growth is expected to stay strong as new combinations reach the clinic and coverage widens.
⮞In January 2026, the American Cancer Society projected about 2,114,850 new cancer cases and 626,140 cancer deaths in the United States for 2026, with a five-year survival rate of 70%. The numbers show the large patient base served by immunotherapy drugs.
Immunotherapy Drugs Market Segment Analysis:
-
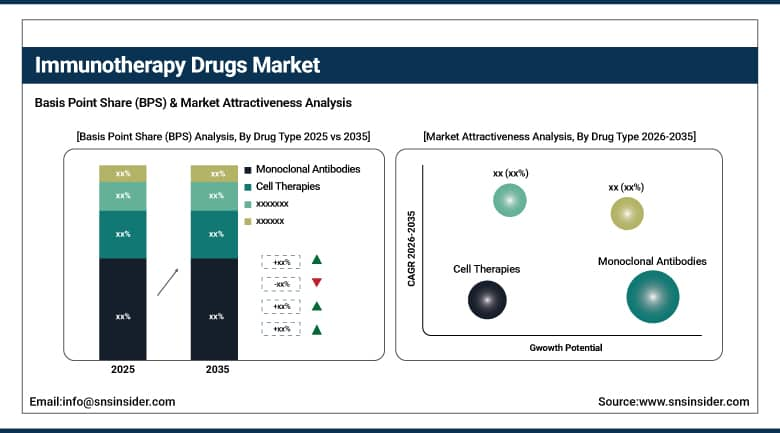
By Drug Type, the Monoclonal Antibodies segment dominated the Immunotherapy Drugs Market with approximately 71.42% share in 2025, while the Cell Therapies segment is the fastest growing with a CAGR of approximately 24.92%.
-
By Therapy Area, the Cancer segment dominated the Immunotherapy Drugs Market with approximately 90.42% share in 2025, while the Autoimmune and Inflammatory Diseases segment is the fastest growing with a CAGR of approximately 12.45%.
-
By Route of Administration, the Intravenous segment dominated the Immunotherapy Drugs Market with approximately 85.40% share in 2025, while the Subcutaneous segment is the fastest growing with a CAGR of approximately 16.40%.
-
By End User, the Hospitals and Clinics segment dominated the Immunotherapy Drugs Market with approximately 45.15% share in 2025, while the Research Laboratories segment is the fastest growing with a CAGR of approximately 14.36%.
By Drug Type, Monoclonal Antibodies Dominates the Immunotherapy Drugs Market and Cell Therapies Grows Fastest
Monoclonal antibodies lead because checkpoint inhibitors such as pembrolizumab and nivolumab are used across many tumor types and many treatment lines. Each new indication adds patients and extends treatment duration. Antibodies are made at scale with established processes, and oncologists know how to give them and manage side effects. Combination regimens with chemotherapy or targeted drugs raise use further. Autoimmune and inflammatory antibodies add large volumes beyond cancer. The size of the installed prescriber base and the strength of clinical evidence keep this drug type far ahead of other classes. Biosimilar versions of older antibodies also expand volume in lower-cost markets.
Cell therapies are the fastest growing type because CAR-T and T-cell products are moving from late-line blood cancers to earlier treatment and new diseases. Approved products now include therapies for lymphoma, myeloma and melanoma, and trials are testing them in lupus and other autoimmune diseases. Manufacturing capacity and treatment site networks are expanding. Prices are high, so revenue grows quickly even with modest patient numbers. Vaccines, interferons and interleukins remain smaller segments, with cancer vaccines and engineered cytokines drawing renewed research investment. Engineered cytokines aim to improve the balance between benefit and toxicity.
⮞In February 2026, Bristol Myers Squibb reported fiscal 2025 Opdivo sales of USD 10,049 million, of which USD 5,904 million came from the United States. The figure shows the commercial weight of a single checkpoint inhibitor in this market.
By Therapy Area, Cancer Dominates the Immunotherapy Drugs Market and Autoimmune and Inflammatory Diseases Grows Fastest
Cancer leads because immune checkpoint blockade changed standard care in lung cancer, melanoma, kidney cancer, bladder cancer and many other tumors. Oncology trials keep adding combinations and earlier-stage uses, such as treatment before and after surgery. High prices per patient and long treatment courses give oncology the largest revenue pool. Payers cover the drugs because survival benefit is well documented. Diagnostic tests that measure PD-L1 or mismatch repair status help select patients and support wider use across hospitals.across hospitals. Pathology laboratories also adopt standardized reporting.
Autoimmune and inflammatory diseases are growing fastest as immune-modulating drugs reach rheumatology, dermatology, gastroenterology and neurology. Antibodies that block inflammatory signals are used for conditions such as psoriasis, arthritis and bowel disease, and cell therapies are being tested to reset the immune system in lupus and other disorders. Infectious disease applications, led by vaccines, add steady volume. Biosimilar competition limits price growth in older inflammatory antibodies, but new targets and long-acting forms keep demand rising. Pharmacogenomic and biomarker tests help physicians choose among competing options.
⮞Regeneron reported in January 2026 that Libtayo sales reached USD 1,453 million in 2025, up 19% from USD 1,217 million. The growth shows how newer checkpoint inhibitors are still gaining share in oncology.
By Route of Administration, Intravenous Dominates the Immunotherapy Drugs Market and Subcutaneous Grows Fastest
Intravenous delivery leads because most approved antibodies and cell therapies were developed for infusion, and hospital oncology units are set up to give them. Dosing by body weight and the need to monitor infusion reactions favor supervised settings. Clinicians have long experience with infusion protocols, and reimbursement for administration is well established. Large pivotal trials were run with intravenous dosing, which anchors labels and treatment guidelines. These factors keep infusion the main route even as alternatives appear. Infusion centers also bill for chair time, which supports facility interest.
Subcutaneous delivery is the fastest growing route as companies reformulate leading antibodies with enzymes that allow larger injection volumes. Injections take minutes instead of hours, which frees infusion chairs and shortens patient visits. Several checkpoint inhibitors and bispecific antibodies now have subcutaneous versions approved in the United States or Europe. Patients prefer faster visits, and health systems benefit from capacity gains. Oral immunomodulators remain a small route, and the main shift ahead is conversion of intravenous franchises to injected forms.
⮞In January 2026, Roche reported that the FDA approved Lunsumio VELO on 22 December 2025, cutting administration time from two to four hours to about one minute. The change shows the pace of the shift toward subcutaneous dosing.
By End User, Hospitals and Clinics Dominates the Immunotherapy Drugs Market and Research Laboratories Grows Fastest
Hospitals and clinics lead because immunotherapy drugs are given under specialist supervision, often with imaging, laboratory tests and emergency support nearby. Cancer centers run infusion suites and cell therapy units, and they manage the toxicity that immune treatments can cause. Hospital pharmacies buy and prepare most of the drugs.Hospital pharmacies buy and prepare most of the drugs. Teaching hospitals also run clinical trials that add early use. Community oncology clinics extend access, particularly as injections replace infusions. These sites handle the bulk of prescriptions and procedures.
Research laboratories are growing fastest as academic and company teams test new targets, cell engineering methods and combinations. Spending on discovery of antibodies, engineered T cells and vaccines is rising, and research institutes buy drugs and reagents for translational studies. Government and private funding of immuno-oncology remains high. Contract research and manufacturing groups support these programs. Retail and online pharmacies serve a small share, mainly for injected or oral products used for autoimmune conditions, and specialty pharmacies manage complex distribution. Core facilities at universities buy reagents and biologics for shared use.
⮞In February 2026, Iovance reported product revenue of about USD 263.5 million for fiscal 2025, including about USD 220 million from Amtagvi, a tumor-infiltrating lymphocyte therapy. The sales show hospital-based cell therapy reaching commercial scale.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
79.73 |
|
Europe |
Germany |
25.41 |
|
Asia Pacific |
China |
38.76 |
|
Latin America |
Brazil |
52.38 |
|
Middle East & Africa |
Saudi Arabia |
29.64 |
North America Immunotherapy Drugs Market Insights
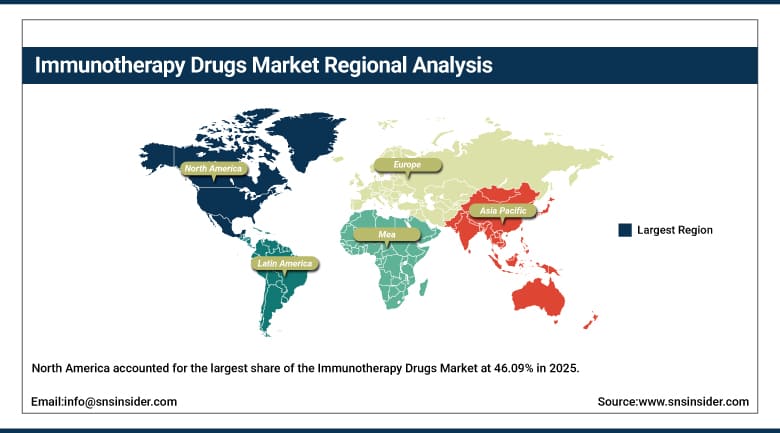
North America accounted for the largest share of the Immunotherapy Drugs Market at 46.09% in 2025, led by the United States. Leading developers such as Merck, Bristol Myers Squibb, Regeneron, Amgen and Gilead are based in the region, and many first launches occur there. High cancer incidence among an aging population, strong insurance coverage and a dense network of cancer centers support use. Canada adds demand through provincial programs that fund immunotherapy after health technology review. Mexico adds demand through public institutions and private insurers.
The Food and Drug Administration uses accelerated approval and breakthrough designations to bring new immunotherapies to patients quickly, and recent decisions have covered rectal cancer, melanoma and bladder cancer. Medicare and commercial insurers cover most approved uses, though prior authorization is common. Drug price negotiation and biosimilar entry are expected to change the revenue of top products. Cell therapy centers are expanding, Cell therapy centers are expanding, and outpatient delivery of injected products is growing. Community oncology networks are also adding capacity for injected products.
⮞In March 2026, Legend Biotech reported net trade sales of about USD 1.9 billion for Carvykti in 2025, with treatment at 294 sites in 14 markets. The network shows how cell therapy delivery is scaling across North America and beyond.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Immunotherapy Drugs Market Insights
Europe is among the largest region and is led by Germany, the United Kingdom, France, Italy and Spain. National health systems cover immunotherapies after assessments of clinical benefit, and uptake varies between countries. The region has strong cancer research networks and hosts developers such as Roche, AstraZeneca, GSK, Genmab and BeOne's European operations. Germany leads in volume because of broad access,Germany leads in volume because of broad access, while the United Kingdom's assessment body shapes use through guidance on cost effectiveness.
The European Medicines Agency approves products centrally, and recent decisions have included subcutaneous versions of leading antibodies. Health technology assessment rules are evolving through the joint clinical assessment process, which may speed access for new cancer drugs. Budget pressure and negotiated rebates restrain price growth. Hospitals are adding cell therapy capacity, though manufacturing and trained staff remain limited. Biosimilars of older inflammatory antibodies are widely used, which shifts spending toward newer products. Cancer screening programs that detect disease earlier also enlarge the group eligible for treatment.
⮞In November 2025, Merck announced that the European Commission approved subcutaneous Keytruda for all adult indications approved in the European Union, supported by a trial of 377 patients. The approval shows the region's move toward faster injected dosing.
Asia Pacific Immunotherapy Drugs Market Insights
Asia Pacific is expected to be the fastest growing region in terms of a CAGR of 13.64% during 2026-2035. China, Japan, India, South Korea and Australia will drive regional demand. There is an increase in incidences of cancer in ageing population along with increased government initiatives in insurance coverage of new cancer drugs. There is rapid growth in innovations from China with Akeso, BeOne and Legend as some players developing checkpoint inhibitors, bispecific antibodies and cell therapies. There is a developed market in Japan along with early adoption of drug classes. South Korea and Australia contribute towards demand by using national insurance schemes for innovative cancer drugs.
There is strong price competition in the region, especially in China where there is competition among local checkpoint inhibitors with imported ones along with negotiation on reimbursement prices. National Medical Products Administration is approving new immuno-oncology agents quickly while licensing deals are transferring Chinese assets to Western partners. India is providing access with local production of biosimilars and low-cost cell therapy. There is a lack of trained personnel and treatment centers outside big cities along with patient paying for themselves in several countries. Clinical trials in the region are increasing.
⮞In August 2026, Akeso announced that China's drug regulator approved ivonescimab with chemotherapy for first-line squamous non-small cell lung cancer, based on median progression-free survival of 11.1 months versus 6.9 months. The decision shows Chinese-developed bispecifics reaching the market.
MEA & Latin America Immunotherapy Drugs Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. The Americas record more than 4 million new cancer cases a year, and regional health bodies are urging better access to treatment. Brazil's regulator is approving new indications for checkpoint inhibitors, while public coverage is limited, so access depends on private insurance and court-ordered supply. Local production and technology transfer deals aim to lower prices. Biosimilar antibodies are growing in importance. Public purchasing agencies are beginning to negotiate bundled prices for oncology biologics.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Israel and South Africa lead demand. Gulf states are investing in cancer centers, genomics and local cell therapy programs, and Saudi hospitals have started trials of locally developed CAR-T products. In much of Africa, access to immunotherapy is very limited because of cost and weak diagnostic capacity. Pharmaceutical companies are using patient access programs and tiered pricing, and regional regulators are leaning on approvals from the United States and Europe. Medical tourism hubs in the Gulf also attract patients seeking advanced cancer care.
⮞In August 2025, the Saudi Food and Drug Authority announced the first Phase I trial of a locally developed CD19 CAR-T therapy for relapsed or refractory acute lymphoblastic leukemia at King Faisal Specialist Hospital. The trial shows regional ambitions in advanced cell therapy.
Market Dynamics:
Growth Drivers: Rising Cancer Burden and Expanding Approvals Drive Growth in the Immunotherapy Drugs Market
Rising cancer incidence is the main source of demand. Aging populations and longer survival increase the number of patients who may receive immune-based treatment during their illness. Checkpoint inhibitors now have approvals in dozens of tumor types, and new indications keep arriving, often earlier in the disease course. Longer treatment duration and combination regimens raise revenue per patient. Biomarker testing helps identify responders, which improves outcomes and supports payer coverage of these costly drugs. Real-world data from large registries further supports label expansion.
Pipeline strength and regulatory support add momentum. Bispecific antibodies, T-cell engagers, cell therapies and cancer vaccines are advancing through late-stage trials. Regulators offer breakthrough designations, accelerated approval and priority review, which shortens time to market. Companies are investing heavily in subcutaneous forms, new targets and combinations. Licensing and acquisition deals bring in assets from China and small biotechnology firms. Expansion into autoimmune disease opens a second large market for immune-modulating drugs. Combination studies with antibody-drug conjugates are another source of new uses.
⮞In November 2025, Amgen announced FDA traditional approval of Imdelltra for extensive-stage small cell lung cancer, based on a median overall survival of 13.6 months versus 8.3 months in 509 patients. The result shows how new immune-engaging drugs are improving outcomes in hard-to-treat cancers.
Restraints: High Treatment Cost and Competitive Pressure Restrain Growth in the Immunotherapy Drugs Market
High cost and barriers to reimbursement create access issues. The yearly cost of treatment using checkpoint inhibitors is high, and cellular therapy may cost a few hundred thousand dollars per patient in addition to hospitalization and monitoring costs. Insurance companies use prior authorizations and approve treatments only when the indications are approved. Public health care systems in developing nations cannot afford to cover their populations, and thus, there is late or lack of treatment among their patients. Medication cost management programs and tendering programs create price pressures.
Safety and competition add further constraints. Immune-related adverse events such as colitis and pneumonitis require monitoring and can lead to stopped treatment. Cell therapy requires specialized centers, long manufacturing times and trained staff, which restrict volume. Many patients do not respond or develop resistance. Patent expiry of leading antibodies invites biosimilars, and crowded pipelines in the same targets reduce pricing power.invites biosimilars, and crowded pipelines in the same targets reduce pricing power. Manufacturing complexity for biologics and cell products also raises cost of goods. Supply of viral vectors and cell culture media can also constrain output.
⮞In February 2026, Gilead Sciences reported that its cell therapy sales fell 7% to USD 1.8 billion in 2025, with Yescarta down 5% and Tecartus down 15% amid rising competition. The decline shows the commercial pressure facing first-generation cell therapies.
Opportunities: In Vivo Cell Therapy and Subcutaneous Conversion Create Opportunities in the Immunotherapy Drugs Market
There is potential in vivo cellular therapy and autoimmune expansion. In vivo delivery of genetic instructions may eliminate the need for costly and time-consuming manufacture of cells, and initial programs focus on B-cell-driven autoimmune conditions. It will expand potential patient populations from thousands to millions. Large pharmaceutical companies are acquiring platform companies to get access. Also, allogeneic and off-the-shelf cellular products are gaining momentum; this may lead to cost reduction and increased availability through community health centers. Contract manufacturers’ partnerships may help to cut capital expenses of small developers.
Subcutaneous administration and emerging markets present more potential. Re-formulation of leading antibodies for subcutaneous injection will protect franchises from competition when patents expire and be convenient for patients. Also, the company can use combination approaches to expand indications to first-line indications. Emerging markets in Asia, Latin America and the Middle East have increasing cancer burden and increasing capacity of hospitals. Local production, tiered pricing, technology transfer can increase accessibility. Also, there is potential in bispecific antibodies from Chinese developers that allow licensing and co-development deals. There is cancer vaccine platform that uses personalized tumors' mutations.
⮞In August 2025, AbbVie completed its acquisition of Capstan Therapeutics, whose lead program is an in vivo CD19 CAR-T therapy in Phase 1 for B-cell driven autoimmune disease. The deal shows large drugmakers investing in the next generation of cell therapy.
Recent Developments:
-
In August 2026, BeOne Medicines announced FDA approval of Tevimbra combined with zanidatamab, developed with Jazz, for HER2-positive gastric and gastroesophageal junction cancer. The combination showed median overall survival of 26.4 months versus 19.2 months in the pivotal trial.
-
In August 2026, Replimune announced FDA accelerated approval of Tudriqev, an oncolytic virus, in combination with nivolumab for melanoma. The approval was based on an objective response rate of 24.2% and a median duration of response of 14.1 months.
-
In October 2026, ImmunityBio announced that the FDA expanded the approved use of Anktiva with BCG to high-grade papillary-only bladder cancer. The decision followed a complete response rate of 62% in 77 patients and widens the treatable population.
-
In October 2026, GSK announced FDA accelerated approval of Jemperli for locally advanced mismatch repair deficient rectal cancer. The approval was supported by a sustained clinical complete response rate of 47% at 12 months in 154 treated patients.
Immunotherapy Drugs Market Key Players are:
-
Merck & Co., Inc.
-
Bristol Myers Squibb Company
-
F. Hoffmann-La Roche Ltd (Genentech)
-
AstraZeneca PLC
-
Regeneron Pharmaceuticals, Inc.
-
GSK plc
-
Amgen Inc.
-
Johnson & Johnson (Janssen)
-
Gilead Sciences, Inc. (Kite)
-
Legend Biotech Corporation
-
BeOne Medicines Ltd.
-
Immunocore Holdings plc
-
Iovance Biotherapeutics, Inc.
-
Akeso, Inc.
-
Genmab A/S
-
ImmunityBio, Inc.
-
Coherus Oncology, Inc.
-
Replimune Group, Inc.
Immunotherapy Drugs Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 262.61 Billion |
| Market Size by 2035 | USD 817.08 Billion |
| CAGR | CAGR of 12.02% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Drug Type (Monoclonal Antibodies, Vaccines, Cell Therapies, Interferons and Interleukins, and Others) • By Therapy Area (Cancer, Autoimmune and Inflammatory Diseases, Infectious Diseases, and Others) • By Route of Administration (Intravenous, Subcutaneous, and Others) • By End User (Hospitals and Clinics, Research Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Merck & Co., Inc., Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd (Genentech), AstraZeneca PLC, Regeneron Pharmaceuticals, Inc., GSK plc, Amgen Inc., Johnson & Johnson (Janssen), Gilead Sciences, Inc. (Kite), Legend Biotech Corporation, BeOne Medicines Ltd., Immunocore Holdings plc, Iovance Biotherapeutics, Inc., Akeso, Inc., Genmab A/S, ImmunityBio, Inc., Coherus Oncology, Inc., Replimune Group, Inc. |

Frequently Asked Questions
Key players include Merck, Bristol Myers Squibb, Roche, AstraZeneca, Regeneron, GSK, Amgen, Johnson & Johnson, Gilead Sciences, Legend Biotech, BeOne Medicines, Immunocore, Iovance Biotherapeutics, Akeso, Genmab, ImmunityBio, Coherus Oncology and Replimune.
Key opportunities include in vivo and off-the-shelf cell therapies, expansion into autoimmune disease, subcutaneous reformulation of leading antibodies and growth in emerging markets.
Rising cancer incidence, together with expanding approvals of checkpoint inhibitors, bispecific antibodies and cell therapies, is the main growth factor.
By Drug Type, the Monoclonal Antibodies segment dominated the market in 2025 with an estimated 71.42% share, supported by wide use of checkpoint inhibitors across tumor types.
North America dominated the market with a share of 46.09% in 2025, driven by high cancer incidence, early access to new drugs and strong insurance coverage.
