
Industrial Diesel Turbocharger Market Report Scope & Overview:
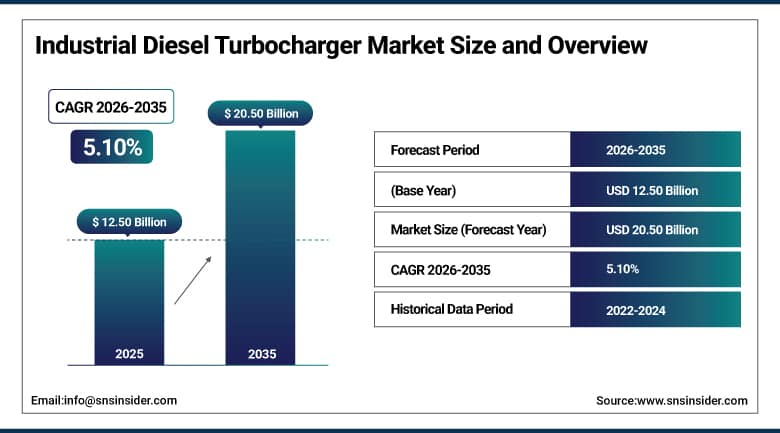
The Industrial Diesel Turbocharger Market was valued at USD 12.50 Billion in 2025 and is expected to reach USD 20.50 Billion by 2035, growing at a CAGR of 5.10% from 2026–2035.
Industrial diesel turbochargers are mechanical components that increase engine power output by forcing additional compressed air into the combustion chamber, allowing better fuel combustion and improved efficiency across marine, power generation, construction, mining, and agricultural equipment applications. Diesel engines are normally used in these industrial settings for their high torque, fuel efficiency, and durability compared to gasoline alternatives, and turbochargers are essential to helping these engines meet strict emission regulations while enhancing performance under heavy, continuous-duty loads. The market continues evolving in response to technological advancements and sustainability initiatives, as OEMs work to downsize engines while enhancing thermal efficiency.
Cummins launched the industry's first turbocharger designed specifically for hydrogen internal combustion engines in January 2025, securing a contract to supply the variable geometry unit to a major European OEM building the first hydrogen-powered heavy-duty on-highway engine for the European market. Hydrogen combustion produces far more water vapor than diesel exhaust and behaves differently at every airflow rate, so Cummins had to redesign the turbocharger's aerodynamics essentially from scratch rather than simply adapting an existing diesel unit, a genuinely different engineering challenge than the incremental improvements that usually define this category.
To Get More Information On Industrial Diesel Turbocharger Market - Request Free Sample Report
Industrial Diesel Turbocharger Market Trends:
-
Rising development of hydrogen-capable turbocharger designs supporting the transition toward zero-tailpipe-emission heavy-duty and off-highway engines
-
Growing adoption of variable geometry turbochargers offering superior fuel efficiency improvements and performance optimization across engine operating ranges
-
Increasing integration of two-stage turbocharging technology for enhanced engine performance and reliability in demanding off-highway applications
-
Rapid replacement demand for stricter emissions compliance and fleet upgrades across mining, genset, and marine retrofit markets
-
Growing electronically actuated wastegate technology enabling more precise boost control and improved fuel efficiency
-
Expanding aftermarket channels and close OEM/engine platform integration supporting product innovation across the industry
U.S. Industrial Diesel Turbocharger Market Outlook:
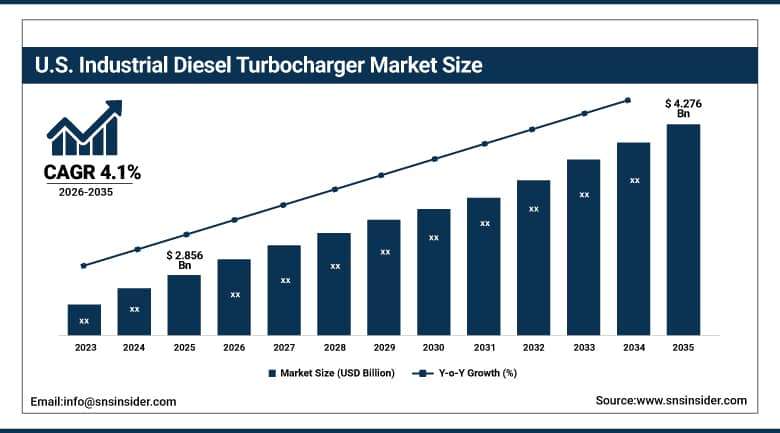
The U.S. Industrial Diesel Turbocharger Market was valued at approximately USD 2.856 Billion in 2025 and is expected to reach approximately USD 4.276 Billion by 2035, growing at a CAGR of approximately 4.1%.
The U.S. market grows due to rising demand for fuel-efficient, low-emission engines in industries like construction and power generation, with power generation holding a significant application share given the need for reliable and cost-effective power sources, especially in remote areas and for backup power applications. Diesel engines continue offering better fuel economy and durability compared to gasoline engines, further driving their preference in domestic industrial settings. Technological advancements, including variable geometry turbochargers, have enhanced diesel engine performance, making them more efficient and environmentally friendly across the construction, mining, and agricultural equipment sectors.
Garrett Motion was selected by a major global equipment manufacturer to supply two-stage turbo technology for a hydrogen-powered internal combustion engine built specifically for large-scale earthmoving and construction machinery, with the engine slated for a 2025 market debut across operations in Australia, Central Asia, and Europe. The two-stage design splits compression work between two separate turbochargers to deliver highly pressurized air at optimal efficiency, and the resulting engine is designed to match traditional diesel performance while emitting essentially zero tailpipe CO2, a combination that matters enormously for construction equipment operators who can't simply wait for battery-electric machinery to catch up to diesel's power density.
Industrial Diesel Turbocharger Market Segment Analysis:
-
By Engine Type, the Diesel Engine segment dominated the Industrial Diesel Turbocharger Market with approximately 52.60% share in 2025, while the Dual Fuel Engine segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Component Type, the Turbine segment dominated the Industrial Diesel Turbocharger Market with approximately 31.50% share in 2025, while the Actuators segment is the fastest growing with a CAGR of approximately 7.40%.
-
By Technology, the Wastegate/Fixed Geometry segment dominated the Industrial Diesel Turbocharger Market with approximately 61.50% share in 2025, while the Variable Geometry Turbocharger segment is the fastest growing with a CAGR of approximately 6.70%.
-
By Application, the Marine segment dominated the Industrial Diesel Turbocharger Market with approximately 34.60% share in 2025, while the Power Generation segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Sales Channel, the OEM Sales segment dominated the Industrial Diesel Turbocharger Market with approximately 58.40% share in 2025, while the Online Sales segment is the fastest growing with a CAGR of approximately 7.80%.
By Engine Type, Diesel Engine dominates, Dual Fuel Engine grows fastest
Diesel engines had the greatest market share for engine-type in 2025 due to their high torque, fuel economy, and durability as compared to gasoline engines and other types of engines, especially in marine, power generation, and heavy duty equipment. The attributes of diesel engines such as high torque, fuel economy, and durability ensure that they continue to dominate the engine-type category of the larger turbochargers market for industries.
The dual fuel engines have the highest growth rate because of the rise in demand for engines that can be used with both diesel and alternate fuels like natural gas or hydrogen to ensure that the emission requirements are met while not having to abandon the diesel engines altogether. Regulatory pressures on emissions in the marine and power generation industry continue to contribute to this above-average growth rate.
By Component Type, Turbine dominates, Actuators grows fastest
The turbine was the largest individual component type in 2025, being the essential mechanical part used to convert the energy from the exhaust gas into the torque that turns the compressor section in each turbocharger unit. The inherent nature of its critical role in the process ensures that the turbine remains the largest individual component type revenue-wise in the wider industrial diesel turbocharger industry.
Actuators are growing at the fastest rate because of the increasing prevalence of electronically actuated variable geometry and wastegate systems that replace simple mechanical actuators and contribute to better fuel economy and boost pressure control in advanced turbocharger systems. Increasing demand for electronically controlled boost pressure management drives this above-average growth trend.
By Technology, Wastegate/Fixed Geometry dominates, VGT grows fastest
Wastegate and fixed geometry turbochargers held the largest share of the technology segment in 2025, remaining the proven, cost-effective standard across the majority of industrial diesel engine applications where simpler boost control adequately meets performance requirements. That combination of reliability and lower manufacturing cost keeps fixed geometry designs the dominant technology category across the broader industrial diesel turbocharger market.
Variable geometry turbochargers are growing fastest as these systems offer superior fuel efficiency improvements of meaningful magnitude and optimal performance optimization across engine operating ranges, making them increasingly preferred over traditional wastegate systems. Rising demand for improved fuel economy and tighter emissions compliance continues reinforcing this above-average growth trajectory relative to the broader, fixed-geometry-dominated technology mix.
By Application, Marine dominates, Power Generation grows fastest
The marine segment held the largest share of the application segment in 2025, driven by dominant shipbuilding industries across major maritime nations that continue specifying turbocharged diesel engines for both propulsion and auxiliary power aboard commercial and naval vessels. That combination of scale and established maritime engineering standards keeps marine the dominant application category across the broader industrial diesel turbocharger market.
Power generation is emerging as the fastest-growing application as turbochargers in power generation improve the efficiency of diesel gensets, vital for industrial backup power and rural electrification across both developed and emerging markets. Around a substantial share of diesel power units integrate turbochargers to boost output, and rising demand for reliable backup power infrastructure continues reinforcing this above-average growth trajectory relative to the broader, marine-dominated application mix.
By Sales Channel, OEM Sales dominates, Online Sales grows fastest
OEM sales accounted for the largest share of the sales-channel segment in 2025, reflecting how industrial diesel turbochargers are overwhelmingly specified and installed during original engine assembly rather than purchased separately after the fact. That deep integration between turbocharger specification and overall engine platform engineering keeps OEM sales the dominant distribution pathway across nearly every turbocharger category.
Online sales are growing fastest as smaller equipment operators and independent service providers increasingly source replacement turbochargers and components through digital industrial supply platforms rather than negotiating direct manufacturer relationships. That channel shift is particularly pronounced among smaller businesses that don't have the purchasing volume to command favorable direct-supply contract terms from the largest turbocharger manufacturers.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.60% |
|
Europe |
Germany |
25.20% |
|
Asia Pacific |
China |
40.60% |
|
Latin America |
Brazil |
34.80% |
|
Middle East & Africa |
Saudi Arabia |
30.20% |
Asia Pacific Industrial Diesel Turbocharger Market Insights
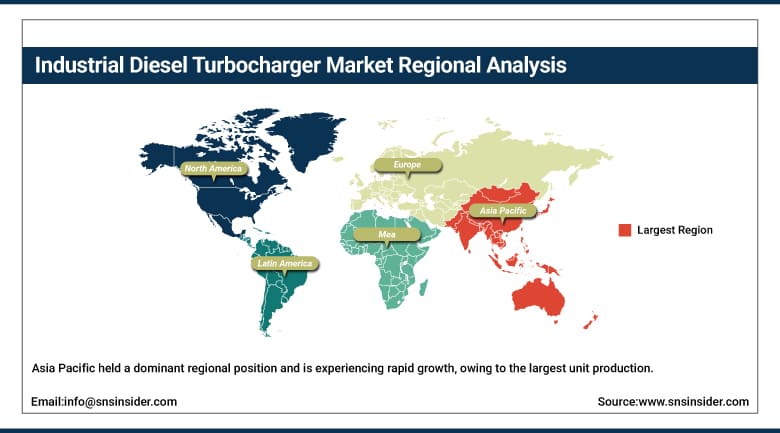
Asia Pacific held a dominant regional position and is experiencing rapid growth, owing to the largest unit production and demand for industrial engines, alongside strong construction and mining equipment markets across the region's largest economies. Rapidly expanding industrial manufacturing and infrastructure development across China and India continue reinforcing this accelerating growth trajectory.
China's massive industrial engine manufacturing base gives the region substantial baseline demand, while India's rapidly expanding construction and mining equipment sector is drawing significant new investment in turbocharger production capacity. Japan and South Korea represent more mature, technology-forward markets with established marine and power generation turbocharger standards, while Southeast Asian markets continue following a similar industrialization-driven growth trajectory.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Industrial Diesel Turbocharger Market Insights
North America remains the largest market for industrial diesel turbochargers, supported by rapid replacement activity driven by stricter emissions compliance and fleet upgrades across mining, genset, and marine retrofit markets throughout the region. Deep concentration of the world's largest turbocharger manufacturers and engine platform integrators continues reinforcing this leading position across the broader region.
Canada contributes additional demand through its own mining and power generation sector, while Mexico's market continues expanding alongside growing nearshoring-driven industrial manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production networks.
Europe Industrial Diesel Turbocharger Market Insights
Europe is a well-developed and regulation-driven market for industrial diesel turbochargers, influenced by regulations that keep forcing manufacturers to adopt innovative turbocharger technology and eco-friendly diesel and dual-fuel engines architecture. Germany is the main demand driver in the region, which has a significant base of industrial engine production, along with turbocharger manufacturers possessing significant engineering competencies.
The Nordic countries, including Norway, provide notable demand, especially in the maritime segment, supported by sophisticated maritime technologies and rising need for eco-friendly vessels. The regional focus on hydrogen-powered and dual-fuel turbocharger technology influences product development in the region to a greater degree than anywhere else in the world.
MEA & Latin America Industrial Diesel Turbocharger Market Insights
The Middle East and Africa represent a smaller but strategically developing industrial diesel turbocharger market, with Saudi Arabia driving demand through substantial infrastructure investment and expanding industrial machinery deployment tied to the country's broader economic diversification and construction expansion goals. Growth elsewhere in the region remains tied closely to the pace of broader industrial machinery and construction infrastructure development.
Latin America is a growing market led by Brazil, where expanding mining, agricultural equipment, and power generation sectors continue driving demand for industrial diesel turbochargers. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing industrial manufacturing sectors.
Market Dynamics:
Growth Drivers: Emission regulation compliance and fuel efficiency demand fueling adoption
Strict laws on emission controls can be counted among the driving factors contributing to the growth in industrial demand for diesel turbochargers due to the increasingly stringent laws and requirements on exhaust emissions control that can be better fulfilled by turbocharged engines because of their complete combustion as opposed to naturally-aspirated engines. The growing demand for energy efficiency is adding another factor to the demand for turbochargers.
The need for improved fuel efficiency in industrial diesel engines adds a second major driver, alongside OEM efforts to downsize and enhance thermal efficiency across construction, mining, marine, and power generation equipment platforms. Increasing demand for power generation and growing construction and infrastructure development worldwide continue reinforcing this demand base across nearly every major industrial and energy market.
Restraints: High capital costs and hydrogen engineering complexity limiting deployment pace
High capital costs associated with advanced turbocharger technology, particularly two-stage and hydrogen-capable designs, continue to require substantial engineering and capital investment that can compete with other equipment upgrade priorities within operator capital planning processes. That cost sensitivity can slow adoption even among operators who recognize the genuine performance and emissions advantages these advanced systems offer.
Hydrogen engineering complexity adds a further restraint, since hydrogen combustion behaves fundamentally differently from diesel combustion at every airflow rate and produces substantially more water vapor, requiring turbocharger manufacturers to redesign aerodynamics and materials essentially from scratch rather than adapting existing diesel platforms. That technical complexity continues limiting how quickly hydrogen-capable turbocharger technology can scale to broader commercial deployment.
Opportunities: Hydrogen combustion engine expansion and off-highway electrification hybrid opportunities opening new growth avenues
Hydrogen combustion engine expansion offers manufacturers a genuine path to capturing premium business from OEMs seeking zero-tailpipe-emission alternatives to battery-electric power for applications where battery energy density still falls short of diesel's performance. Companies that build strong hydrogen-specific turbocharger engineering capability are positioned to capture disproportionate growth as this application category continues expanding from pilot programs into genuine commercial deployment.
Off-highway and construction equipment electrification-hybrid opportunities represent a second significant opportunity, as manufacturers develop two-stage and variable geometry turbochargers optimized for hybrid diesel-electric powertrains combining conventional engine efficiency with electrified assist. Manufacturers that build genuine hybrid-compatible turbocharger technology are positioned to capture premium pricing from equipment makers bridging the gap toward full electrification.
Recent Developments:
-
In January 2025, Cummins launched its industry-first hydrogen internal combustion engine turbocharger, securing a supply contract with a major European OEM for heavy-duty on-highway applications.
-
In February 2025, BorgWarner extended wastegate turbocharger contracts with a major North American OEM, covering midsized gasoline engine platforms with production continuing through 2028 and beyond.
-
In July 2025, BorgWarner secured a wastegate turbocharger contract to supply a major global OEM's hybrid sports car platform, with production expected to begin in the third quarter of 2028.
-
In 2024 and 2025, Garrett Motion continued advancing its H2-ICE two-stage turbo technology program for off-highway construction and earthmoving equipment, targeting a 2025 market debut.
Industrial Diesel Turbocharger Market Key Players:
-
Honeywell International Inc.
-
BorgWarner Inc.
-
Cummins Inc.
-
Mitsubishi Heavy Industries, Ltd.
-
IHI Corporation
-
Garrett Motion Inc.
-
Continental AG
-
Weifang Deli Turbocharger Co., Ltd.
-
Accelleron Industries (ABB Turbocharging)
-
MAN Energy Solutions
-
Wabtec Corporation
-
Caterpillar Inc.
-
Rotomaster International
-
Turbo Energy Private Limited
-
Precision Turbo & Engine
-
Cummins Turbo Technologies (Holset)
-
Schwitzer
-
Elgin Industries
-
Bosch Mahle Turbo Systems
-
Sonalika Group
Industrial Diesel Turbocharger Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 12.50 Billion |
| Market Size by 2035 | USD 20.50 Billion |
| CAGR | CAGR of 5.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Engine Type (Internal Combustion Engine, Diesel Engine, Natural Gas Engine, Dual Fuel Engine, Heavy Fuel Engine) • by Component Type (Bearing Systems, Compressor, Turbine, Wastegate, Actuators) • by Technology (Variable Geometry Turbocharger, Wastegate/Fixed Geometry, Two-Stage) • by Application (Marine, Power Generation, Construction Equipment, Mining, Agricultural Equipment) • by Sales Channel (Direct Sales, Distributor Sales, Online Sales, OEM Sales) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc., BorgWarner Inc., Cummins Inc., Mitsubishi Heavy Industries, Ltd., IHI Corporation, Garrett Motion Inc., Continental AG, Weifang Deli Turbocharger Co., Ltd., Accelleron Industries (ABB Turbocharging), MAN Energy Solutions, Wabtec Corporation, Caterpillar Inc., Rotomaster International, Turbo Energy Private Limited, Precision Turbo & Engine, Cummins Turbo Technologies (Holset), Schwitzer, Elgin Industries, Bosch Mahle Turbo Systems, Sonalika Group |
Frequently Asked Questions
Leading companies include Honeywell International Inc., BorgWarner Inc., Cummins Inc., Mitsubishi Heavy Industries, Ltd., and IHI Corporation, among other major turbocharger and engine component manufacturers.
Opportunities include hydrogen combustion engine expansion offering zero-tailpipe-emission alternatives and off-highway electrification-hybrid opportunities bridging conventional engine efficiency with electrified assist.
Growth is driven by stricter emission regulations, rising demand for energy efficiency, and the need for improved fuel efficiency in industrial diesel engines.
Diesel Engine dominates by engine type with approximately 52.60% share, Turbine dominates by component type with roughly 31.50% share, Wastegate/Fixed Geometry dominates by technology with about 61.50% share, and Marine dominates by application with approximately 34.60% share; Dual Fuel Engine, Actuators, Variable Geometry Turbocharger, and Power Generation are the fastest-growing segments within their respective categories.
North America is the largest regional market, led by the United States, while Asia Pacific, led by China, is the fastest-growing region through 2035.
