
Automotive DC-DC Converters Market Report Scope & Overview:
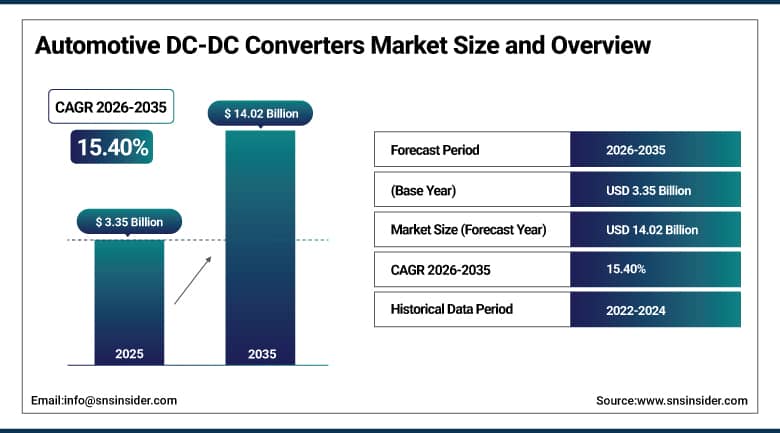
The Automotive DC-DC Converters Market was valued at USD 3.35 Billion in 2025 and is expected to reach USD 14.02 Billion by 2035, growing at a CAGR of 15.40% from 2026 to 2035.
The global Automotive DC-DC Converters Market is expanding rapidly owing to the increased usage of electric and hybrid cars around the world. The growing popularity of electric vehicles is resulting in a higher need for a system that can convert the power efficiently for varying voltages between batteries, motors, ECU, and other auxiliary systems of the vehicle. In addition, the increasing incorporation of various electronic devices such as advanced driver assistance systems and infotainment in the vehicles is further adding to the growing demand for power in the automobile industry. Automakers are focusing on power electronics that are light, compact, and energy-efficient.
Vicor introduced a new DCM family of regulated 48V-to-12V DC-DC converters for evolving EV architectures in March 2025, reflecting continued semiconductor and power module innovation as automotive manufacturers deploy high-efficiency converter systems to comply with evolving environmental regulations and improve energy management across next-generation vehicle platforms operating efficiently between minus 40 and plus 80 degrees Celsius while exceeding 90% energy efficiency.
To Get More Information On Automotive DC-DC Converters Market - Request Free Sample Report
Automotive DC-DC Converters Market Trends
-
Growing shift to 800V vehicle architectures continues doubling voltage from the traditional 400V standard to reduce current requirements and enable faster DC charging.
-
Rising integration of silicon carbide and gallium nitride semiconductor technologies continues improving converter efficiency, thermal performance, and power density.
-
Expanding development of converters optimized for 800V architectures and ultra-fast charging ecosystems continues reshaping competitive product strategies.
-
Increasing investment in AI-powered power management solutions continues to help offset massive power consumption from AI-driven autonomous driving systems.
-
Growing megafab-scale silicon carbide manufacturing capacity investment continues as leading semiconductor companies race to meet automotive-grade demand.
U.S. Automotive DC-DC Converters Market Outlook
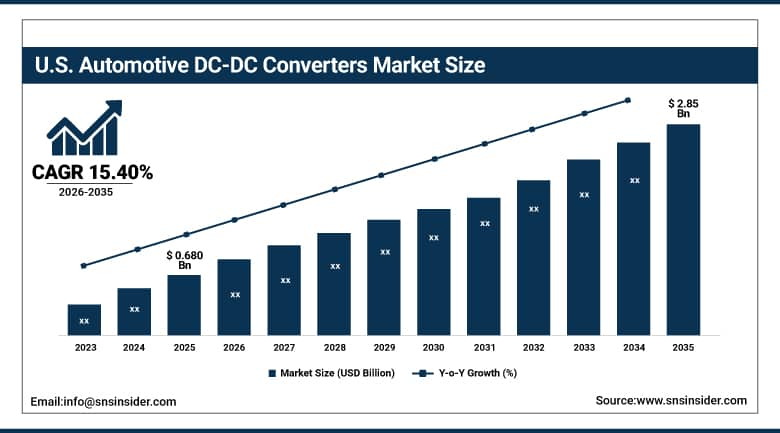
The U.S. Automotive DC-DC Converters Market was valued at USD 0.680 Billion in 2025 and is projected to reach USD 2.85 Billion by 2035, growing at a CAGR of 15.40% during 2026-2035.
Rising electric vehicle production and increasing complexity of vehicle electronics continue to support robust market growth across the United States. Leading semiconductor manufacturers continue to expand silicon carbide production capacity addressing rising demand for high-voltage, high-efficiency converter platforms. Growing deployment of 800V architectures across next-generation American electric vehicle platforms continues to reinforce sustained domestic market development nationwide.
Infineon inaugurated its "Kulim 3" facility in Malaysia as the world's largest 200mm silicon carbide power fab, with its CoolSiC technology currently being deployed in the high-stakes launch of the Rivian R2 platform, reflecting the strategic importance American electric vehicle manufacturers place on securing reliable, high-volume silicon carbide semiconductor supply as the industry scales toward mass-market 800V architecture adoption.
Automotive DC-DC Converters Market Segment Analysis
-
By Product Type, Isolated led the Automotive DC-DC Converters Market with a 58.20% share in 2025, while Bi-Directional is the fastest-growing product/topology type segment with a CAGR of 18.24% from 2026-2035.
-
By Propulsion Type, Battery Electric Vehicles (BEV) led the Automotive DC-DC Converters Market with a 66.50% share in 2025, while Fuel Cell Electric Vehicles (FCEV) is the fastest-growing propulsion type segment with a CAGR of 19.60% from 2026-2035.
-
By Input Voltage, 40-70V led the Automotive DC-DC Converters Market with a 56.43% share in 2025, while Above 70V is the fastest-growing input voltage segment with a CAGR of 18.27% from 2026-2035.
-
By Vehicle Type, Commercial Vehicles led the Automotive DC-DC Converters Market with a 67.30% share in 2025, while Passenger Vehicles is the fastest-growing vehicle type segment with a CAGR of 16.80% from 2026-2035.
By Product Type, Isolated Dominated the Market While Bi-Directional Is the Fastest-Growing Segment
The Isolated segment led the Automotive DC-DC Converters Market with a revenue share of 58.20% in 2025, due to the adoption of isolated architectures such as flyback, forward, full bridge, half bridge, and push pull that offer better safety attributes essential for high voltage automotive applications. The isolated converters continue to offer the required electrical isolation between the high voltage traction battery systems and low voltage vehicle electronics, thus maintaining this architectural dominance in the overall automotive DC-DC converters market.
The Bi-Directional segment is projected to register the fastest CAGR of 18.24% during the forecast period 2026-2035, due to increasing demand for 48V/12V bi-directional systems that can handle both the traction and auxiliary power flow in mild hybrid and electric vehicles. Increasing regulations mandating the need for 48V mild hybrid systems in internal combustion engines have been instrumental in this segment's above average growth compared to isolated architectures.
By Propulsion Type, Battery Electric Vehicles Dominated the Market While Fuel Cell Electric Vehicles Is the Fastest-Growing Segment
The Battery Electric Vehicles (BEV) segment led the Automotive DC-DC Converters Market with a revenue share of 66.50% in 2025, owing to rising production of BEVs with more than one DC-DC converters to regulate power flows in traction battery, auxiliary, and charging. The propulsion system of BEVs still holds the status of the largest and fastest-growing category of electrified vehicles across the globe which is responsible for maintaining its leadership status within the automotive DC-DC converter market.
The Fuel Cell Electric Vehicles (FCEV) segment is expected to register the fastest CAGR of 19.60% during the forecast period 2026-2035, owing to rising investments of governments in the commercial vehicles projects using hydrogen fuel cell technology, thereby necessitating power conversion between fuel cell stacks and vehicle's electric systems. Increasing usage of fuel cell technology in heavy duty and long haul commercial vehicles has been responsible for maintaining above average growth of this segment compared to conventional propulsion systems like BEV and hybrids.
By Input Voltage, 40-70V Dominated the Market While Above 70V Is the Fastest-Growing Segment
The 40-70V segment led the Automotive DC-DC Converters Market with a revenue share of 56.43% in 2025, owing to the compatibility of this voltage range with the prevalence of the 48V mild-hybrid system on board the electrified and conventionally powered ICE vehicles. Input voltage range of 40-70V remains the principal link between the existing 12V electrical system and the evolving high-voltage traction batteries, contributing to its leadership among other segments of the global automotive DC-DC converters market.
The Above 70V segment is expected to register the fastest CAGR of 18.27% during the forecast period 2026-2035, owing to the increasing demand for the DC-DC converters catering to above-70 volts traction batteries used in 400V and 800V architectures featuring ultra fast charging ability. Continuous transition to 800V vehicle platform and increasing adoption of silicon carbide & gallium nitride semiconductors keep reinforcing the above average growth path of this category.
By Vehicle Type, Commercial Vehicles Dominated the Market While Passenger Vehicles Is the Fastest-Growing Segment
The Commercial Vehicles segment led the Automotive DC-DC Converters Market with a revenue share of 67.30% in 2025, reflecting commercial fleet electrification requiring reliable multi-voltage power management systems capable of supporting demanding duty cycles and thermal profiles. Commercial vehicles continue to represent significant DC-DC converter demand given their electrical architecture complexity, sustaining this vehicle type's dominant position across the broader automotive DC-DC converter market worldwide.
The Passenger Vehicles segment is expected to register the fastest CAGR of 16.80% during the forecast period 2026-2035, driven by mass-market electric vehicle adoption requiring increasingly sophisticated power conversion systems supporting infotainment, ADAS, and battery management functions. Growing consumer EV adoption across major automotive markets continues to reinforce this segment's above-average growth trajectory relative to the more established commercial vehicle category.
Regional Insights
|
Region |
Country |
Share (2025) |
|---|---|---|
|
Europe |
Germany |
26.80% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
38.60% |
|
Middle East & Africa |
UAE |
18.60% |
|
Latin America |
Brazil |
22.60% |
Europe Automotive DC-DC Converters Market Insights
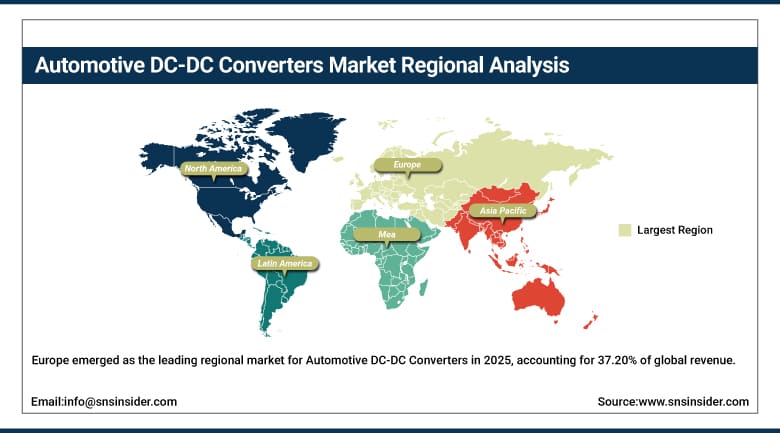
Europe emerged as the leading regional market for Automotive DC-DC Converters in 2025, accounting for 37.20% of global revenue. The region’s leadership is supported by stringent emission regulations and vehicle electrification mandates accelerating the adoption of 48V and higher-voltage architectures. Government investment in clean mobility infrastructure is further supporting electrification. Additionally, strong automotive manufacturing capabilities and continued innovation by Tier-1 suppliers are driving advancements in converter efficiency, safety, reliability, and performance across European markets.
Germany led the European market with a 26.80% regional share in 2025, supported by its concentration of leading automotive OEMs and Tier-1 suppliers including Bosch, Continental, and Infineon. France, Italy, and the United Kingdom are also contributing meaningfully to regional growth, supported by strong government incentives promoting electric vehicle adoption across major European markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive DC-DC Converters Market Insights
North America represented a significant share of the global Automotive DC-DC Converters Market in 2025, due to increased production of electric vehicles as well as vehicle electrification. The increased incorporation of sophisticated electronic systems is also boosting the need for power conversion technologies in the region. The development of facilities for producing silicon carbide is adding impetus to the power electronics industry in the region. Furthermore, innovations, developments in EV infrastructure, and attention towards energy-efficient automotive components are adding value to North America in the global automotive DC-DC converter market.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its concentration of leading electric vehicle manufacturers and growing domestic semiconductor manufacturing investment. Canada and Mexico are also contributing to regional growth through steady automotive electronics manufacturing and growing electric vehicle adoption across North American automotive supply chains.
Asia Pacific Automotive DC-DC Converters Market Insights
Asia Pacific is projected to register the fastest growth in the Automotive DC-DC Converters Market during the forecast period, driven by rapidly expanding electric vehicle production, particularly in China. Increasing domestic manufacturing capacity for silicon carbide semiconductors is supporting the development of advanced power electronics. Government-backed electrification initiatives, expanding EV infrastructure, and growing investments in automotive technologies are further accelerating regional adoption. Rising vehicle electrification and increasing demand for efficient power conversion systems are expected to maintain Asia Pacific’s above-average growth trajectory compared with mature Western markets.
China accounted for approximately 38.60% of the Asia Pacific market in 2025, supported by its position as the world's largest electric vehicle production hub and rapidly expanding domestic power semiconductor manufacturing capacity. Japan, South Korea, and India are also contributing meaningfully to regional growth, with Japan sustaining strong demand given its leading automotive electronics supplier base.
Middle East & Africa and Latin America Automotive DC-DC Converters Market Insights
The Middle East & Africa region is exhibiting steady growth as automotive manufacturing diversification and electric vehicle infrastructure investment continue expanding across the Gulf states. Latin America is similarly benefiting from expanding automotive manufacturing capacity and growing consumer interest in electric and hybrid vehicle adoption across major regional economies.
The UAE led the Middle East & Africa market with a 18.60% regional share in 2025, supported by growing automotive manufacturing diversification and electric vehicle infrastructure investment. Brazil represented 22.60% of the Latin American market in 2025, driven by expanding automotive manufacturing capacity, with Mexico also contributing to regional growth through growing electric vehicle component manufacturing investment.
Growth Drivers: EV Electrification Acceleration and 800V Architecture Adoption Driving Market Growth
The Automotive DC-DC Converters Market is being driven primarily by accelerating electric vehicle production, rising deployment of 400V and 800V vehicle architectures, and increasing demand for highly efficient onboard power management systems capable of supporting next-generation electrified vehicles. Automotive DC-DC converters continue rapidly evolving from auxiliary electronic components into mission-critical power management systems that enable seamless energy transfer between high-voltage traction batteries and low-voltage vehicle electronics.
Growing shift to 800V vehicle architectures continues doubling voltage from the traditional 400V standard to reduce current requirements and enable faster DC charging. Rising integration of silicon carbide and gallium nitride semiconductor technologies continues improving converter efficiency, thermal performance, and power density. Expanding development of converters optimized for ultra-fast charging ecosystems continues reshaping competitive product strategies, reinforcing sustained industry investment.
Restraints: Semiconductor Supply Constraints and High Development Costs Limiting Market Expansion
Despite favorable underlying demand, the market faces meaningful restraints related to silicon carbide and gallium nitride semiconductor supply constraints, as leading manufacturers race to scale megafab-level production capacity to meet surging automotive-grade demand. Substantial capital investment required for advanced power semiconductor manufacturing facilities continues to limit market entry to well-capitalized companies possessing vertical integration capability.
Complex thermal management and reliability engineering requirements for high-voltage, high-power-density converters continue to extend product development and qualification timelines for automotive-grade components. Growing competitive intensity among an expanding roster of Tier-1 suppliers and semiconductor manufacturers also continues to compress margins across mainstream converter categories, particularly amid intense competition for OEM design wins.
Opportunities: AI-Powered Power Management and Fuel Cell Vehicle Expansion Creating New Growth Avenues
Substantial opportunity exists in continued development of AI-powered power management solutions capable of offsetting massive power consumption from AI-driven autonomous driving systems while optimizing overall vehicle energy efficiency. Companies that successfully commercialize software-defined, intelligently managed converter platforms stand to capture significant share of category growth as vehicles increasingly integrate sophisticated onboard computing capability.
Growing fuel cell vehicle adoption across heavy-duty and commercial applications presents a further significant growth avenue, as government investment in hydrogen mobility ecosystems continues expanding. Expanding silicon carbide megafab manufacturing capacity across emerging markets in Asia Pacific also represents meaningful untapped opportunity for automotive DC-DC converter manufacturers seeking supply chain diversification.
Recent Developments:
-
2024: STMicroelectronics unveiled a new generation of silicon carbide power technology in 750V and 1200V classes for next-generation EV traction inverters, having supplied SiC devices for more than 5 million passenger cars worldwide.
-
2026: Infineon inaugurated its 'Kulim 3' facility in Malaysia as the world's largest 200mm silicon carbide power fab, deploying CoolSiC technology across the Rivian R2 platform and Xiaomi's EV lineup expansion.
-
2026: Infineon opened the world's largest fab for power semiconductors and analog/mixed-signal technologies in Dresden, Germany.
-
2026: The global shift to 800V vehicle architectures accelerated, with automakers doubling voltage from the traditional 400V standard to enable faster DC charging with thinner, lighter wiring.
Automotive DC-DC Converters Companies are:
-
Robert Bosch GmbH
-
Denso Corporation
-
Valeo
-
Continental AG
-
BorgWarner Inc.
-
Toyota Industries Corporation
-
Hyundai Mobis
-
Vicor Corporation
-
Delta Electronics, Inc.
-
TDK Corporation
-
Panasonic Corporation
-
ZF Friedrichshafen AG
-
Marelli Holdings Co., Ltd.
-
LG Innotek Co., Ltd.
-
STMicroelectronics N.V.
-
Texas Instruments Incorporated
-
Eaton Corporation plc
-
HELLA GmbH & Co. KGaA
Automotive DC-DC Converters Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.35 Billion |
| Market Size by 2035 | USD 14.02 Billion |
| CAGR | CAGR of 15.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Isolated, Non-Isolated/Bi-Directional) • By Propulsion Type (BEV, HEV, PHEV, FCEV) • By Input Voltage (Below 12V, 12-24V, 24-48V, 40-70V, Above 70V) • By Vehicle Type (Passenger Vehicles, Commercial Vehicles, Two-Wheelers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Denso Corporation, Valeo, Continental AG, BorgWarner Inc., Infineon Technologies AG, Toyota Industries Corporation, Hyundai Mobis, Vicor Corporation, Delta Electronics, Inc., TDK Corporation, Panasonic Corporation, ZF Friedrichshafen AG, Marelli Holdings Co., Ltd., Aptiv PLC, LG Innotek Co., Ltd., STMicroelectronics N.V., Texas Instruments Incorporated, Eaton Corporation plc, HELLA GmbH & Co. KGaA. |
Frequently Asked Questions
The Automotive DC-DC Converters Market is expected to grow at a CAGR of 15.40% from 2026 to 2035.
The Automotive DC-DC Converters Market was valued at USD 3.35 Billion in 2025.
The market is driven by accelerating electric vehicle production, rising deployment of 400V and 800V vehicle architectures, and increasing demand for highly efficient onboard power management systems.
The Isolated segment dominated the Automotive DC-DC Converters Market in 2025, accounting for approximately 58.20% market share.
The Europe region dominated the Automotive DC-DC Converters Market in 2025, accounting for approximately 37.20% market share.
