
Industrial Starch Market Report Scope & Overview:
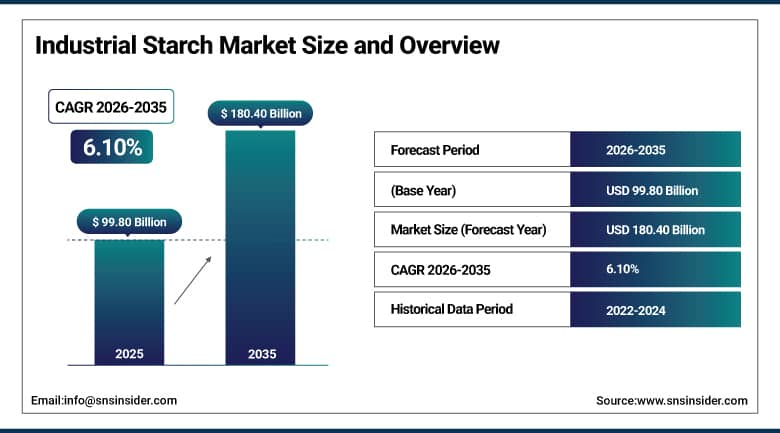
The Industrial Starch Market was valued at USD 99.80 Billion in 2025 and is expected to reach USD 180.40 Billion by 2035, growing at a CAGR of 6.10% from 2026 to 2035.
The Industrial Starch Market has been seeing considerable growth due to the increasing consumption of industrial starch by the food & beverages processing industry because of its properties as a thickening, gelling, stabilizing, and binding agent in various types of packaged and convenience foods. The growing consumption of starch derivatives and sweeteners by the confectionery, bakery, and dairy industry, coupled with growing consumption by the pharmaceuticals & biotechnology sector, has expanded the usage of starch derivatives to various industries. The increased popularity of biodegradable and bio-based products has also boosted its demand in bioplastic, paper, and packaging applications as an alternative to petroleum-based products.
In June 2026, Ingredion Incorporated announced a recommended all-cash acquisition of Tate & Lyle PLC for an enterprise value of approximately USD 5.0 Billion, combining Ingredion’s texture and sugar reduction capabilities with Tate & Lyle’s mouthfeel, sweetening, and fortification portfolio, reflecting continued large-scale consolidation across the global starch and specialty ingredients industry.
Market Size and Forecast
- Market Size in 2026E: USD 105.90 Billion
- Market Size by 2035: USD 180.40 Billion
- CAGR: 6.10% from 2026 to 2035
- Fastest Growing Region: Asia Pacific
- Largest Region: North America
To Get More Information On Industrial Starch Market - Request Free Sample Report
Industrial Starch Market Trends
- Growing adoption of cassava-based starch is expanding rapidly, supported by its non-GMO positioning and alignment with clean-label regulatory requirements in Europe.
- Rising demand for native starch in clean-label bakery and dairy formulations is transitioning the category toward more nuanced, premium-oriented product positioning.
- Expanding use of industrial starch in biodegradable plastics and packaging materials continues to shape new product development priorities across the industry.
- Increasing consolidation among leading ingredient manufacturers, including large-scale mergers and acquisitions, is reshaping competitive dynamics across the sector.
- Growing investment in wastewater treatment and production process technology is broadening sustainability positioning beyond traditional processing methods.
U.S. Industrial Starch Market Outlook
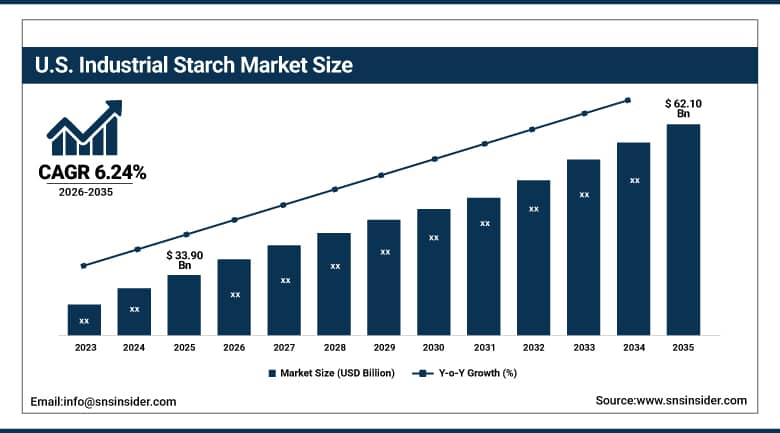
The U.S. Industrial Starch Market was valued at USD 33.90 Billion in 2025 and is projected to reach USD 62.10 Billion by 2035, growing at a CAGR of 6.24% during 2026-2035.
The U.S. Industrial Starch Market is growing steadily, due to the country’s position as the largest global corn producer and exporter, supporting abundant raw material availability and a well-established processing infrastructure. The increased adoption of processed, packaged, and convenience food products is contributing to the growth of consumption. Corn-derived starch and starch derivatives are gaining popularity among food processors, pharmaceutical manufacturers, and paper industry participants. Innovations such as functional native starches and clean-label texturizers are driving consumer and manufacturer choice options. Robust distribution networks through direct industrial supply agreements and specialty ingredient distributors are increasing product availability. Furthermore, increasing investments by ingredient producers and shifting demand toward biodegradable materials are opening up new growth avenues.
In early 2025, Ingredion announced plans to invest USD 100 Million into the development of its texture and healthful solutions facility in Indianapolis, Indiana, reflecting continued capital investment by leading producers in expanding domestic starch-based ingredient manufacturing capacity.
Industrial Starch Market Segment Analysis
- By Source, Corn segment dominated the Industrial Starch Market in 2025 with around 70% share; Cassava segment is the fastest-growing segment.
- By Product Type, Native Starch segment dominated the market in 2025 with around 52% share; Starch Derivatives & Sweeteners segment is the fastest-growing segment.
- By Application, Food & Beverage segment dominated the market in 2025 with around 56% share; Pharmaceuticals segment is the fastest-growing segment.
- By Function, Thickening segment dominated the market in 2025; Binders & Excipients segment is the fastest-growing segment.
By Source, Corn Dominates the Industrial Starch Market While Cassava Registers the Fastest Growth
Corn Starch leads the way in Industrial Starch Market because of its abundance, availability of infrastructure for processing and higher starch content enabling industrial extraction and processing on an extensive scale. Corn starch enjoys an organized supply chain, especially in the U.S., thereby ensuring sufficient volumes of raw material at favorable costs to manufacturers. Ease of handling in high throughput systems ensures suitability for applications in food, paper, and industry sectors. Familiarity among consumers, scalability of sourcing along with manufacturing infrastructure ensure that corn starch maintains the lead among sources of raw materials.
Cassava has seen tremendous growth due to growing demand from manufacturers for non-GMO and allergen-free sources of starch. This is especially true for products meant for European market where clean-label and regulated label are becoming increasingly important. Starch derived from cassava finds great favor among food manufacturers looking for naturally sourced and minimal process ingredients for bakery, dairy and confectionery applications.
By Product Type, Native Starch Dominates the Industrial Starch Market While Starch Derivatives & Sweeteners Emerge as the Fastest-Growing Type
Native Starch leads in the Industrial Starch Market because of its versatile application, cost-effectiveness, and functionality that does not require any further chemical modifications in food, paper, and industrial applications. Native Starch is extensively used as a thickening, stabilizing, and binding agent in bakery products, dairy products, and processed foods. The rising demand for clean-label ingredients is further adding to the preference for native and minimally processed starches, leading to the segment's market dominance.
The segment of Starch Derivatives & Sweeteners is witnessing rapid growth owing to the rising use of starch derivatives and sweeteners in confectionery, beverages, and processed food products that need particular functionalities like improved sweetness, viscosity regulation, or shelf-life. The rising demand for sugar-free and specialized sweeteners in the food and beverages industry is making food & beverage manufacturers opt for modified starch-based products. The development in starch modification technology and enzymatic modification technology has created many opportunities in this segment.
By Application, Food & Beverage Dominates the Industrial Starch Market While Pharmaceuticals Experiences the Fastest Growth
Food & Beverage dominates the Industrial Starch Market due to the increasing trend of processed, packaged, and convenience food consumption that relies on starch as a thickening, stabilizing, gelling, and binding agent. Various bakery, dairy, confectionery, and sauce products incorporate starch and its derivatives across home, foodservice, and industrial processing settings. The growing popularity of convenience foods, increasing demand for texture and shelf-life enhancement, and rising product innovation are driving consumption. Widespread manufacturing availability and an expanding range of processed food launches are further fueling demand in this application space.
Pharmaceuticals is growing rapidly on account of increasing usage of starch as a binder, diluent, disintegrant, and excipient in tablet and capsule formulations. Increasing demand for biodegradable and pharmaceutical-grade excipients is compelling drug manufacturers to adopt starch-based ingredients over synthetic alternatives. Advances in excipient functionality and formulation technology are opening up several opportunities for commercial utilization in this segment.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.10% |
|
Asia Pacific |
China |
36.80% |
|
Europe |
Germany |
24.30% |
|
Middle East & Africa |
UAE |
17.60% |
|
Latin America |
Brazil |
24.20% |
North America Industrial Starch Market Insights
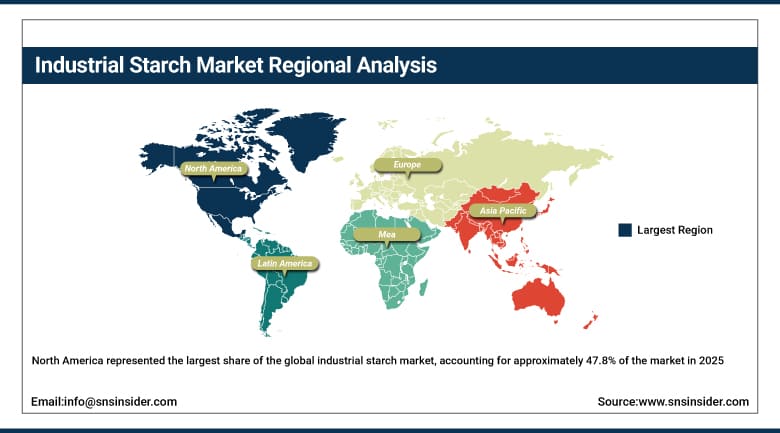
North America represented the largest share of the global industrial starch market, accounting for approximately 47.8% of the market in 2025, supported by robust demand from the food and beverage sector, a well-established corn processing industry, and growing applications in biodegradable plastics and pharmaceuticals. Increasing consumption of processed and packaged food products is reinforcing demand for starch-based functional ingredients. Growing consumer interest in clean-label and biodegradable materials is encouraging manufacturers to expand native and specialty starch product lines. Well-established corn cultivation, processing infrastructure, and distribution networks across the United States and Canada are also improving product accessibility and sustaining regional market development.
The United States accounted for approximately 85.10% of the North American market in 2025, reflecting its position as the largest global corn producer and exporter along with extensive food and industrial processing infrastructure. Canada and Mexico are contributing to regional growth through steady demand for processed food and expanding paper and packaging applications.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Industrial Starch Market Insights
Europe was one of the major regions that held considerable market share in the Industrial Starch Market in 2025. This was attributed to the presence of stringent regulations pertaining to clean-label and non-GMO starches in addition to the availability of infrastructure that deals with the processing of wheat and potato starches. Growing demand for cassava and non-GMO starch sources in countries like Germany, France, and Netherlands is encouraging innovation in the market.
Germany had the largest regional share at 24.30% in 2025 owing to the presence of food and industrial processing infrastructure and growing biodegradable materials industry in the region. The other two major contributors in the region include United Kingdom and France, which have growing demand for clean-label food ingredients.
Asia Pacific Industrial Starch Market Insights
Asia Pacific is expected to register the fastest CAGR in the Industrial Starch Market during 2026–2035, driven by rapid growth in food processing, packaging, and pharmaceutical manufacturing across the region’s large population base. China and India are witnessing particularly strong growth as expanding processed food consumption and industrial manufacturing capacity increase demand for corn and cassava-based starch. Rising product innovation and growing consumer awareness regarding biodegradable materials are further supporting market expansion. Rising demand for pharmaceutical excipients and clean-label food ingredients is also reinforcing Asia Pacific’s above-average growth trajectory compared with more mature markets.
China accounted for approximately 36.80% of the Asia Pacific market in 2025, supported by its large-scale corn processing base and expanding food and pharmaceutical manufacturing sectors. Japan, India, and South Korea are also contributing meaningfully to regional growth, with India benefiting from rapidly expanding processed food consumption and industrial manufacturing capacity.
Middle East & Africa and Latin America Industrial Starch Market Insights
The Middle East & Africa market has been experiencing continuous growth due to increased food processing infrastructural development in the Gulf countries, fueled by increasing modern retail and packaged food demand. The same case has been witnessed in Latin America because of the expansion in cassava planting and consumer demand for processed foods and bio-degradable food packages.
The UAE emerged as the top country in the Middle East & Africa market with a 17.60% regional share in 2025, owing to increasing food processing infrastructures and modern retail expansion. Brazil contributed 24.20% to the total Latin American market in 2025, owing to expansion in cassava based starch production and processed food consumption, alongside Argentina which contributes to regional growth through increasing corn-based industrial starch.
Market Dynamics
Growth Drivers: Processed Food Demand and Biodegradable Materials Adoption Driving Market Growth
The main factors influencing the growth of the Industrial Starch Market include increasing demand for processed and convenience food products, rising use of starch as a thickening, stabilizing, and gelling agent, and growing adoption of biodegradable materials as substitutes for synthetic plastics. As starch is increasingly recognized as a versatile, cost-effective, and sustainable functional ingredient, food, pharmaceutical, and packaging manufacturers are increasingly realizing its benefits, contributing to growth in the global market for this ingredient category.
Growing adoption of starch derivatives and sweeteners in confectionery, bakery, and beverage applications continues to expand as manufacturers seek reduced-sugar and specialty functional solutions. Increasing innovation in production process and wastewater treatment technology is influencing new efficiency and sustainability trends across the overall industrial starch market.
Restraints: Raw Material Price Volatility and Regulatory Compliance Challenges Limiting Market Expansion
Although there are positive aspects related to demand, the segment will be constrained due to challenges posed by the cost variability of raw materials and the complex regulatory environment in different regions. The cost and availability of raw materials such as corn, cassava, wheat, and potatoes can be affected by weather conditions, productivity, and shifts in farming priorities, thus affecting the cost structure of the production process of the manufacturers. There are still regulatory differences in different regions concerning the labeling of food ingredients, GM crops, and pharmaceutical excipients, which affects market entry times and necessitates compliance investment from manufacturers.
Higher research and development costs associated with technology and the development of specialty products will affect production costs, making it difficult for smaller companies to compete on prices. Moreover, there will be increased pricing pressures as a result of competition among suppliers, both the existing ones and those from different regions. As the category matures, manufacturers will have to strike a balance between price, functionality, and regulation.
Opportunities: Bioplastics Expansion and Pharmaceutical Excipient Innovation Creating New Growth Avenues
A number of opportunities lie in the production of bioplastics, creation of new pharmaceutical excipients, and usage of starch in paper and packaging industries. The development of starch-based bioplastic technologies can be a solution to meet increasing demand for bio-degradable substitutes for plastic packaging made from petroleum. Producers can take advantage of growing interest to customized starch for pharmaceuticals that includes specialty binders, disintegrators and drug delivery excipients. Growing demand for starch in the paper and corrugating industry as a binder and coating agent also offers producers a way to increase visibility and consumption frequency.
Development of sources of non-GMO cassava, wheat, potato starch can provide producers with new applications that will attract customers and producers who care about sustainability. Improvements in enzymatic processing can give producers an opportunity to remain competitive in price while maintaining functional qualities. Clean label and advances in production technology as well as accessibility of biodegradable packaging can also help producers to differentiate themselves.
Recent Developments:
- 2026: Sanstar Limited commissioned expanded native starch manufacturing capacity at its Dhule facility in Maharashtra, increasing total installed capacity from 1,100 TPD to 2,350 TPD.
- 2026: SMS Corporation held a groundbreaking ceremony for a new tapioca starch production facility aimed at expanding manufacturing and innovation capabilities for food and non-food starch applications, including pharmaceuticals, paper, adhesives, and sustainable biomaterials.
- 2025: Ingredion Incorporated introduced NOVATION Indulge 2940, described as the first non-GMO functional native corn starch, expanding its clean-label texturizer portfolio for dairy and alternative dairy applications.
Industrial Starch Market key players are:
- Cargill, Incorporated
- Archer Daniels Midland Company (ADM)
- Ingredion Incorporated
- Tate & Lyle PLC
- AGRANA Beteiligungs-AG
- Grain Processing Corporation
- Roquette Frères
- Tereos Group
- Royal Cosun
- Coöperatie Koninklijke Avebe U.A.
- Emsland Group
- Global Bio-Chem Technology Group Company Limited
- Manildra Group
- Universal Starch-Chem Allied Ltd.
- Gulshan Polyols Limited
- Sanstar Limited
- Japan Corn Starch Co., Ltd.
- Angel Starch and Food Pvt. Ltd.
- PT Budi Starch & Sweetener Tbk
- Siam Modified Starch Co., Ltd.
Industrial Starch Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 99.80 Billion |
| Market Size by 2035 | USD 180.40 Billion |
| CAGR | CAGR of 6.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source (Corn, Cassava, Wheat, Potato, and Others) • By Product Type (Native Starch, and Starch Derivatives & Sweeteners) • By Application (Food & Beverage, Pharmaceuticals, Paper & Corrugating, Animal Feed, and Others) • By Function (Thickening, Stabilizing & Gelling Agents, and Binders & Excipients) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cargill, Incorporated; Archer Daniels Midland Company (ADM); Ingredion Incorporated; Tate & Lyle PLC; AGRANA Beteiligungs-AG; Grain Processing Corporation; Roquette Frères; Tereos Group; Royal Cosun; Coöperatie Koninklijke Avebe U.A.; Emsland Group; Global Bio-Chem Technology Group Company Limited; Manildra Group; Universal Starch-Chem Allied Ltd.; Gulshan Polyols Limited; Sanstar Limited; Japan Corn Starch Co., Ltd.; Angel Starch and Food Pvt. Ltd.; PT Budi Starch & Sweetener Tbk; Siam Modified Starch Co., Ltd. |
Frequently Asked Questions
Bioplastics Expansion and Pharmaceutical Excipient Innovation Creating New Growth Avenues
Some of the major companies that operate in the global industrial starch market are Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Grain Processing Corporation, AGRANA Beteiligungs-AG, Emsland Group.
The market is driven by growing demand for processed and convenience food products, rising use of starch as a functional processing agent, and increasing adoption of biodegradable materials.
The Corn segment dominated the Industrial Starch Market in 2025.
The North America region dominated the Industrial Starch Market in 2025, accounting for approximately 40% of global market share.
