
Kidney Stone Management Market Report Scope & Overview:
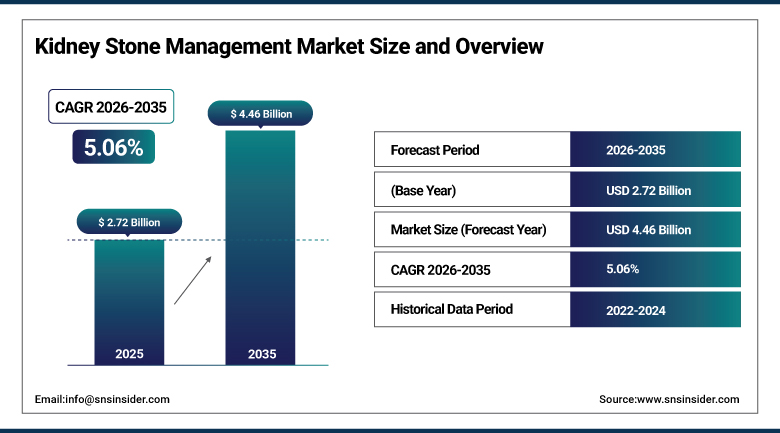
The Kidney Stone Management Market was valued at USD 2.72 Billion in 2025 and is expected to reach USD 4.46 Billion by 2035, growing at a CAGR of 5.06% from 2026-2035.
The kidney stone management market includes the equipment used for diagnosis, fragmentation, and removal of urinary stones. This includes extracorporeal shock wave lithotripsy, ureteroscopy and laser fragmentation of stones, percutaneous nephrolithotomy for large stones, and the imaging devices that diagnose and track them. Over 10 percent of all adults will have a kidney stone at some point in their lives, and 50 percent of patients have another one after five years, ensuring a consistent need for treatment equipment and imaging devices. Market growth will be driven by increased incidence due to lifestyle factors such as diet and obesity as well as climate-related changes, ongoing replacement of open surgical treatments with minimally invasive methods such as ureteroscopy and lasers, and innovations in disposable scopes, pressure measurement, and laser fibres. The hospital setting will continue to dominate, but minimally invasive procedures will be done more outside of hospitals.
In 2025, Boston Scientific reported that it received CE mark approval for the MOSES Raydar Holmium Laser System, designed to increase ablation efficiency by maintaining an effective proximity range between the laser fibre tip and the kidney stone during lithotripsy procedures.
To Get more information Kidney Stone Management Market - Request Free Sample Report
Kidney Stone Management Market Trends
-
Rising adoption of single-use flexible ureteroscopes reducing reprocessing burden and infection risk.
-
Growing use of real-time intrarenal pressure monitoring during ureteroscopy to improve patient safety.
-
Expanding availability of thulium-fibre and next-generation holmium laser lithotripsy systems.
-
Increasing migration of uncomplicated stone procedures toward ambulatory surgical centers.
-
Rising incidence of uric acid stones linked to obesity and metabolic syndrome.
-
Growing integration of digital visualisation and pressure data into comprehensive stone management platforms.
U.S. Kidney Stone Management Market Overview
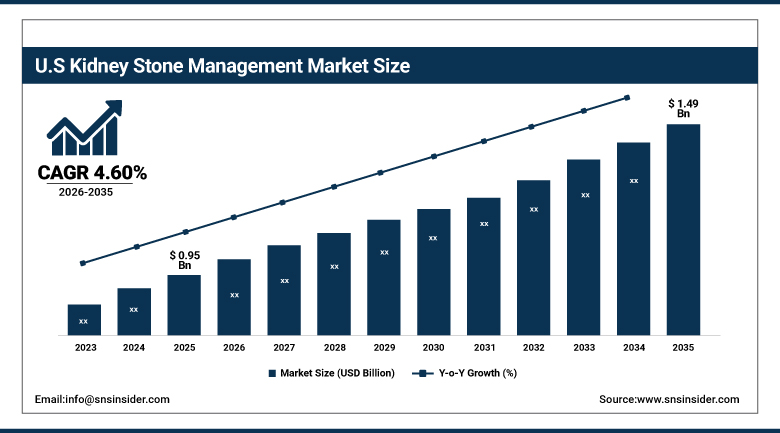
The U.S. Kidney Stone Management Market was valued at USD 0.95 Billion in 2025 and is expected to reach USD 1.49 Billion by 2035, growing at a CAGR of 4.60% from 2026-2035.
The U.S. Kidney Stone Management Market benefits from a large and ageing population with rising rates of obesity and metabolic disease, both of which are established risk factors for stone formation, alongside broad insurance coverage and rapid adoption of minimally invasive treatment technology. Urology practices and hospital systems across the country continue to replace older, reusable ureteroscopes with single-use devices to reduce infection risk and reprocessing cost, and leading device makers continue to expand laser fibre and fluid management portfolios to support increasingly complex procedures. Ambulatory surgical centers are taking on a growing share of uncomplicated cases as reimbursement extends to the outpatient setting, while hospitals retain the more complex percutaneous procedures. Continued clinical research into stone prevention and recurrence management is expected to support steady, incremental innovation across the product portfolio.
In 2026, Boston Scientific received U.S. Food and Drug Administration clearance for its Asurys Fluid Management System, a single irrigation management platform designed for ureteroscopy, cystoscopy, percutaneous nephrolithotomy, and benign prostatic hyperplasia procedures.
Kidney Stone Management Market Segment Analysis
-
By Category, the Treatment segment dominated the market with a 58.60% share in 2025, while the Diagnostics segment is the fastest growing with a CAGR of 6.20% during 2026-2035.
-
By Treatment Procedure, the Extracorporeal Shock Wave Lithotripsy segment dominated the market with a 42.60% share in 2025, while the Laser Lithotripsy segment is the fastest growing with a CAGR of 7.20% during 2026-2035.
-
By Stone Type, the Calcium segment dominated the market with a 68.60% share in 2025, while the Uric Acid segment is the fastest growing with a CAGR of 6.60% during 2026-2035.
-
By End User, the Hospitals segment dominated the market with a 54.60% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of 6.80% during 2026-2035.
By Category, Treatment Dominates the Market and Diagnostics Grows Fastest
Treatment segment dominated the Kidney Stone Management market in 2025. Lithotripsy systems, ureteroscopes, laser fibres, stents, and retrieval baskets together account for the bulk of spending, reflecting the direct cost of the devices and disposables consumed during stone removal procedures. The recurring nature of kidney stone disease, with many patients requiring repeat intervention over their lifetime, continues to sustain steady treatment device demand.
Diagnostics is projected to be the fastest-growing category over the forecast period. Imaging technologies including computed tomography, ultrasound, and abdominal X-ray are essential to confirming stone presence, size, and location before choosing a treatment approach, and growing emphasis on early detection and recurrence monitoring continues to expand diagnostic imaging volumes alongside treatment procedures.
By Treatment Procedure, Extracorporeal Shock Wave Lithotripsy Dominates the Market and Laser Lithotripsy Grows Fastest
Extracorporeal shock wave lithotripsy dominated the market in 2025. This non-invasive technique fragments stones using externally applied shock waves without the need for incisions or scope insertion, making it a well-established first-line option for moderate-sized stones across both hospital and outpatient settings. Its high success rate and lack of anaesthesia requirements in many cases continue to support broad, sustained use.
Laser lithotripsy is expected to be the fastest-growing treatment procedure over the forecast period. Holmium and increasingly thulium-fibre laser systems, paired with flexible ureteroscopes, allow precise fragmentation of stones located throughout the urinary tract with strong safety and efficacy outcomes. Continued innovation in laser fibre design and ablation efficiency is expanding the range of stones that can be treated this way, driving above-market growth for this procedure.
By Stone Type, Calcium Dominates the Market and Uric Acid Grows Fastest
Calcium stones dominated the market in 2025. Calcium oxalate and calcium phosphate stones account for the large majority of all kidney stones diagnosed worldwide, reflecting common dietary and metabolic risk factors, and this sustained prevalence keeps calcium stone management at the centre of device and procedure demand.
Uric acid stones are projected to be the fastest-growing stone type over the forecast period. Rising global rates of obesity, metabolic syndrome, and type 2 diabetes are increasing the incidence of uric acid stone formation, and because these stones can sometimes be dissolved with medical therapy as well as fragmented surgically, growing case volumes are expanding demand across both treatment and diagnostic monitoring.
By End User, Hospitals Dominates the Market and Ambulatory Surgical Centers Grows Fastest
Hospitals dominated the market in 2025. They perform the full range of stone procedures, including complex percutaneous nephrolithotomy cases and emergency interventions for obstructing stones, and they maintain the imaging, anaesthesia, and post-procedure support required for higher-acuity patients. This breadth of capability keeps hospitals as the leading end-user setting.
Ambulatory surgical centers are expected to be the fastest-growing end-user category over the forecast period. Uncomplicated ureteroscopy and shock wave lithotripsy procedures are well suited to outpatient delivery, and payers increasingly favour the lower cost base these facilities offer relative to hospital admission. Expanding reimbursement for outpatient stone procedures continues to accelerate this shift.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
90.60% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Kidney Stone Management Market Insights
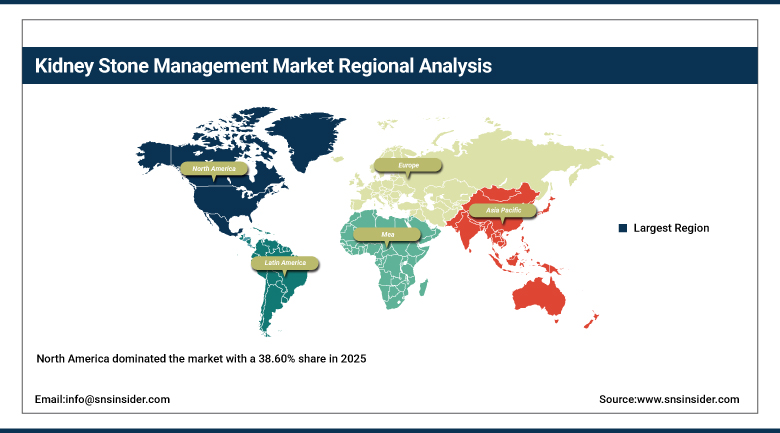
North America dominated the market with a 38.60% share in 2025. High kidney stone prevalence linked to diet and climate, broad insurance coverage, and rapid adoption of minimally invasive treatment technology underpin the region's leading position. The presence of leading device manufacturers headquartered within the region further reinforces sustained investment in next-generation laser, imaging, and fluid management systems.
Canada contributes steady incremental demand as its own urology infrastructure continues to expand access to minimally invasive stone treatment. Continued adoption of single-use ureteroscopes and advanced laser lithotripsy systems is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Kidney Stone Management Market Insights
Europe holds a significant share of the global market, supported by well-developed public health systems and a long tradition of urological research and clinical guideline development. Germany anchors regional demand through its large hospital sector and strong domestic medical device manufacturing base.
The United Kingdom, France, and Italy add consistent demand as national health systems continue to extend access to minimally invasive stone procedures. Continued clinical evidence generation across European centres supports ongoing refinement of treatment guidelines and sustained adoption of advanced laser and imaging technology.
Asia Pacific Kidney Stone Management Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 6.86% during 2026-2035. Rising kidney stone prevalence linked to dietary change and hot climates, expanding hospital infrastructure, and growing healthcare spending continue to accelerate regional adoption of modern stone management technology. Increasing preference for flexible ureteroscopy and single-use devices is broadening access to minimally invasive treatment across the region.
China anchors regional demand through its large patient population and expanding urology infrastructure. India contributes substantial growth given its very high kidney stone prevalence and rapidly developing private hospital sector. Japan and South Korea add mature, technology-oriented demand, positioning Asia Pacific as the fastest-growing regional market through the forecast period.
MEA & Latin America Kidney Stone Management Market Insights
The Middle East & Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where hot climates contribute to elevated kidney stone prevalence and regional governments continue to expand specialist urology capacity.
Latin America is anchored by Brazil, where a sizeable domestic healthcare sector sustains steady demand for stone management devices. Mexico contributes further incremental growth as regional healthcare access continues to widen, though adoption of the most advanced laser and imaging systems across the broader region still lags more established global markets.
Market Dynamics
Growth Drivers: Rising Stone Prevalence and Minimally Invasive Adoption
Rising prevalence and recurrence of kidney stones stands as the primary growth driver. More than one in ten adults develop a stone during their lifetime, and up to half experience recurrence within five years, sustaining continuous demand for both treatment and diagnostic imaging. Dietary patterns, obesity, and climate-related dehydration continue to widen the at-risk population across both developed and emerging markets.
Continued adoption of minimally invasive treatment technology represents a second major driver. Ureteroscopy and laser lithotripsy increasingly replace open surgery for a wide range of stone sizes and locations, supported by innovation in single-use scopes, laser fibre design, and real-time pressure monitoring that improves both safety and procedural efficiency.
Restraints: High Procedure Costs and Access Disparities
High procedure and device costs remain a genuine restraint, as advanced laser lithotripsy systems and single-use ureteroscopes continue to command premium pricing that smaller facilities and price-sensitive healthcare systems can struggle to justify against limited capital and disposables budgets.
Disparities in access to specialist urology care present a further restraint, as many emerging markets and rural regions lack sufficient trained urologists and imaging infrastructure to deliver timely stone diagnosis and minimally invasive treatment, leaving some patients reliant on delayed or more invasive intervention.
Opportunities: Laser Technology Advancement and Ambulatory Care Expansion
Continued advancement of laser lithotripsy technology represents a substantial opportunity, as manufacturers that can deliver genuinely more efficient ablation, improved fibre durability, and integrated pressure monitoring stand to capture demand from urologists seeking better outcomes across an expanding range of stone compositions and locations.
Continued expansion of ambulatory surgical center capacity offers a further avenue for growth, as payers increasingly favour lower-cost outpatient delivery for uncomplicated procedures. Manufacturers that can supply compact, cost-effective systems suited to these settings are positioned to capture demand from a fast-growing customer segment.
Recent Developments:
-
2023: Boston Scientific received FDA clearance for its LithoVue Elite Single-Use Digital Flexible Ureteroscope System, the first ureteroscope with the ability to monitor intrarenal pressure in real time during ureteroscopy.
-
2026: Boston Scientific continued expanding its StoneSmart Solutions portfolio, including the Escape and OptiFlex access sheaths and Zero Tip nitinol stone retrieval baskets, to support the full stone management procedure from visualisation through retrieval.
Kidney Stone Management Market Key Players are
-
Cook Medical LLC
-
Storz Medical AG
-
Medispec Ltd.
-
Dornier MedTech GmbH
-
Richard Wolf GmbH
-
Karl Storz SE & Co. KG
-
Stryker Corporation
-
ELMED Medical Systems
-
DirexGroup
-
EDAP TMS SA
-
Coloplast A/S
-
Applied Medical Resources Corporation
-
Rocamed SAM
-
Well Lead Medical Co., Ltd.
-
PercSys, Inc.
-
Lumenis Ltd.
-
IPG Photonics Corporation
-
Becton, Dickinson and Company
Kidney Stone Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.72 Billion |
| Market Size by 2035 | USD 4.46 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Category (Treatment, Diagnostics) • By Treatment Procedure (Extracorporeal Shock Wave Lithotripsy, Ureteroscopy, Percutaneous Nephrolithotomy, Laser Lithotripsy, Others) • By Stone Type (Calcium, Uric Acid, Struvite, Cysteine) • By End User (Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Boston Scientific Corporation, Olympus Corporation, Cook Medical LLC, Storz Medical AG, Medispec Ltd., Dornier MedTech GmbH, Richard Wolf GmbH, Karl Storz SE & Co. KG, Stryker Corporation, ELMED Medical Systems, DirexGroup, EDAP TMS SA, Coloplast A/S, Applied Medical Resources Corporation, Rocamed SAM, Well Lead Medical Co., Ltd., PercSys, Inc., Lumenis Ltd., IPG Photonics Corporation, Becton, Dickinson and Company |
Frequently Asked Questions
Key players include Boston Scientific Corporation, Olympus Corporation, Cook Medical LLC, Storz Medical AG, Medispec Ltd., and Dornier MedTech GmbH, among other medical device manufacturers.
Continued advancement of laser lithotripsy technology and continued expansion of ambulatory surgical center capacity represent the primary opportunities.
Growth is primarily driven by rising prevalence and recurrence of kidney stones, combined with continued adoption of minimally invasive treatment technology.
By Category, Treatment dominated the market with a 58.60% share in 2025, reflecting sustained demand for lithotripsy systems, scopes, and disposables.
North America dominated the market with a 38.60% share in 2025, supported by high kidney stone prevalence and broad insurance coverage.
