
Magnetic Separator Market Report Scope & Overview:
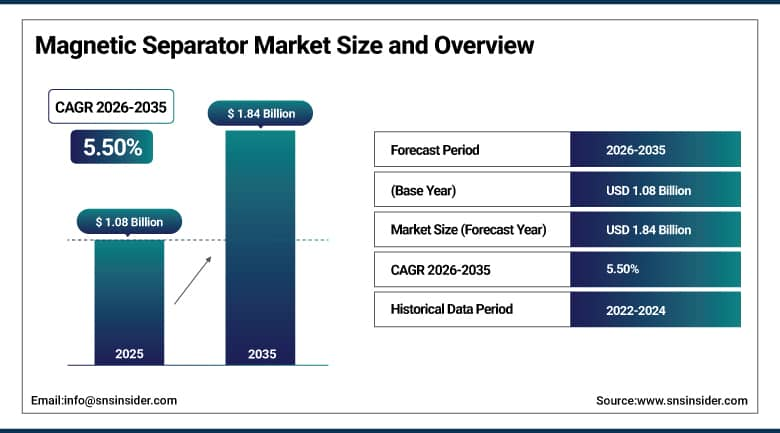
The Magnetic Separator Market was valued at USD 1.08 Billion in 2025 and is expected to reach USD 1.84 Billion by 2035, growing at a CAGR of 5.50% from 2026 to 2035.
The magnetic separator market is evolving from a basic material-handling solution into a critical technology for contamination control, resource recovery, and high-purity material processing across industries. Pulling stray metal out of a material stream sounds like a narrow, almost old-fashioned engineering problem, but it sits at the center of a surprising number of industries, mining operations protecting crushers from tramp metal, food processors keeping contaminants out of packaged product, and recyclers separating ferrous scrap from mixed waste streams before it ever reaches a landfill. Recycling regulation in particular has turned magnetic separation from a nice-to-have efficiency measure into something closer to a compliance requirement in several major markets.
In October 2025, STEINERT GmbH partnered with eFACTOR3 LLC to expand distribution, after-sales support, and a new regional testing centre for its magnetic separation and sensor-based sorting equipment across North America.
To Get More Information On Magnetic Separator Market - Request Free Sample Report
Magnetic Separator Market Trends
- AI-assisted intensity tuning is helping magnetic separators adjust automatically to variable material feed characteristics.
- Recycling facilities are adopting higher-gradient separators to recover finer non-ferrous and weakly magnetic particles.
- Predictive maintenance sensors are being built into separator drive systems to reduce unplanned downtime.
- Rare earth magnet designs are replacing older ceramic and ferrite magnets in applications needing stronger field strength.
- Regional distributors and equipment makers are expanding testing and demonstration facilities to shorten sales cycles for specialized separator configurations.
The U.S. Magnetic Separator Market Outlook
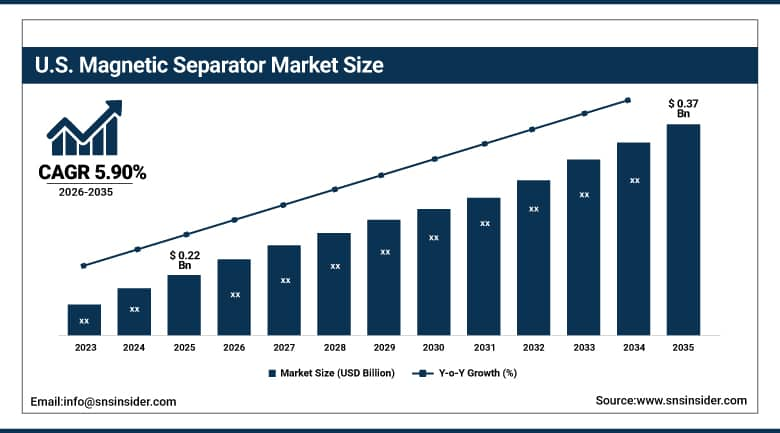
The U.S. Magnetic Separator Market was valued at USD 0.22 Billion in 2025 and is projected to reach USD 0.37 Billion by 2035, growing at a CAGR of 5.90% during 2026-2035.
Investment in recycling infrastructure has formed one of the more reliable demand drivers within the U.S., where both municipal and private material recovery facilities have been ramping up capacity to process more and more mixed waste and electronic scrap. Food processing facilities are upgrading from existing low-intensity separators to high-intensity separators that can recover smaller particles of metals, which is motivated in part by increasing food safety audit requirements. The mining sector within the western U.S. continues to employ magnetic separation not only for ore beneficiation, but also to protect equipment, forming a more stable, less cyclical, demand source than recycling. Distribution agreements such as STEINERT's recent one with a local recycling equipment manufacturer are also boosting equipment availability.
In February 2024, Eriez Manufacturing Co. launched its Xpress line of pre-engineered, modular magnetic separators designed for rapid deployment during U.S. plant upgrades and expansions.
Magnetic Separator Market Segment Analysis
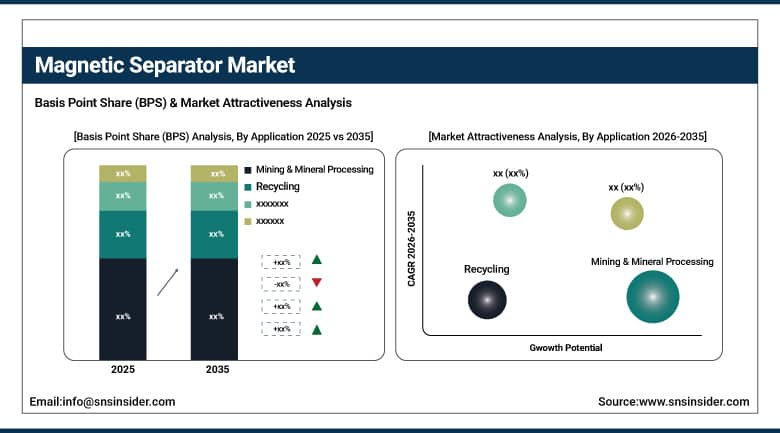
- By Application, mining & mineral processing segment dominated the magnetic separator market in 2025 with 35.4% share; recycling segment is the fastest-growing segment, registering a CAGR of 8.60% from 2026 to 2035.
- By Product Type, permanent magnet separators segment dominated the magnetic separator market in 2025 with 30.4% share; rare earth magnetic separators segment is the fastest-growing segment, registering a CAGR of 7.80% from 2026 to 2035.
- By Magnetic Field Intensity, low-intensity magnetic separators (LIMS) segment dominated the magnetic separator market in 2025 with 40.5% share; high-gradient magnetic separators (HGMS) segment is the fastest-growing segment, registering a CAGR of 8.20% from 2026 to 2035.
- By Installation Type, overband & cross-belt separators segment dominated the magnetic separator market in 2025 with 41.6% share; drum separators segment is the fastest-growing segment, registering a CAGR of 7.40% from 2026 to 2035.
By Application, mining & mineral processing dominate the magnetic separator market while recycling grows fastest
Mining & mineral processing accounts for 35.4% of application demand, the largest single category, reflecting how fundamental magnetic separation is to both ore beneficiation and equipment protection across the industry. Separators pull tramp metal out of ore streams before it reaches crushers and mills, preventing expensive equipment damage, while also playing a direct role in concentrating magnetic ore bodies like magnetite and hematite.
Recycling is the fastest-growing application, expanding at an 8.60% CAGR, as tightening waste management regulation and growing electronic scrap volumes push material recovery facilities to invest in more sophisticated separation equipment. Extended producer responsibility rules in several major markets are increasingly tying compliance to material recovery rates, which gives recyclers a direct financial incentive to capture more ferrous and weakly magnetic material than older equipment allowed.
By Product Type, permanent magnet separators dominate the magnetic separator market while rare earth magnetic separators grows fastest
Permanent magnet separators hold 30.4% of the magnetic separator market, largely because they do not need an external power source to generate their magnetic field, which makes them cheaper to operate and simpler to maintain than electromagnetic alternatives. That reliability matters most in continuous industrial processes like mining and bulk material handling, where an unplanned electrical failure taking a separator offline could mean costly downstream contamination or equipment damage.
Rare Earth Magnetic Separators are growing at a 7.80% CAGR, the fastest pace among product types, as industries chasing higher material purity need field strength that conventional ferrite or ceramic magnets simply cannot deliver. Neodymium-based separator designs can pull weakly magnetic particles that older magnet technology would miss entirely, which matters increasingly in recycling applications where recovering even small amounts of additional metal has real economic value.
By Magnetic Field Intensity, low-intensity (LIMS) dominate the magnetic separator market while high-gradient (HGMS) grows fastest
Low-intensity magnetic separators hold 40.5% of the market by magnetic field intensity, remaining the standard choice for removing strongly magnetic materials like iron and steel fragments from bulk material streams across mining, food processing, and general industrial applications. Their lower cost and simpler design make them the default first line of defense against tramp metal contamination before a process stream ever reaches more specialized separation equipment.
High-gradient magnetic separators are growing fastest, at an 8.20% CAGR, as recycling and mineral processing operations chase the ability to capture fine, weakly magnetic particles that lower-intensity equipment passes right through. This capability is becoming increasingly important as easily accessible high-grade ore deposits deplete, pushing mining operations toward processing lower-grade material where efficient fine-particle recovery matters more to overall project economics.
By Installation Type, overband & cross-belt separators dominate the magnetic separator market while drum separators grows fastest
Overband & cross-belt separators hold 41.6% of the installation-type market, valued for their ability to continuously remove tramp metal from a moving conveyor belt without interrupting material flow, a critical feature for high-throughput mining and recycling operations. Their position above the belt also makes maintenance and magnet replacement more straightforward than separators embedded within the material stream itself.
The growth rate for drum separators is the highest at 7.40% CAGR owing to their small installation area and ability to continuously clean themselves, making them highly suitable for facilities where there is a scarcity of installation area or the requirement to process high volume materials. Another advantage with drum separators is that they handle wet as well as dry material flows better than certain overband variants.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.40% |
|
Asia Pacific |
China |
36.90% |
|
Europe |
Germany |
26.60% |
|
Middle East & Africa |
UAE |
17.50% |
|
Latin America |
Brazil |
25.70% |
Asia Pacific Magnetic Separator Market Insights
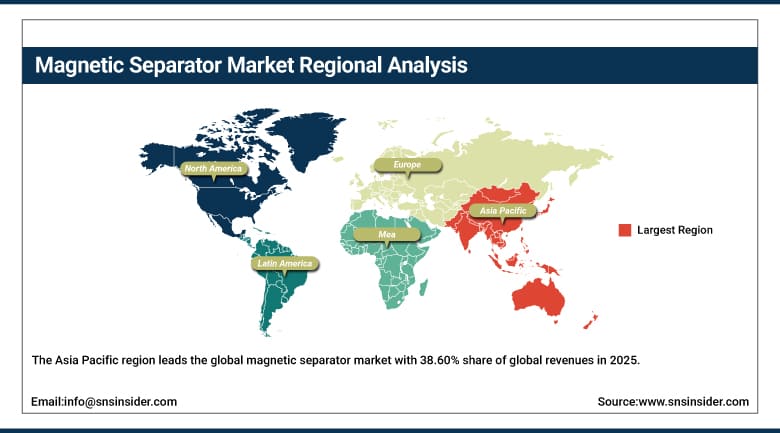
The Asia Pacific region leads the global magnetic separator market with 38.60% share of global revenues in 2025 due to the presence of huge mining and mineral processing activities, as well as rapid growth of recycling facilities. Chinese dominance in the mining activity and metal scrap generation from the manufacturing sector is driving the growth, and Indian contribution is coming from increasing demand in steel and mineral processing sectors.
In terms of share in the regional market, China dominates with 36.90% owing to mining, steel manufacturing, and recycling facilities, while India is growing at a fast pace due to the investment in mineral processing and recycling facilities. Japan and South Korea are contributing due to their electronics and food processing recycling facilities.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Magnetic Separator Market Insights
North America's magnetic separator market is steady and mature, supported by well-established mining, food processing, and recycling industries that already rely heavily on magnetic separation as standard equipment. Growth here comes mostly from equipment upgrades toward higher-intensity, rare earth-based separators rather than first-time adoption, since the underlying technology has been standard practice across these industries for decades.
The United States accounts for approximately 85.40% of the North American market, reflecting its large mining, food processing, and recycling infrastructure base. Canada contributes a smaller but steady share, tied to its own mining sector and growing investment in recycling and waste management infrastructure.
Europe Magnetic Separator Market Insights
Europe is growing faster than any other region in this market, expanding at roughly a 6% CAGR through 2035, driven by among the strictest recycling and circular economy regulations in the world. Countries across the region are tying compliance and extended producer responsibility fees directly to material recovery rates, giving recyclers a strong financial incentive to invest in more capable separation equipment rather than treating it as a discretionary upgrade.
With a market share of 26.60%, Germany holds a leading position in the European market due to its developed recycling and manufacturing industry along with some of the strongest environmental compliance standards. France and the United Kingdom come second and third, with their growing demand linked to waste management facilities.
Middle East & Africa and Latin America Magnetic Separator Market Insights
The Middle East & Africa market continues to grow steadily due to the increased mining activities in the Gulf countries and certain regions in Africa along with the development of recycling infrastructure in the major urban areas in the region. The Latin American market is growing on similar lines due to the increasing mining activities in Brazil and Chile along with increased investment in recycling infrastructure in the major cities in the region.
The UAE dominates the Middle East & Africa market with a market share of 17.50%. Brazil accounts for 25.70% share in the Latin American market due to its well-developed mining industry while Chile also contributes significantly through its copper and minerals processing facilities.
Market Dynamics
Growth Drivers: Recycling Regulation and Mineral Processing Expansion Fueling Market Growth
Tightening recycling and extended producer responsibility regulation is the clearest driver behind rising demand for more capable separation equipment, as material recovery facilities face growing pressure to capture higher percentages of recoverable metal from mixed waste streams. Expanding mineral processing activity, particularly as mining operations shift toward lower-grade ore deposits requiring more thorough separation, is adding a second significant demand line.
Food safety compliance requirements are reinforcing steady replacement demand in food and beverage processing, where even trace metal contamination can trigger costly product recalls.
Restraints: Rare Earth Material Costs and Capital Expenditure Barriers Limiting Market Expansion
Rare earth magnet materials, essential for the highest-performance separator designs, have seen meaningfully volatile pricing tied to geopolitical supply chain concentration, which makes it difficult for equipment makers to hold pricing steady on premium separator lines. Smaller mining and recycling operations often struggle to justify the capital cost of upgrading to higher-intensity or high-gradient equipment, particularly when older, lower-cost separators still meet minimum regulatory requirements.
Installation complexity for some specialized separator configurations, particularly high-gradient systems requiring careful integration with existing material handling infrastructure, can also slow adoption among facilities without in-house engineering expertise.
Opportunities: AI-Assisted Tuning and Fine-Particle Recovery Creating New Growth Avenues
AI-assisted intensity tuning represents a genuine opportunity for equipment makers to differentiate on operational efficiency rather than raw magnet strength alone, allowing separators to automatically adjust to variable material feed characteristics rather than requiring manual reconfiguration. Facilities managing highly variable waste or ore streams stand to benefit most from this kind of adaptive technology.
Fine-particle recovery capability offers a second clear opportunity, particularly in recycling applications where recovering even small additional percentages of metal has direct economic value, and in mineral processing as easily accessible high-grade ore deposits continue to deplete globally.
Recent Developments:
- 2025: STEINERT GmbH partnered with eFACTOR3 LLC to expand distribution, after-sales support, and a new regional testing centre for its magnetic separation and sensor-based sorting equipment across North America.
- 2024: Bunting Magnetics Co. introduced an enhanced liquid magnetic separator alongside its Performer Weigh metal detection system at Pack Expo, targeting contamination removal in liquid and slurry processing lines.
- 2024: Eriez Manufacturing Co. launched its Xpress line of pre-engineered, modular magnetic separators designed for rapid deployment during plant upgrades and expansions.
- 2024: Eriez Manufacturing Co. introduced new high-intensity magnetic filters and matrix-type separators at Ceramitec 2024, aimed at fine-particle separation across ceramics and industrial mineral processing.
Magnetic Separator Market key players are:
- Metso Corporation
- Eriez Manufacturing Co.
- Bunting Magnetics Co.
- STEINERT GmbH
- Goudsmit Magnetics Group
- LONGi Magnet Co., Ltd.
- Multotec (Pty) Ltd.
- IFE Aufbereitungstechnik GmbH
- Master Magnets Ltd.
- Walker Magnetics
- SGM Magnetics S.p.A.
- Industrial Magnetics, Inc.
- Magnetic Products, Inc.
- Dings Magnetic Group
- Kanetec Co., Ltd.
- Sollau s.r.o.
- Shandong Huate Magnet Technology Co., Ltd.
- National Magnetics Group, Inc.
- Eclipse Magnetics Ltd.
- Nippon Magnetics, Inc.
Magnetic Separator Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.08 Billion |
| Market Size by 2035 | USD 1.84 Billion |
| CAGR | CAGR of 5.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Permanent Magnet Separators, Electromagnetic Separators, Rare Earth Magnetic Separators, Others) • By Magnetic Field Intensity (Low-Intensity Magnetic Separators (LIMS), High-Intensity Magnetic Separators (HIMS), High-Gradient Magnetic Separators (HGMS)) • By Application (Mining & Mineral Processing, Food & Beverage, Recycling, Chemical Industry, Others) • By Installation Type (Overband & Cross-Belt Separators, Drum Separators, Suspended Separators, Pulley Separators) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Metso Corporation, Eriez Manufacturing Co., Bunting Magnetics Co., STEINERT GmbH, Goudsmit Magnetics Group, LONGi Magnet Co., Ltd., Multotec (Pty) Ltd., IFE Aufbereitungstechnik GmbH, Master Magnets Ltd., Walker Magnetics, SGM Magnetics S.p.A., Industrial Magnetics, Inc., Magnetic Products, Inc., Dings Magnetic Group, Kanetec Co., Ltd., Sollau s.r.o., Shandong Huate Magnet Technology Co., Ltd., National Magnetics Group, Inc., Eclipse Magnetics Ltd., Nippon Magnetics, Inc. |
Frequently Asked Questions
Key players include Metso Corporation, Eriez Manufacturing Co., Bunting Magnetics Co., STEINERT GmbH, and Goudsmit Magnetics Group, alongside other established magnetic separation equipment manufacturers.
Key opportunities include AI-assisted intensity tuning for variable material streams, fine-particle recovery capability for recycling and low-grade ore processing, and expanding recycling infrastructure investment tied to extended producer responsibility regulation.
The market is driven by tightening recycling and extended producer responsibility regulation, expanding mineral processing activity, and steady food safety compliance-driven replacement demand.
The Permanent Magnet Separators segment dominated the Magnetic Separator Market in 2025.
The Asia Pacific region dominated the Magnetic Separator Market in 2025, accounting for approximately 38.60% of global market share.
