
Nanomedicine Market Report Scope and Overview
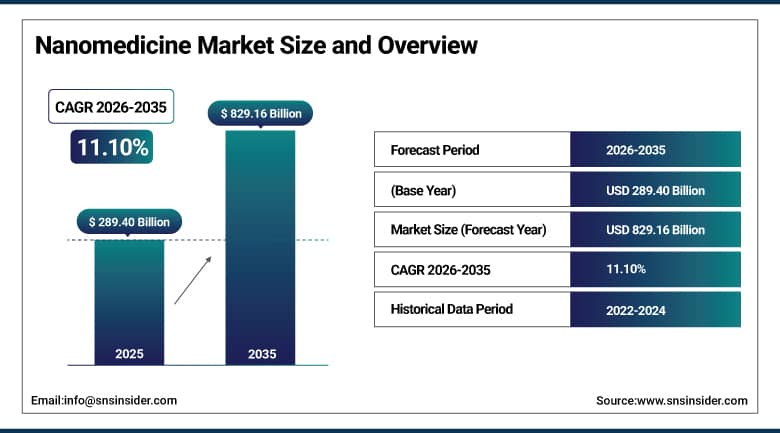
The Nanomedicine Market was valued at USD 289.40 Billion in 2025 and is estimated at USD 321.52 Billion in 2026. The market is forecast to reach USD 829.16 Billion by 2035, registering a CAGR of 11.10% from 2026 to 2035. Nanomedicine applies materials engineered at the scale of one to one hundred nanometers, such as lipid and polymer particles, to deliver drugs, image tissue, diagnose disease, and build implants. North America accounted for the largest regional share at 48.30% in 2025, while Asia Pacific is expected to grow fastest. Demand is supported by RNA therapeutics, targeted cancer treatment, and advanced drug delivery.
To Get More Information On Nanomedicine Market - Request Free Sample Report
Key Market Trends and Insights
-
By molecule type: Nanoparticles held the largest market share of 75.30% in 2025.
-
By application: Drug delivery held the largest market share of 33.20% in 2025.
-
By indication: Clinical oncology held the largest market share of 33.40% in 2025.
-
By end user: Pharmaceutical and biotechnology companies held the largest market share of 51.40% in 2025.
-
North America accounted for the largest regional share of 48.30% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 13.60% from 2026 to 2035.
-
The U.S. is the leading country market in North America, supported by a large drug development base, strong venture funding, and an experienced regulator that has reviewed nanoparticle products for three decades.
Growth Outlook
Nanomedicine has moved from a research concept to a routine part of drug development. The first nanoparticle drug, a liposomal formulation of doxorubicin, was approved by the United States Food and Drug Administration in 1995, and the field gained wide attention when the first small interfering RNA drug delivered by lipid nanoparticles was approved in 2018. Messenger RNA vaccines that relied on the same delivery approach then reached billions of people, and developers now apply nanoparticles to cancer, rare disease, infection, and gene editing programs.
Growth is also driven by the need to improve the performance of existing medicines. Many drugs dissolve poorly, break down in the body, or reach healthy tissue as well as diseased tissue, which causes side effects. Nanocarriers can protect a drug, control its release, and steer it to a target, and they allow companies to extend patent life through new formulations. As manufacturing methods mature and investment from large drug makers continues, the market is expected to expand steadily through the next decade.
Market Dynamics
Driver: RNA Therapeutics, Targeted Cancer Treatment, and Demand for Better Drug Delivery Drive Nanomedicine Adoption
Nucleic acid medicines cannot work without a delivery system, and lipid nanoparticles have become the leading choice for messenger RNA, small interfering RNA, and gene editing payloads. The approval of new mRNA products beyond COVID-19, including a first mRNA influenza vaccine in 2026, shows that the platform has regulatory acceptance, and the pipeline of RNA programs in oncology, rare disease, and infection is large. Each program needs formulation expertise, specialized lipids, and manufacturing capacity, which increases demand across the nanomedicine value chain. Investors and licensing partners also reward companies that show their delivery platform works with several drug types, so platform breadth has become a source of value.
Cancer treatment is the second major driver. Tumors are hard to treat without damaging healthy tissue, and nanoparticles can concentrate a drug or a radiation enhancer inside tumors and reduce toxicity elsewhere. Several nanoparticle products are in late stage trials, including radioenhancers for head and neck cancer and lung cancer, and regulators have shown willingness to adjust trial designs for them. Patients and physicians value treatments that reduce side effects, so oncology remains the leading area of investment for developers. Payers accept higher prices when a product shows clear gains in safety or survival, which supports the commercial case for developing new nanoparticle formulations in cancer care.
Restraint: Manufacturing Complexity, Regulatory Uncertainty, and Intellectual Property Disputes Restrain Market Growth
Nanomedicines are difficult to make consistently. Particle size, shape, surface chemistry, and drug loading must be controlled tightly, and small changes in a process can alter how a product behaves in the body. Scale up from laboratory batches to commercial supply requires specialized equipment, strict quality testing, and cold chain logistics for many products. These requirements raise costs, limit the number of qualified contract manufacturers, and slow the progress of promising candidates from the clinic to the market. Quality problems can also lead to batch rejection or delays in launch, which makes developers very careful about the choice of manufacturing partners and technology.
Regulatory and legal issues add further risk. Agencies still develop guidance on how to compare reformulated nanoparticle drugs with originals, and approval paths for generic versions remain complex. Intellectual property disputes over delivery technology can be costly, as a large settlement over lipid nanoparticle patents in 2026 showed. Many early nanoparticle drugs also failed to show strong benefits in humans because of biological barriers, which makes investors and drug makers cautious about weaker programs. Long development timelines and high clinical trial costs add to the financial risk, particularly for smaller companies that rely on outside funding to reach each milestone.
Opportunity: Contract Manufacturing Capacity, Extra-Hepatic Delivery, and Home Administered Biologics Create New Revenue Pools
Contract manufacturing is a clear area of opportunity. Drug developers that lack in-house nanoparticle expertise rely on specialized partners for formulation, fill finish, and scale up, and suppliers are investing in new facilities for lipid based products. As more RNA and nanoparticle programs move toward commercial launch, demand for qualified capacity is expected to exceed supply in several regions, which gives suppliers of lipids, equipment, and contract services room to grow. Long term supply agreements between developers and manufacturers are becoming more common, and they give both sides greater certainty over volumes, pricing, and investment in new equipment and facilities.
New product concepts offer further growth. Researchers are working on nanoparticles that reach tissues beyond the liver, such as the lung, brain, and immune cells, which would widen the range of diseases that RNA and gene editing drugs can treat. Nanoparticle technologies are also being used to make highly concentrated biologic suspensions for subcutaneous or inhaled use, so that therapies given by infusion could move to home administration and reach patients more conveniently. Companies that achieve safe and repeatable delivery to new organs would gain access to large patient groups and could command premium partnership terms from large drug makers.
Market Characteristics and Concentration
The Nanomedicine Market is Moderately Consolidated. Large pharmaceutical and vaccine companies hold the biggest commercial positions through marketed products and late stage pipelines, while specialist delivery technology firms, contract manufacturers, and diagnostic and imaging companies supply the platforms and services that these products depend on. Many of the largest companies also license delivery technology from specialists, which keeps the supplier base wide and encourages continuous partnering across the sector. Partnerships are frequent.
Competition centers on delivery technology performance, intellectual property, manufacturing quality, clinical results, and the ability to supply at commercial scale. Large drug makers compete through pipelines and funding, delivery specialists compete through proprietary lipids and carriers, and contract manufacturers compete on capacity, speed, and regulatory record. Regulatory standing is another point of difference, as companies with approved products and a clean inspection record are often chosen first for large and sensitive programs.
Barriers to entry are high because of the scientific expertise, capital, and regulatory evidence required. Patent portfolios around delivery technology are dense, clinical development is lengthy, and manufacturing sites need extensive validation. Newcomers usually succeed by focusing on a defined technology advantage or by partnering with established companies that bring clinical and commercial capability. Licensing deals are common. Early partnerships also give smaller firms access to clinical expertise, manufacturing know how, and the commercial reach that they cannot build alone.
Analyst Perspective
The Nanomedicine Market is expanding steadily because drug developers need better ways to deliver RNA medicines, target cancer treatment, and improve the performance of existing drugs. Growth is supported by regulatory precedent, new manufacturing capacity, and rising investment, while manufacturing complexity, regulatory uncertainty, and patent disputes remain challenges. North America leads today on value, while Asia Pacific is expected to expand fastest as local drug makers and research programs scale up. An SNS Insider Analyst, Santosh Bhul, commented, "Nanomedicine is becoming the delivery infrastructure for the next generation of drugs. Companies that master consistent large scale manufacturing and can show clear clinical benefit will capture the largest share of value as RNA and targeted therapies move into mainstream care."
Segment Analysis
Molecule Type Insights
Nanoparticles held the largest share of the market at 75.30% in 2025. This group includes lipid nanoparticles, liposomes, polymeric particles, metal and oxide particles, and protein based carriers, and it covers nearly all approved nanomedicine products. Nanoparticles are versatile, can be made in a wide range of sizes, and carry many types of drugs, which explains why developers choose them first for new programs in vaccines, oncology, and gene therapy. Manufacturers also value their consistent behavior at commercial scale, which reduces batch variation and regulatory risk. Safety data are reviewed closely.
Nanoshells, nanotubes, and nanodevices make up the remaining share. Nanoshells are used in photothermal cancer treatment and imaging, nanotubes are studied for sensing and drug carrying, and nanodevices include tiny sensors and delivery machines that remain mostly at the research and early clinical stage. These categories are expected to grow faster than nanoparticles from a smaller base as technical and safety questions are resolved over the forecast period. Safety questions around long term exposure are studied closely, and regulators ask developers for detailed characterization data. Companies monitor their progress closely.
Application Insights
Drug delivery held the largest share of the market at 33.20% in 2025. Nanocarriers improve solubility, protect fragile molecules, control release, and steer drugs to target tissue, so they are used in vaccines, cancer drugs, anesthetics, and RNA medicines. Developers also use nanoparticle formulations to extend product life cycles, which gives established drug makers a commercial reason to invest in delivery technology alongside the clinical benefits. Companies also report that formulation changes can bring new patents and extend the commercial life of established drugs. Patients benefit from fewer doses and less discomfort.
Therapeutics, in-vitro diagnostics, in-vivo imaging, and implants make up the rest of the market. Therapeutic nanoparticles act directly on disease, while diagnostic and imaging products use nanoparticles to detect biomarkers and improve contrast in scans. Implants use nanostructured surfaces to help bone and tissue integrate. Therapeutics are expected to grow quickly as more nanoparticle based treatments complete late stage trials and move into regular clinical practice. Imaging agents and diagnostics also benefit from these carriers, since they improve signal strength and the detection of disease at earlier stages. Costs matter.
Indication Insights
Clinical oncology held the largest share of the market at 33.40% in 2025. Cancer drugs often have serious side effects, and nanoparticles can improve how much drug reaches a tumor while reducing exposure of healthy tissue. Marketed liposomal and albumin bound cancer drugs have a long record of use, and newer radiation enhancing and RNA based products are advancing in late stage trials, which keeps oncology at the center of investment by developers and funders. Radiation enhancing particles and antibody carriers are examples of newer cancer approaches under study. Trials continue.
Infectious diseases, clinical cardiology, orthopedics, and other indications make up the remainder. Infectious disease demand rose with mRNA vaccines and continues with new vaccine and antiviral programs. Cardiology uses nanoparticles in targeted therapy and imaging, while orthopedics uses nanostructured coatings and bone graft materials. Other indications include neurology, rare diseases, and ophthalmology, where better delivery across biological barriers could unlock treatments that are not possible with conventional formulations. Vaccines for emerging infections are a further driver, since nanoparticle platforms allow companies to update products quickly for new threats. Access also matters.
End User Insights
Pharmaceutical and biotechnology companies held the largest share of the market at 51.40% in 2025. They develop and commercialize nanoparticle drugs and vaccines, buy specialized lipids and carriers, and contract formulation and manufacturing services. Large drug makers also license delivery technology from specialist firms, which creates a steady flow of partnerships, milestone payments, and royalties that supports the sector and funds early stage innovation across many platforms. Revenue also comes from supply of lipids, equipment, and formulation services, which makes this group the main source of demand for every other part of the value chain and for suppliers.
Hospitals and diagnostic centers form the next largest group because they administer nanoparticle drugs, use nanoparticle contrast agents and diagnostic tests, and take part in clinical trials. Academic and research institutes supply much of the early science and operate core facilities for characterization and testing. Their spending is smaller but sets the direction of future products, and public research funding supports a strong flow of new ideas into the commercial pipeline. Funders also support translation of discoveries into clinical trials through partnerships. Partnerships are common. Demand stays steady across the forecast period.
Regional Insights
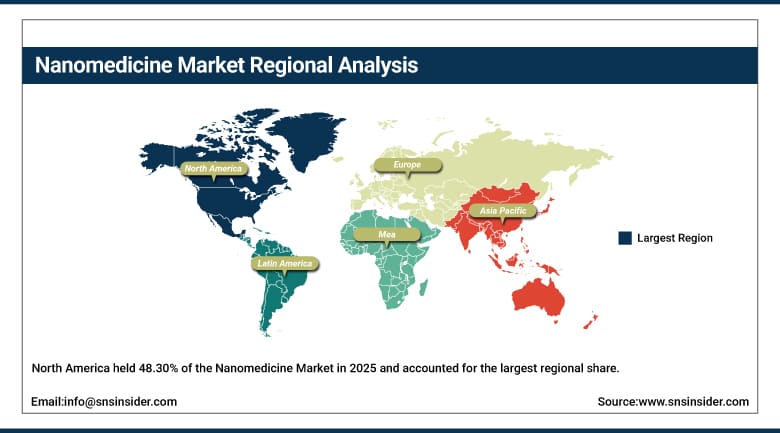
North America held 48.30% of the Nanomedicine Market in 2025 and accounted for the largest regional share. The region has the largest concentration of drug developers, venture investors, and research universities working on nanoparticle products, along with a regulator that has reviewed such products since the 1990s. Mexico is reported within Latin America. High spending on oncology and vaccine research and strong funding for RNA companies keep demand high across the region. Large networks also help.
Get Customized Report as Per Your Business Requirement - Enquiry Now
U.S. Nanomedicine Market
The U.S. Nanomedicine Market was valued at USD 128.88 Billion in 2025 and is projected to expand at a CAGR of 10.70% from 2026 to 2035. The country is home to most large drug makers working on nanoparticle products, and it operates the National Nanotechnology Initiative, which coordinates federal research funding. The Food and Drug Administration has long experience with liposomal and lipid nanoparticle products, and its guidance on liposome drug products gives developers a clear route.
Capital and capacity strengthen the market. Venture investors and public markets fund RNA and nanoparticle companies, and contract manufacturers continue to build lipid based capacity in states such as Indiana and Wisconsin. Large vaccine and oncology programs use nanoparticle formulations, and recent approvals of mRNA products beyond COVID-19 are encouraging additional investment in delivery technology and local supply chains for specialized lipids. State incentives for biomanufacturing also attract new investment into lipid and nanoparticle production sites across the country.
Europe Nanomedicine Market
Europe held 24.10% of the market in 2025, led by Germany, the United Kingdom, France, Italy, and Spain. The European Medicines Agency has issued reflection papers on nanoparticle products, including liposomes and block copolymer micelles, which guide developers on quality and clinical evidence. The region has strong academic research, several leading delivery technology firms, and large contract manufacturing sites, and public funding programs support collaboration between universities and companies. Cross border consortia also contribute. Programs continue.
Asia Pacific Nanomedicine Market
Asia Pacific held 20.80% of the market in 2025 and is expected to be the fastest growing region, at a CAGR of 13.60% from 2026 to 2035. China, Japan, India, South Korea, and Australia are the main country markets. China and India have expanded generic and specialty drug production and research funding, while Japan and South Korea have strong materials and drug delivery science. Local developers are building nanoparticle programs and manufacturing capacity to serve local and export markets.
Latin America Nanomedicine Market
Latin America accounted for 3.70% of the market in 2025, led by Brazil and Mexico. Brazil has an established research base in nanotechnology and a large pharmaceutical sector, while Mexico hosts clinical research and generic manufacturing. Demand is mainly met through imported products, and growth is supported by rising cancer incidence, expanding access to specialty drugs, and research collaboration between regional universities and international developers over the forecast period. Local firms are forming partnerships. Growth continues.
Middle East and Africa Nanomedicine Market
The Middle East and Africa held 3.10% of the market in 2025, led by Saudi Arabia, the United Arab Emirates, Israel, South Africa, and Egypt. Gulf countries are investing in biotechnology and local manufacturing under national diversification programs, and Israel has a strong base of nanotechnology start-ups. In Africa, adoption is concentrated in specialist centers and is supported by international partnerships, while access to advanced products remains limited by cost and infrastructure. Investment is rising.
Key Nanomedicine Market Company Insights
Competition in the Nanomedicine Market spans large pharmaceutical and vaccine companies, specialist delivery technology firms, contract development and manufacturing organizations, and diagnostic and imaging companies. Leading participants compete on delivery technology, intellectual property, clinical results, and manufacturing scale. Many are expanding capacity and forming partnerships to secure their positions in RNA and oncology programs.
Key Nanomedicine Companies:
-
Pfizer Inc.
-
Moderna, Inc.
-
Johnson and Johnson
-
Novartis AG
-
Merck and Co., Inc.
-
Abbott Laboratories
-
GE HealthCare Technologies Inc.
-
Nanobiotix S.A.
-
Arbutus Biopharma Corporation
-
Genevant Sciences
-
Evonik Industries AG
-
Lonza Group AG
-
Cytiva
-
Nanoform Finland Plc
Recent Developments
-
In November 2026, Lonza agreed to acquire the United States contract development and manufacturing business of Merck KGaA, which includes a site in Indianapolis for lipid nanoparticle, liposome, and PEGylated protein manufacturing. The deal serves developers of antibody drug conjugates, viral vectors, and nanoparticle programs. The company stated that the purpose was to expand its United States presence and strengthen its global manufacturing network, with closing expected in mid-2027.
-
In August 2026, Evonik announced a new GMP drug product facility for lipid-based drug delivery in Vancouver, Canada, with an investment above CAD 150 million. The site serves pharmaceutical and biotechnology customers developing vaccines and therapeutics. The company stated that the purpose was to increase development and manufacturing capacity to more than three times its current level, with production planned to begin at the end of 2029.
-
In August 2026, Moderna was reported to have received United States approval for mFLUSIVA, the first mRNA influenza vaccine, which uses lipid nanoparticle delivery. The vaccine serves adults aged 50 and older. The company stated that the approval showed the continued strength and versatility of its mRNA platform, and the product is the fourth Moderna medicine to be approved in the country.
-
In July 2026, Nanobiotix received approval from the United States Food and Drug Administration for a protocol amendment to its Phase 3 NANORAY-312 trial of NBTXR3 in head and neck cancer. The product is a nanoparticle designed to increase radiation dose inside tumor cells. The company stated that the change reduces the number of events needed for the final analysis, which could bring results earlier than planned.
-
In May 2026, Sapu Nano dosed the first patient in a Phase 1b trial of Sapu003, an intravenous nanocarrier form of everolimus. The trial enrolls patients with hormone receptor positive breast cancer and other solid tumors sensitive to mTOR inhibition. The company stated that the purpose was to overcome the limits of oral everolimus, such as inconsistent absorption and dose-limiting toxicity, by changing how the drug is delivered.
-
In May 2026, Nanoform signed an exclusivity agreement with a United States biopharmaceutical company to apply its biologics nanoparticle technology to a subcutaneous biologic medicine. The technology supports suspensions above 500 mg per mL. The company stated that the purpose was to enable concentrated formulations that reduce injection volumes and could allow home delivery of therapies that are usually given by infusion.
-
In March 2026, Genevant Sciences and Arbutus Biopharma announced a global settlement with Moderna over the use of their lipid nanoparticle technology in its COVID-19 vaccines. Moderna agreed to pay USD 950.00 Million upfront plus up to USD 1.30 Billion contingent on a court ruling. The companies stated that the purpose was to end the dispute and let them focus on nucleic acid delivery work.
-
In 2026, Cytiva expanded the lipid nanoparticle capabilities of its Precision NanoSystems business with advanced microfluidic formulation platforms. The platforms serve developers of RNA therapeutics at clinical and commercial scale. The company stated that the purpose was to speed up clinical and commercial manufacturing of RNA medicines and to give customers a consistent path from early formulation work to large batches.
Scope and Research Methodology
This report estimates the Nanomedicine Market through a bottom-up build from marketed nanoparticle products and late stage pipeline programs by region, multiplied by typical net prices and treatment volumes, and checked against a top-down view of pharmaceutical and diagnostic spending. The scope covers therapeutic, drug delivery, diagnostic, imaging, and implant products that rely on engineered nanoscale materials, and excludes bulk chemicals and general nanomaterials sold for industrial use. Assumptions are documented for net prices, treatment volumes, and launch timing of late stage products, and they are tested against developer interviews and public company commentary to keep estimates consistent across regions and years. Ranges are reviewed yearly by analysts.
Secondary research draws on regulatory approvals, clinical trial registries, company filings, patent records, and scientific publications. Primary research includes conversations with formulation scientists, clinical investigators, regulatory specialists, contract manufacturers, and company executives, used to confirm product prices, adoption rates, and capacity plans. Reported figures are cross checked against company disclosures, and Mexico is included within Latin America for regional totals. Interviews are conducted in multiple regions and with respondents of different sizes, so that views from large drug makers, delivery technology firms, contract manufacturers, and academic researchers are all represented in the final market view. Findings are documented carefully.
Segment shares are built from revenue by molecule type, application, indication, and end user, then aligned with regional totals. Forecasts apply growth assumptions for each segment and region that reflect approvals, trial outcomes, manufacturing capacity, and investment trends, and they are tested against alternative scenarios. Figures are reviewed at each update to reflect new approvals, acquisitions, and revised company results. Quality checks include a review of every input by a second analyst, comparison of results against independent indicators such as approvals and trial registrations, and a final consistency test between segment totals and regional totals. Updates are documented.
Nanomedicine Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 289.40 Billion |
| Market Size by 2035 | USD 829.16 Billion |
| CAGR | CAGR of 11.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Molecule Type (Nanoparticles, Nanoshells, Nanotubes, and Nanodevices) • By Application (Drug Delivery, Therapeutics, In-Vitro Diagnostics, In-Vivo Imaging, and Implants) • By Indication (Clinical Oncology, Infectious Diseases, Clinical Cardiology, Orthopedics, and Others) • By End User (Pharmaceutical and Biotechnology Companies, Hospitals and Diagnostic Centers, and Academic and Research Institutes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Pfizer Inc., Moderna, Inc., Johnson and Johnson, Novartis AG, Merck and Co., Inc., Abbott Laboratories, GE HealthCare Technologies Inc., Nanobiotix S.A., Arbutus Biopharma Corporation, Genevant Sciences, Evonik Industries AG, Lonza Group AG, Cytiva, Nanoform Finland Plc |

Frequently Asked Questions
The market was valued at USD 289.40 Billion in 2025 and is projected to reach USD 829.16 Billion by 2035.
The market is expected to register a CAGR of 11.10% from 2026 to 2035.
North America led the market with a 48.30% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 13.60% from 2026 to 2035.
Key players include Pfizer, Moderna, Johnson and Johnson, Novartis, and Merck and Co.
