
Offshore Decommissioning Market Report Scope & Overview:
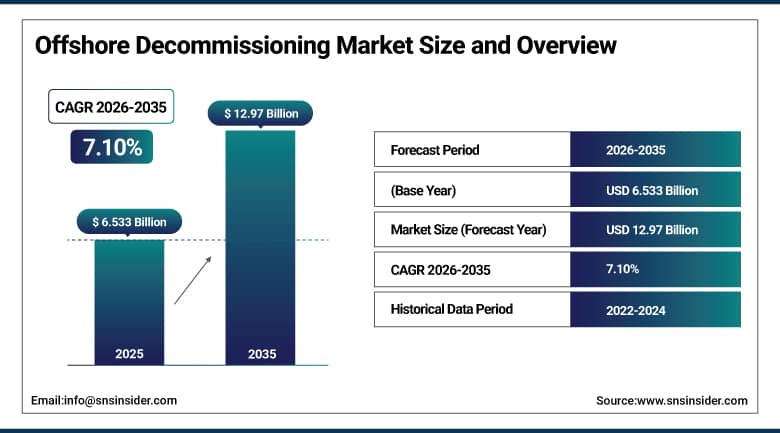
The global Offshore Decommissioning Market was valued at USD 6.533 Billion in 2025 and is expected to reach USD 12.97 Billion by 2035, growing at a CAGR of 7.10% from 2026 to 2035.
Offshore structure decommissioning includes the complex procedure of shutting down, decommissioning, and demolition of aged offshore oil and gas platforms including fixed structures, floating production structures, subsea pipelines, and wellheads. This market growth continues to be driven by the ongoing aging of existing structures that have mostly been constructed in the North Sea, Gulf of Mexico, and Southeast Asia from the 1970s through the 1990s and are reaching the end of their life cycle.
North Sea received its largest ever offshore decommissioning contract in 2025 in favor of Subsea 7 that represents one of the largest platform removal contracts within the region and is evidence of Subsea 7's strength in full-scale decommissioning solutions, thus highlighting the trend toward awarding platform removal contracts within the North Sea due to operators retiring aging platforms due to integrity issues.
Market Size and Forecast
-
Market Size in 2026E: USD 7.00 Billion
-
Market Size by 2035: USD 12.97 Billion
-
CAGR: 7.10% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
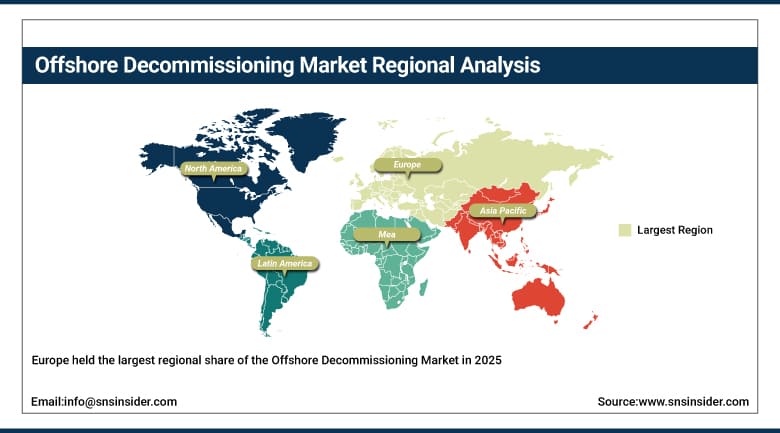
Largest Region: Europe
To Get More Information On Offshore Decommissioning Market - Request Free Sample Report
Offshore Decommissioning Market Trends
-
Growing digital decommissioning platforms are enhancing project planning and reducing operational costs through real-time data analytics and remote monitoring.
-
Rising development of advanced robotic decommissioning technologies is improving safety and efficiency across complex subsea removal operations.
-
Expanding adoption of environmentally sustainable waste management solutions is addressing recycling and disposal requirements for aging offshore structures.
-
Increasing investment in digital monitoring systems for asset integrity is enabling earlier identification of decommissioning-ready infrastructure.
-
Growing regulatory enforcement, rather than broader energy-transition narratives, continues to primarily drive aging structural asset retirement decisions.
U.S. Offshore Decommissioning Market Outlook
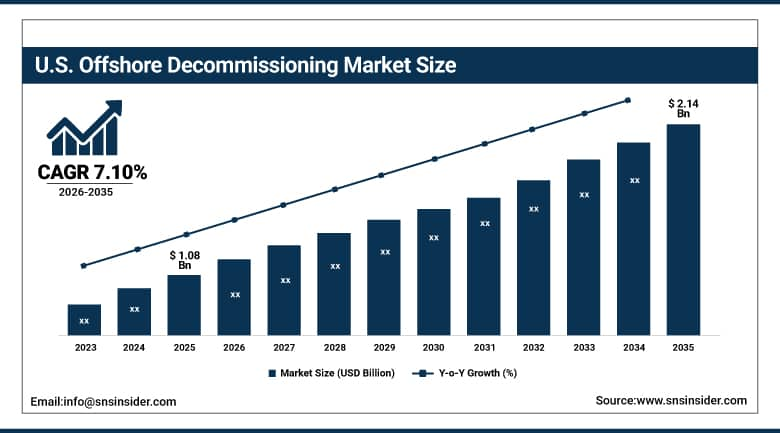
The U.S. Offshore Decommissioning Market was valued at USD 1.08 Billion in 2025 and is projected to reach USD 2.14 Billion by 2035, growing at a CAGR of 7.10% during 2026-2035.
The aging infrastructure of the Gulf of Mexico region, coupled with the robust compliance frameworks, is expected to continue driving the growth of the decommissioning market in the United States. The leading service providers are increasingly offering digital project management services and remote monitoring to address the demands of operational cost reductions. An increasing number of non-productive mature offshore wells needing plugging and abandonment will continue to drive the need for decommissioning services in the country.
In 2025, TechnipFMC introduced its digital decommissioning platform to help increase efficiency in project planning and operational cost reductions using real-time data analysis and remote monitoring features.
Offshore Decommissioning Market Segment Analysis
-
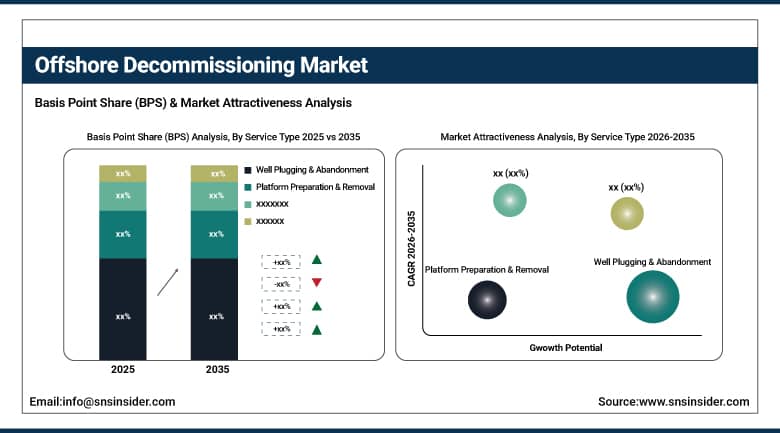
By Service Type, Well Plugging & Abandonment led the Offshore Decommissioning Market with a 34.20% share in 2025, while Platform Preparation & Removal is the fastest-growing service type segment with a CAGR of 8.60% from 2026-2035.
-
By Structure Type, Fixed Platforms led the Offshore Decommissioning Market with a 52.60% share in 2025, while Subsea Pipelines is the fastest-growing structure type segment with a CAGR of 12.70% from 2026-2035.
-
By Water Depth, Shallow Water led the Offshore Decommissioning Market with a 48.30% share in 2025, while Deepwater is the fastest-growing water depth segment with a CAGR of 9.80% from 2026-2035.
By Service Type, Well Plugging & Abandonment Dominated the Market While Platform Preparation & Removal Is the Fastest-Growing Segment
Well Plugging & Abandonment accounted for the largest revenue share of 34.20% in the Offshore Decommissioning Market, attributed to the increasing demand for the service due to the rising number of aging and non-producing offshore wells that need mandatory well plugging in order to avoid pollution. Well plugging & abandonment is an essential cost component when it comes to the retirement process of offshore fields, which helps maintain the dominance of this category among other decommissioning services.
Platform Preparation & Removal is projected to witness the highest CAGR of 8.60% from 2026 to 2035, on account of the increasing awareness about environmental issues and the growing need for full removal of structures rather than partial abandonment. The increase in the number of aging fixed platforms nearing their end of life is another factor driving the growth of this segment.
By Structure Type, Fixed Platforms Dominated the Market While Subsea Pipelines Is the Fastest-Growing Segment
Fixed Platforms held the leading share in the Offshore Decommissioning Market, accounting for 52.60% revenue share in 2025, attributed to the extensive installed base of fixed platform structure installations in shallow offshore water basins, which have been mainly developed in the 1970s-1990s. Fixed platforms remain the largest and most visible type of offshore structures to be eventually decommissioned, retaining this segment dominance within the overall offshore decommissioning market.
Subsea Pipelines is expected to witness the fastest CAGR of 12.70% over the forecast period 2026-2035, due to growing volumes of aging subsea structures approaching end-of-life, along with decommissioning programs for related platforms and wellheads. Increased awareness about the complexity of subsea pipelines decommissioning operations further supports high growth rate of this segment compared to more traditional offshore structure removal segments.
By Water Depth, Shallow Water Dominated the Market While Deepwater Is the Fastest-Growing Segment
The Shallow Water sub-segment had the largest revenue share of 48.30% in 2025, owing to a large number of fixed platform decommissioning activities taking place in mature shallow water basins such as the North Sea, Gulf of Mexico, and offshore oilfields of Southeast Asia. Shallow water oilfields form a significant share of the existing offshore infrastructure portfolio due to decades of exploitation activities taking place at these depths.
The Deep Water segment is anticipated to post the highest CAGR of 9.80% throughout the projection period from 2026 to 2035, on account of the maturing of deepwater oilfields that were discovered due to the offshore exploration rush seen over the past years. Increased complexities and dedicated vessels for deepwater decommissioning are expected to boost the growth rate of this segment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Europe |
United Kingdom |
42.60% |
|
North America |
United States |
68.60% |
|
Asia Pacific |
China |
34.60% |
|
Middle East & Africa |
Saudi Arabia |
26.40% |
|
Latin America |
Brazil |
32.60% |
Europe Offshore Decommissioning Market Insights
Europe held the largest regional share of the Offshore Decommissioning Market in 2025, supported by comprehensive regulatory frameworks, experienced service providers, and government-backed initiatives promoting safe decommissioning practices across the mature North Sea offshore basin. The North Sea Transition Authority projects the UK oil and gas industry will spend approximately USD 27.9 billion on decommissioning activities between 2023 and 2032, reinforcing the region's leadership position.
The United Kingdom led the European market with a 42.60% regional share in 2025, supported by the North Sea's extensive installed base of aging fixed platforms and substantial planned decommissioning expenditure through the 2030s. Norway, the Netherlands, and Denmark are also contributing meaningfully to regional growth, supported by mature North Sea infrastructure and strong domestic decommissioning service provider expertise.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Offshore Decommissioning Market Insights
The North American region was responsible for a considerable portion of the total Offshore Decommissioning Market in 2025 due to aging offshore structures in the Gulf of Mexico region along with stringent regulations regarding the removal of such structures. There is an existing huge installed base of legacy offshore structures that were built in the earlier phases of offshore exploration activities.
The United States holds around 68.60% of the North American market in 2025 due to aging infrastructure in the Gulf of Mexico region along with matured regulations. The Gulf of Mexico region of Mexico is also contributing to the growth of the region through aging offshore infrastructure base along with the increased participation of decommissioning services providers.
Asia Pacific Offshore Decommissioning Market Insights
Asia Pacific is identified as a fast-emerging market for the Offshore Decommissioning Market, driven by increasing offshore exploration activities and the need for localized decommissioning capabilities as regional offshore fields mature. Rising investments in decommissioning projects across Southeast Asian offshore basins continue to reinforce the region's above-average growth trajectory relative to more mature Western markets.
China accounted for approximately 34.60% of the Asia Pacific market in 2025, supported by its expanding domestic offshore oil and gas infrastructure and growing localized decommissioning service capability. Malaysia, Indonesia, and Australia are also contributing meaningfully to regional growth, with Southeast Asian offshore basins developed during earlier exploration decades now approaching end-of-life.
Middle East & Africa and Latin America Offshore Decommissioning Market Insights
The Middle East and Africa region shows consistent growth due to the expansion of the maturation of offshore fields and development of regulations in the Gulf countries. Latin America is also experiencing growth in its market due to the expansion of the offshore infrastructure and requirement for decommissioning, thanks to the strong offshore production infrastructure in Brazil.
Saudi Arabia dominated the Middle East and Africa market with 26.40% regional market share in 2025, backed by consistent maturation of regional offshore infrastructure and capability for decommissioning. The 32.60% share in the Latin America market in 2025 belonged to Brazil, due to its strong offshore oil production infrastructure, and Mexico also contributed to regional growth due to its offshore Gulf of Mexico infrastructure.
Market Dynamics
Growth Drivers: Aging Infrastructure and Regulatory Enforcement Driving Market Growth
The Offshore Decommissioning Market is more focused on the aging of offshore infrastructure, regulatory compliance, and portfolio rebalancing, instead of wider concepts of energy transitions. This equipment is now approaching the end of its service life due to higher integrity risks, corrosion problems, and higher maintenance costs, which make the operation of such facilities economically unsustainable for offshore basins developed in the 1970s-1990s.
Development of digital decommissioning tools is helping to optimize the processes of planning and implementation through real-time analytics and remote monitoring. Higher use of advanced robotic technologies for decommissioning is contributing to greater safety and efficiency of subsea disassembly works. Use of environmentally sustainable waste management methods is helping to meet higher recycling and disposal standards.
Restraints: High Capital Costs and Operational Complexity Limiting Market Expansion
Despite positive fundamentals in terms of demand, there are important constraints that exist due to high capital expenses and project complexity, which represent major challenges for small companies that have to manage their decommissioning responsibilities in relation to their offshore portfolio of assets. A complex multistage project implementation process, encompassing permitting, engineering, mobilization, removal, and cleanup, continues to necessitate close coordination between specialized service providers.
Volatile prices for oil and gas commodities continue to affect operator ability and capability to cover decommissioning responsibilities, especially for small independent operators that have limited balance sheets. Scarcity of specialized vessels capable of lifting heavy cargo and executing decommissioning projects remains an issue that limits flexibility in project scheduling, especially in case of multiple concurrent large-scale removal projects.
Opportunities: Digital Technology Integration and Emerging Market Expansion Creating New Growth Avenues
Substantial opportunity exists in continued development of digital monitoring and integrated project management platforms capable of delivering measurable cost reduction and schedule predictability improvements. Service providers that successfully commercialize real-time data analytics and remote monitoring capability stand to capture significant share of category growth as operators increasingly prioritize cost efficiency alongside safety and environmental compliance.
Growing offshore exploration maturation across emerging markets in Asia Pacific and Latin America represents a further significant growth avenue, as regional offshore fields developed during earlier exploration decades approach end-of-life and require localized decommissioning capability. Continued advancement in robotic and remote decommissioning technology also represents meaningful opportunity for service providers seeking to reduce operational risk and cost across complex subsea removal operations.
Recent Developments:
-
2025: Subsea 7 secured a major offshore decommissioning contract in the North Sea, marking one of the largest platform removal projects in the region.
-
2025: TechnipFMC announced the launch of a new digital decommissioning platform designed to enhance project planning and reduce operational costs through real-time data analytics.
-
2026: AF Offshore Decom announced its latest offshore decommissioning project, involving dismantling and recycling of aging offshore structures utilizing advanced engineering and responsible environmental practices.
-
2023-2032: The North Sea Transition Authority projects the UK oil and gas industry will spend approximately USD 27.9 billion on decommissioning activities across the UK Continental Shelf.
Offshore Decommissioning Companies are:
-
TechnipFMC plc
-
Subsea 7 S.A.
-
Saipem S.p.A.
-
Baker Hughes Company
-
Petrofac Limited
-
Aker Solutions ASA
-
John Wood Group PLC
-
Royal Boskalis Westminster N.V.
-
Allseas Group S.A.
-
AF Offshore Decom
-
Heerema Marine Contractors
-
Van Oord
-
DeepOcean Group Holding BV
-
Fluor Corporation
-
McDermott International, Ltd.
-
Worley Limited
-
Ramboll Group A/S
-
Oceaneering International, Inc.
-
Enquest PLC
-
Repsol S.A.
Offshore Decommissioning Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.533 Billion |
| Market Size by 2035 | USD 12.97 Billion |
| CAGR | CAGR of 7.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Well Plugging & Abandonment, Platform Preparation & Removal, Pipeline Decommissioning, Site Remediation) • By Structure Type (Fixed Platforms, Floating Production Systems, Subsea Pipelines) • By Water Depth (Shallow Water, Deepwater, Ultra-Deepwater) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TechnipFMC plc, Subsea 7 S.A., Saipem S.p.A., Baker Hughes Company, Petrofac Limited, Aker Solutions ASA, John Wood Group PLC, Royal Boskalis Westminster N.V., Allseas Group S.A., AF Offshore Decom, Heerema Marine Contractors, Van Oord, DeepOcean Group Holding BV, Fluor Corporation, McDermott International, Ltd., Worley Limited, Ramboll Group A/S, Oceaneering International, Inc., Enquest PLC, Repsol S.A. |
Frequently Asked Questions
The Offshore Decommissioning Market is expected to grow at a CAGR of 7.10% from 2026 to 2035.
The Offshore Decommissioning Market was valued at USD 6.533 Billion in 2025.
The market is driven by the aging of structural offshore assets, regulatory enforcement, and the economic reprioritization of offshore portfolios.
The Well Plugging & Abandonment segment dominated the Offshore Decommissioning Market in 2025, accounting for approximately 34.20% market share.
The Europe region dominated the Offshore Decommissioning Market in 2025.
