
Omnichannel Retail Commerce Market Report Scope & Overview:
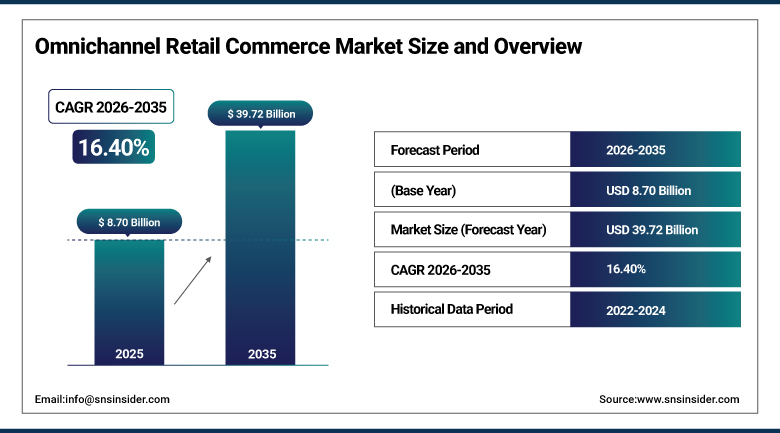
The Omnichannel Retail Commerce Market was valued at USD 8.70 Billion in 2025 and is expected to reach USD 39.72 Billion by 2035, growing at a CAGR of 16.40% from 2026-2035.
The Omnichannel Retail Commerce Market covers software platforms, order and inventory systems, customer data tools, point-of-sale systems and services that let retailers sell and serve customers consistently across stores, websites, apps, marketplaces, social channels and delivery. Shoppers expect to browse online, buy in store, pick up curbside or return anywhere, and retailers need one view of stock and customers. Growth is supported by cloud commerce, AI agents, mobile shopping and quick delivery, while legacy systems, data silos and integration cost shape adoption.
⮞In July, 2026, Salesforce announced general availability of Shopper Agent, Buyer Agent and Merchant Agent in Agentforce Commerce, spanning business-to-consumer, business-to-business, order management and point-of-sale. The release includes native integration with ChatGPT and Google Search, including AI Mode, and the company said retailers running their own shopper agents grew sales 59% faster than those without them.
To Get more information Omnichannel Retail Commerce Market - Request Free Sample Report
Omnichannel Retail Commerce Market Trends
- Use of AI shopping agents and conversational assistants across retail channels
- Shift from separate online and store systems to unified commerce platforms
- Growth of buy online, pick up in store and ship-from-store fulfillment
- Open standards that let AI platforms discover and transact with merchant catalogs
- Spread of quick commerce and marketplace integration through order management tools
- Adoption of cloud point-of-sale systems with in-store returns and clienteling
U.S. Omnichannel Retail Commerce Market Outlook
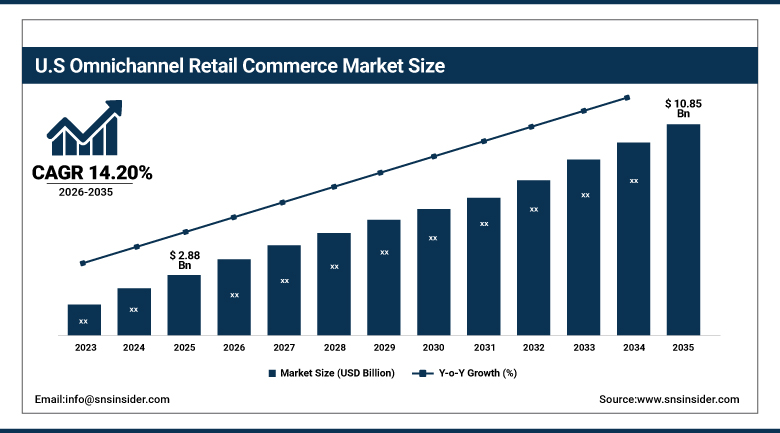
The U.S. Omnichannel Retail Commerce Market was valued at USD 2.88 Billion in 2025 and is expected to reach USD 10.85 Billion by 2035, growing at a CAGR of 14.20% from 2026-2035.
The U.S. Omnichannel Retail Commerce Market is the largest national market, supported by a mature e-commerce base, large store networks, strong software vendors and heavy investment in fulfillment. Retailers use store pickup, ship-from-store and same-day delivery to compete with online platforms, and merchants of all sizes rely on cloud commerce tools. Growth is moderated by legacy systems, integration cost, thin retail margins and tight competition from marketplaces.
⮞In June 17, 2026, Shopify launched its Spring '26 Edition, including the Universal Commerce Protocol co-developed with Google, a Catalog API that makes merchant products searchable by AI platforms, and POS v11 with in-store returns through a QR code in the Shop app. The release also expanded its Sidekick AI assistant across admin screens.
Omnichannel Retail Commerce Market Segment Analysis
- By Solution, e-commerce platforms segment dominated the Omnichannel Retail Commerce Market in 2025 with an estimated 30.00% share; order management segment is the fastest-growing segment, with an estimated CAGR of 19.50% during 2026–2035.
- By Deployment, SaaS segment dominated the Omnichannel Retail Commerce Market in 2025 with an estimated 56.00% share, and is also the fastest-growing segment, with an estimated CAGR of 18.20% during 2026–2035.
- By Retail Vertical, apparel and footwear segment dominated the Omnichannel Retail Commerce Market in 2025 with an estimated 27.00% share; FMCG and grocery segment is the fastest-growing segment, with an estimated CAGR of 19.00% during 2026–2035.
- By Retailer Size, large retailers segment dominated the Omnichannel Retail Commerce Market in 2025 with an estimated 64.00% share; small and medium retailers segment is the fastest-growing segment, with an estimated CAGR of 19.60% during 2026–2035.
By Solution, E-Commerce Platforms Dominates Omnichannel Retail Commerce Market; Order Management to Register Fastest Growth.
E-commerce platforms dominate the Omnichannel Retail Commerce Market because the storefront, catalog, checkout and promotion engine form the base on which other tools connect. Retailers invest in platforms that support web, mobile apps, marketplaces and social selling from one catalog. Vendors such as Shopify, Salesforce, Adobe, Oracle and SAP sell broad suites, and moving to a new platform is a large project, so contracts are long and revenue is recurring. Payment, tax and shipping connectors bundled with the platform also add switching costs, which keeps customers loyal.
Order management is projected to register the fastest growth because retailers must decide in real time where to fulfill each order from, whether a store, warehouse or supplier. Pickup in store, ship-from-store, returns anywhere and quick delivery all depend on a single view of inventory. Order management systems link to marketplaces and delivery services, and retailers adopt them to cut split shipments, lower delivery cost and avoid stockouts. Retailers also measure results by the share of orders fulfilled from stores, which pushes vendors to improve routing logic.
By Deployment, SaaS Dominates Omnichannel Retail Commerce Market and Is Also the Fastest-Growing Segment.
SaaS deployment dominates the Omnichannel Retail Commerce Market because retailers prefer subscription tools that update automatically, scale during peak seasons and avoid heavy hardware spending. Cloud platforms handle traffic spikes on shopping holidays and integrate quickly with payments, logistics and marketing apps. Vendors release new features frequently, including AI assistants, so retailers keep pace with changing shopper expectations without long upgrade projects. Security patching and compliance support from the vendor also lower the burden on retailer IT teams. Fast rollout across many stores is also a benefit of cloud tools.
SaaS is also projected to register the fastest growth as small and mid-sized retailers adopt cloud commerce for the first time and large retailers retire older on-premise systems. Subscription pricing lowers entry cost, and application marketplaces let retailers add functions as needed. Data stored in the cloud supports shared customer profiles and AI models, which is difficult to achieve with separate store systems and legacy databases. Open application programming interfaces also let retailers connect new channels, such as social shops and AI assistants, within weeks.
By Retail Vertical, Apparel and Footwear Dominates Omnichannel Retail Commerce Market; FMCG and Grocery to Register Fastest Growth.
Apparel and footwear dominates the Omnichannel Retail Commerce Market because fashion brands sell through many channels, including own stores, websites, marketplaces and wholesale partners, and manage complex size and color inventory. Returns are frequent, so unified stock and returns handling are valuable. Brands use clienteling, loyalty programs and endless-aisle tools in stores, and investment in omnichannel platforms is a standard part of competing in fashion retail. Peak seasons and frequent promotions also test systems, so fashion retailers value platforms that handle surges smoothly.
FMCG and grocery is projected to register the fastest growth as supermarkets and consumer goods brands expand online ordering, click and collect, home delivery and quick commerce. Fresh products and tight delivery windows need accurate store-level inventory and smart picking. Retailers are also linking loyalty data and digital coupons to online and in-store purchases, which raises demand for platforms that connect customer, order and payment data. Loyalty programs and subscription services also encourage shoppers to buy more often through apps and stores.
By Retailer Size, Large Retailers Dominates Omnichannel Retail Commerce Market; Small and Medium Retailers to Register Fastest Growth.
Large retailers dominate the Omnichannel Retail Commerce Market because they operate hundreds of stores, multiple brands and several digital channels, and they have the budgets for integrated platforms and systems integrators. They spend on order management, analytics, point-of-sale refreshes and AI projects, and they negotiate multi-year agreements with major vendors, which gives vendors large contract values and a strong share of market revenue. Large retailers also tend to buy several modules together, such as order management, analytics and personalization, from one vendor.
Small and medium retailers are projected to register the fastest growth as affordable cloud tools bring omnichannel capability within reach of local chains and independent brands. Packaged integrations connect storefronts, marketplaces, payments and shipping, and pre-built point-of-sale apps support store pickup. Platform providers target this group with simple pricing and AI assistants that reduce the need for technical staff, which opens a large base of new customers. Local payment support and low-code tools also help small retailers get online faster without hiring developers. Pricing tiers by order volume also suit growing sellers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
87.00 |
|
Europe |
Germany |
24.00 |
|
Asia Pacific |
China |
35.00 |
|
Latin America |
Brazil |
49.00 |
|
Middle East & Africa |
United Arab Emirates |
32.00 |
North America Omnichannel Retail Commerce Market Insights
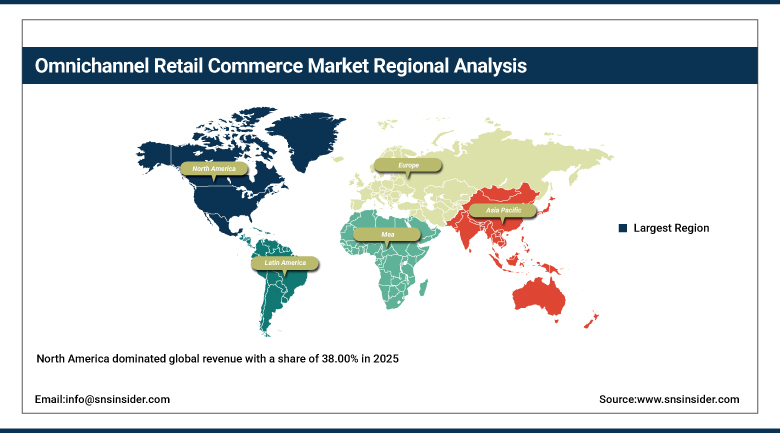
North America dominated global revenue with a share of 38.00% in 2025. The United States accounts for dominant share of regional demand, with Canada adding volume through bank-linked and grocery retailers. Salesforce, Shopify, Adobe, Oracle, Microsoft, IBM, NCR, Toshiba Global Commerce Solutions and Zebra Technologies serve retailers across the region. Canada adds demand through large grocery and department store chains, and Mexico adds smaller volumes through retailers that expand online sales and store pickup in large cities.
High e-commerce penetration, large store networks and strong vendor ecosystems support leadership. Retailers invest in order management, point-of-sale refreshes and AI assistants to compete with large marketplaces. Legacy technology, thin margins and integration complexity moderate growth, but demand for faster fulfillment and unified customer data continues to push retailers toward cloud-based omnichannel platforms. Retail technology vendors, payments firms and logistics providers in the region also form partnerships that give retailers one contact for software, payments and delivery, which shortens project timelines.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Omnichannel Retail Commerce Market Insights
In Europe Germany leads regional demand, followed by the United Kingdom, France, the Netherlands and the Nordic countries, supported by strong online adoption and fashion, grocery and electronics retailers. Zalando, Lightspeed, SAP, Adyen and Teamwork Commerce are among the companies serving the region. The United Kingdom, France and the Netherlands add large volumes through fashion, grocery and electronics chains, while Spain, Italy and the Nordic countries add steady demand as retailers upgrade point-of-sale systems and expand click and collect.
European retailers must manage many languages, currencies, tax rules and delivery norms, so platforms that support multi-country operation are valued. Sustainability and returns reduction goals influence fulfillment design. Fragmented markets, data protection rules and cautious spending in some countries slow growth, though unified commerce projects at fashion and sports brands continue to expand. Cross-border shopping within the European Union also encourages retailers to adopt platforms that handle several currencies, and sports and fashion brands lead the shift to unified commerce across their store networks.
On August 26, 2026, Teamwork Commerce announced that ASICS Europe is now using its omnichannel retail platform, joining ASICS units in Mexico, America, Canada and Australia, alongside payments from Adyen.
Asia Pacific Omnichannel Retail Commerce Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 19.80% during 2026-2035. China leads regional demand, followed by India, Japan, South Korea, Australia and Southeast Asia, supported by mobile shopping, super apps, live commerce and quick delivery. TCS, Unicommerce, Ace Turtle and global vendors serve retailers in the region. Japan and South Korea add demand through convenience stores, department stores and electronics chains, while Australia adds steady volumes through fashion and grocery retailers that offer store pickup and delivery. Super apps also help drive store traffic.
Online and offline blending is well established in China, while India is building omnichannel retail quickly through quick commerce, marketplace integration and store networks. Retailers in Southeast Asia use cloud tools to link shops, marketplaces and social selling. Varied payment methods, logistics gaps outside large cities and platform fees restrain growth, but rising mobile use supports strong demand. Marketplace integration is also a core need in the region, since many brands sell through several marketplaces at once and need real-time stock updates across them.
On September 9, 2025, Dabur India's retail arm NewU partnered with Unicommerce to deploy its Uniware suite across its website, marketplaces, quick commerce platforms and more than 120 stores in over 35 cities.
MEA & Latin America Omnichannel Retail Commerce Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina, Colombia and Chile. Large retailers such as Magazine Luiza use stores as fulfillment points, and marketplaces and payment apps drive digital adoption. Economic swings, delivery cost and fragmented logistics moderate growth. Mexico, Argentina and Colombia add smaller volumes through department stores and grocery chains, and Chile adds demand through large retailers that use stores as pickup points, while payment apps and marketplaces bring more shoppers online.
In the Middle East and Africa, the United Arab Emirates, Saudi Arabia, Egypt and South Africa lead demand. In July, 2024, Dubai-based Landmark Group partnered with Unicommerce for multi-channel order and inventory management in the UAE and Saudi Arabia, starting with its Homebox brand. High mobile use and large mall retailers support omnichannel investment. Saudi Arabia adds demand through mall operators and national retail programs, and Egypt and South Africa add volumes through grocery and fashion chains that are adding online sales and delivery.
Market Dynamics
Growth Drivers: Shopper Expectations, AI Agents and Fast Fulfillment
Shoppers now move between phones, websites and stores in one purchase, and expect stock visibility, pickup and easy returns. Retailers that cannot offer this lose sales to marketplaces and direct brands. Rising delivery expectations also push retailers to use stores as mini warehouses. Mobile payments also make checkout faster across channels, which raises conversion and encourages repeat purchases.
AI shopping agents, new commerce protocols and quick delivery services are adding new channels and raising the need for accurate catalog and inventory data. Vendors are releasing agent tools that help retailers sell on their own sites and on AI platforms. Retail media and loyalty programs also reward retailers that hold unified customer data. Brands that sell directly to shoppers also invest in store networks to improve reach and returns handling.
Restraints: Legacy Systems, Integration Cost and Data Silos
Many retailers run older point-of-sale and inventory systems that do not share data in real time, and replacing them is costly and risky. Integration projects can take many months and need skilled staff. Staff training and change management also add cost, since store teams must learn new tools and processes. Long contracts can also slow switching.
Customer and stock data often sit in separate systems across channels and franchisees, which limits unified views. Thin margins and seasonal cash flow also make large technology projects harder to approve. Data protection rules also vary by country, which complicates sharing customer data across channels.
Opportunities: Quick Commerce, Small Retailers and Agentic Commerce
Quick commerce, store-based fulfillment and marketplace integration create demand for order management and inventory tools. Small and mid-sized retailers represent a large base that is moving to cloud platforms. Vendors can also offer pre-built connectors for marketplaces and delivery apps to speed up launches. Subscription pricing also lowers upfront cost.
Agentic commerce lets AI assistants search, compare and buy from merchant catalogs, creating demand for open catalogs and checkout standards. Personalization, loyalty and retail media based on unified data offer further revenue. Retailers in emerging markets may skip older systems and adopt cloud tools from the start. Cloud vendors also bundle analytics so that smaller retailers gain insight without extra tools.
Recent Developments:
- In August 2026, Teamwork Commerce announced that ASICS Europe uses its omnichannel retail platform. ASICS Europe joins its Mexico, America, Canada and Australia units on the system.
- In July 2026, Salesforce made Shopper Agent, Buyer Agent and Merchant Agent in Agentforce Commerce generally available. The release includes native ChatGPT and Google Search integration.
- In June 2026, Shopify launched its Spring '26 Edition. It includes the Universal Commerce Protocol, a Catalog API and POS v11 with in-store returns.
- In September 2025, Dabur India's retail arm NewU partnered with Unicommerce for omnichannel order management. The deployment covers its website, marketplaces, quick commerce and more than 120 stores.
- In July 2024, Landmark Group partnered with Unicommerce for multi-channel order and inventory management. The arrangement covers its UAE and Saudi Arabia operations, starting with Homebox.
Omnichannel Retail Commerce Market Key Players are:
- Salesforce, Inc.
- Oracle Corporation
- SAP SE
- Adobe Inc.
- International Business Machines Corporation
- Shopify Inc.
- Microsoft Corporation
- NCR Corporation
- Toshiba Global Commerce Solutions
- Zebra Technologies Corporation
- BigCommerce Holdings, Inc.
- Lightspeed Commerce Inc.
- Unicommerce eSolutions Ltd.
- Teamwork Commerce
- Ace Turtle
- Tata Consultancy Services Ltd.
- Adyen N.V.
- Zalando SE
- Google LLC
- Magazine Luiza S.A.
Omnichannel Retail Commerce Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.70 Billion |
| Market Size by 2035 | USD 39.72 Billion |
| CAGR | CAGR of 16.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Solution (E-Commerce Platforms, Order Management, Customer Relationship Management, Point of Sale, and Others) • By Deployment (SaaS and On-Premise) • By Retail Vertical (Apparel and Footwear, FMCG and Grocery, Consumer Electronics, Home and Furniture, and Others) • By Retailer Size (Large Retailers and Small and Medium Retailers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Salesforce, Inc.; Oracle Corporation; SAP SE; Adobe Inc.; International Business Machines Corporation; Shopify Inc.; Microsoft Corporation; NCR Corporation; Toshiba Global Commerce Solutions; Zebra Technologies Corporation; BigCommerce Holdings, Inc.; Lightspeed Commerce Inc.; Unicommerce eSolutions Ltd.; Teamwork Commerce; Ace Turtle; Tata Consultancy Services Ltd.; Adyen N.V.; Zalando SE; Google LLC; Magazine Luiza S.A. |

Frequently Asked Questions
Key players include Salesforce, Inc., Oracle Corporation, SAP SE, Adobe Inc., International Business Machines Corporation, Shopify Inc., Microsoft Corporation and NCR Corporation.
Key opportunities include quick commerce and store-based fulfillment, cloud adoption by small and mid-sized retailers, and agentic commerce through AI assistants.
The major growth factor is shopper demand for a seamless experience across stores, apps and websites, supported by cloud platforms, AI agents and faster fulfillment.
By Solution, the E-Commerce Platforms segment dominated the market in 2025 with an estimated 30.00% share, supported by long-term platform contracts.
North America dominated the market with a share of 38.00% in 2025, driven by high e-commerce penetration, large store networks and strong vendors.
