
Organ on a Chip Market Report Scope & Overview:
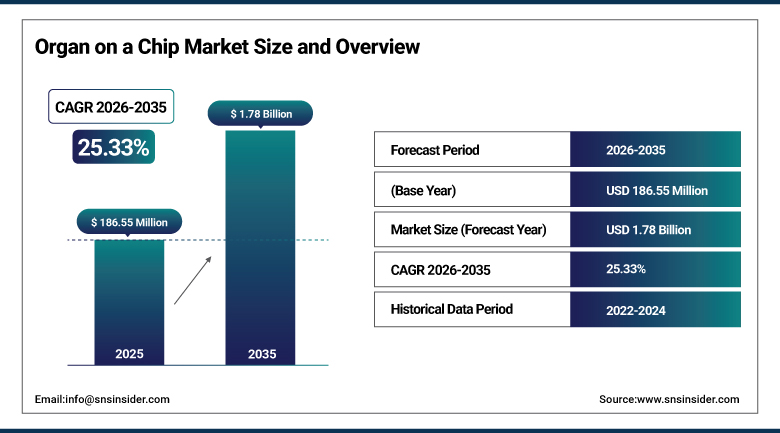
The Organ on a Chip Market was valued at USD 186.55 Million in 2025 and is expected to reach USD 1.78 Billion by 2035, growing at a CAGR of 25.33% from 2026-2035.
The Organ on a Chip Market covers microfluidic devices lined with living human cells that reproduce the structure and function of tissues such as lung, liver, heart, kidney, and brain. These systems allow researchers to test drug safety and efficacy, model disease, and study toxicity without relying solely on animal experiments. Demand is rising as pharmaceutical developers look for models that predict human responses more reliably, and as regulators signal openness to non-animal methods. Vendors supply chips, perfusion instruments, cell models, and contract testing services, and are increasingly connecting multiple organs on a single platform to study systemic effects. Academic spinouts, instrument makers, and contract laboratories all participate, and partnerships between them are common.
⮞In April 2025, the U.S. Food and Drug Administration announced a roadmap to phase out animal testing requirements for monoclonal antibodies and other drugs, naming organ-on-a-chip systems for liver, heart, and immune organs as examples of new approach methods.
To Get more information Organ on a Chip Market - Request Free Sample Report
Organ on a Chip Market Trends
- Development of multi-organ platforms that link several tissue models in one system
- Integration of artificial intelligence and automation for high-throughput screening
- Use of patient-derived cells to build personalized disease models
- Growing regulatory qualification of chips for defined contexts of use
- Expansion of brain and neurological chips for central nervous system drug testing
U.S. Organ on a Chip Market Outlook
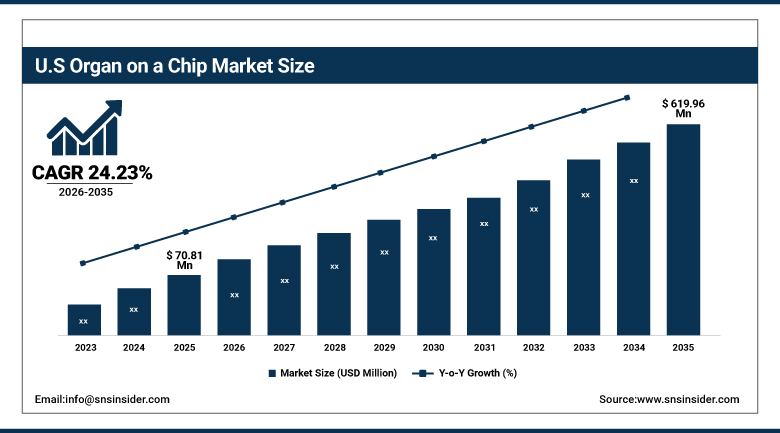
The U.S. Organ on a Chip Market was valued at USD 70.81 Million in 2025 and is expected to reach USD 619.96 Million by 2035, growing at a CAGR of 24.23% from 2026-2035.
The U.S. Organ on a Chip Market is the largest national market, supported by strong academic research, venture funding, and a regulator that has publicly encouraged non-animal approaches. Pharmaceutical companies in Boston, San Francisco, and the Research Triangle operate in-house organ chip laboratories and collaborate with technology developers. Federal agencies are funding validation networks and qualification efforts, while legislation to modernize drug development rules is advancing in Congress. Vendors that secure formal qualification for specific contexts of use are expected to gain a clear advantage with large drug makers. Public research hospitals and national laboratories contribute to the validation datasets that sponsors need.
⮞In July 2026, the U.S. House of Representatives passed H.R. 2821, the FDA Modernization Act 3.0, which would update federal rules to allow non-animal testing methods.
Organ on a Chip Market Segment Analysis
- By Offering, the Products segment dominated the Organ on a Chip Market with approximately 54.20% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 32.38%.
- By Organ Type, the Lung segment dominated the Organ on a Chip Market with approximately 34.12% share in 2025, while the Heart segment is the fastest growing with a CAGR of approximately 27.81%.
- By Application, the Drug Discovery segment dominated the Organ on a Chip Market with approximately 55.92% share in 2025, while the Disease Modeling segment is the fastest growing with a CAGR of approximately 30.83%.
- By End User, the Pharma and Biotech Companies segment dominated the Organ on a Chip Market with approximately 62.27% share in 2025, while the CROs segment is the fastest growing with a CAGR of approximately 30.77%.
By Offering, Products Dominate Organ on a Chip Market; Services to Register Fastest Growth.
Products lead the offering landscape because every study begins with the purchase of chips, perfusion instruments, and cell culture consumables. Pharmaceutical laboratories and academic groups build installed bases that generate repeat orders for disposables and media. Vendors are also bundling hardware with imaging and analysis software, which raises switching costs, and standardized formats make it easier for new users to adopt the technology without extensive in-house engineering expertise. Consumable sales also recur with each experiment across many research laboratories.
The services segment is expanding rapidly due to organizations that lack organ-on-a-chip expertise seeking outsourced services from specialized vendors. Testing services, assay development services, and customized models ensure that sponsors are able to gain validated protocols and generate data for discussion in regulatory authorities. The service providers are expanding their laboratory capacity and collaborating with contract research organizations in order to fulfill demand. Research projects that require multi-organ constructs or cell cultures sourced from patients usually depend greatly on services from specialized service providers.
⮞In February 2026, the Integrated Alliance for Microphysiological Systems, a European industry alliance for microphysiological systems, was launched by leading European developers.
By Organ Type, Lung Dominates Organ on a Chip Market; Heart to Register Fastest Growth.
Lung Chips excel due to the already established applications and commercially viable need for them in the study of respiratory disease, inhaled drugs, and infections. The breathing mechanics, air/liquid interface, and immune cell recruitment have all been modeled in this system, providing the researchers with information not available in conventional cultures. They are also used by the pharmaceutical industry in toxicity testing of inhaled compounds, vaccine research, and antiviral experiments, all based on the huge amount of existing literature validating their use.
Heart chips are growing fastest as developers use them to detect arrhythmia risk and cardiotoxicity earlier in drug development. Cardiac safety failures remain a leading cause of drug withdrawal, so regulators and sponsors value human-relevant predictive tools. Advances in stem cell-derived cardiomyocytes, contractility sensors, and electrophysiology readouts are improving reproducibility. Liver, kidney, brain, and gut chips form the remaining categories and each is gaining momentum in toxicity and disease research. Collaborations with cardiology centers add useful clinical validation data.
⮞A lung-on-chip study with the Francis Crick Institute on early Mycobacterium tuberculosis infection, developed by AlveoliX, was featured on the cover of Science Advances on 2 January 2026.
By Application, Drug Discovery Dominates Organ on a Chip Market; Disease Modeling to Register Fastest Growth.
Drug discovery leads because high attrition in clinical trials has pushed developers to seek more predictive models early in the pipeline. Organ chips are used for target validation, efficacy screening, and safety assessment before candidates move into costly human studies. Pharmaceutical companies are integrating them into decision workflows alongside organoids and computational tools, and success stories are encouraging further adoption in lead optimization and candidate selection programs. Reduced reliance on animal cohorts can lower study costs for selected programs.
Disease modeling is growing fastest as researchers recreate conditions such as fibrosis, neurodegeneration, infection, and cancer using patient-derived cells. These models support mechanistic studies and allow drugs to be tested on genetically defined populations. Rare diseases with limited animal models benefit particularly. Funding agencies are backing personalized chip approaches, and toxicology research continues to expand alongside as regulators accept supporting data from human-relevant systems. Academic consortia are now sharing protocols, which is accelerating the reproducible adoption by laboratories everywhere.
⮞In January 2026, a 3Rs Collaborative project involving CN Bio, FDA CDER, NIH-NICEATM, the Critical Path Institute, and Merck was accepted into the FDA ISTAND program to test liver systems for drug-induced liver injury.
By End User, Pharma and Biotech Companies Dominate Organ on a Chip Market; CROs to Register Fastest Growth.
Pharma and biotech companies lead because they carry the cost of late-stage failures and have the budgets to adopt new platforms. Large drug makers run internal organ chip groups, sponsor method development, and collaborate with vendors on custom models. Smaller biotechs use chips to generate differentiating safety and efficacy data that supports partnering and financing. Regulatory engagement on qualification typically begins with these sponsors. Dedicated internal budgets for new approach methods are also appearing in large corporate research groups.
Contract research organizations are growing fastest as sponsors outsource experiments requiring specialized equipment and trained staff. CROs invest in validated platforms to broaden service catalogs and attract clients seeking non-animal data for filings. Partnerships with chip developers allow them to install systems across multiple sites, and standardization of protocols supports scale. Academic and research institutes remain an important base, supported by public funding for human-relevant research methods. Competition among providers is encouraging faster turnaround and lower pricing for clients.
⮞In April 2025, the contract research organization Pharmaron agreed to validate and install organ-on-a-chip platforms at its sites worldwide.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.00% |
|
Europe |
Germany |
24.57% |
|
Asia Pacific |
China |
36.18% |
|
Latin America |
Brazil |
44.73% |
|
Middle East & Africa |
United Arab Emirates |
38.42% |
North America Organ on a Chip Market Insights
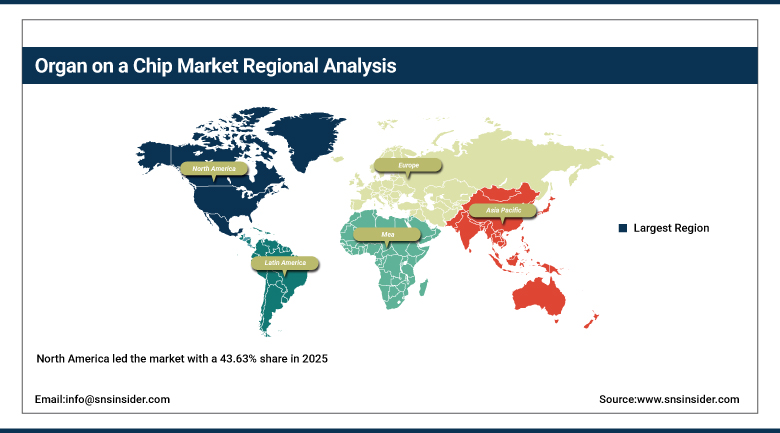
North America led the market with a 43.63% share in 2025, supported by academic research strength, venture capital, and the regulatory signals that favor human-relevant models. The United States generates most regional demand, while Canada contributes through research hospitals and university spinouts. Large pharmaceutical companies headquartered in the region sponsor collaborations with chip developers, and contract research organizations are investing in platforms to serve both local and global clients. Early adoption by regional pharmaceutical groups creates a strong reference base for newer entrants.
Policy support is a defining theme. Federal agencies have announced roadmaps to reduce animal testing, and funding programs are building validation networks and shared datasets. Legislation to update drug development rules has passed in each chamber of Congress in different forms, though final enactment is pending. Vendors are pursuing formal qualification for defined contexts of use, which could convert interest into standard practice. Mexico is counted within Latin America in this report. Advocacy groups and professional societies are also pressing for faster adoption of validated alternatives.
⮞In March 2026, the National Institutes of Health announced more than USD 150 million in first awards to support human-based research that reduces the use of animal models, including a validation network.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Organ on a Chip Market Insights
Europe ranks second, with the Netherlands, Germany, the United Kingdom, Switzerland, and France hosting many of the leading technology developers. Strong public research funding, ethical pressure on animal use, and regulatory interest in new approach methods support adoption. Regional companies have formed industry alliances to promote standards and share best practices, and large pharmaceutical groups headquartered in Europe work closely with these developers on custom models and qualification projects. Local startups also benefit from national innovation grants and access to hospital partners for validation studies.
The European Commission has published a roadmap for phasing out animal testing in chemical safety assessments, which signals a long-term policy shift that favors organ chips and related tools. Funding programs back consortia that develop multi-organ systems. Cosmetics and chemical industries, already prohibited from certain animal tests, are additional users. Competition among regional manufacturers is strong, and acquisitions by larger instrument makers are consolidating the supplier base. Training programs for scientists and regulators are being developed to support wider adoption of the new methods across member states.
⮞In June 2026, the European Commission published a roadmap to phase out animal testing in chemical safety assessments, covering 15 domains and more than 30 opportunities.
Asia Pacific Organ on a Chip Market Insights
Asia Pacific is the fastest growing region with an expected CAGR of 31.45% from 2026 to 2035, led by China, Japan, South Korea, India, and Australia. Government investment in biotechnology, growing contract research sectors, and regulators reviewing alternatives to animal testing are widening adoption. Local companies are developing chips tailored to regional research needs, and global vendors are opening offices and partnering with distributors and universities to build awareness and train users. Growing biopharma investment in Singapore and South Korea adds further momentum.
China has begun consultation on initiatives that promote new approach methods in drug evaluation, and Japan has issued guidelines that accept non-animal data in certain applications. South Korea is considering legislation that would establish a validation center for animal-alternative methods. Cost-sensitive buyers favor local production, so partnerships and local manufacturing are important strategies. Clear regulatory pathways will determine how quickly the region closes the gap with North America. Academic medical centers in the region are building core facilities to support studies and training for researchers.
⮞In July 2026, China's Center for Drug Evaluation opened a consultation on a program to promote the replacement of animal testing with new approach methods.
MEA & Latin America Organ on a Chip Market Insights
Latin America is an emerging market in which animal-testing bans in cosmetics are creating demand for alternative methods. Mexico is counted within this region in market estimates and has prohibited animal testing in cosmetics, while Brazil has enacted a similar law with a phased implementation period. Research universities and contract laboratories in both countries are evaluating human-relevant models, though budgets are limited and most systems are imported from North America and Europe. Regional collaborations with European and North American universities are helping scientists gain hands-on experience.
The Middle East and Africa region is led by the Gulf states, where governments are investing in advanced health technology and regulators are exploring new methods for drug assessment. Research institutions in South Africa and Egypt are building capabilities, though funding remains limited. Adoption depends on training, supply chains for consumables, and collaboration with international developers. Growth is expected from a small base as public institutions demonstrate value and attract private partners. Free zones and research parks offer a platform for international vendors to establish regional hubs.
Market Dynamics
Growth Drivers: Regulatory Momentum and High Drug Attrition Drive Growth in the Organ on a Chip Market
Regulatory momentum is the strongest driver. Agencies in the United States, Europe, and Asia are publishing roadmaps and guidance that encourage non-animal data, and legislation is moving through legislatures. These signals give pharmaceutical companies confidence to invest in platforms and prepare qualification packages. Public funding programs are reinforcing the trend by paying for validation studies, shared datasets, and training that reduce barriers for new users and for smaller vendors. Industry consortia further contribute by publishing performance benchmarks, and these shared standards reduce uncertainty about how results will be judged by reviewers, helping sponsors justify budgets for adoption across several therapeutic areas.
High attrition in drug development is a second driver. Many candidates that look safe in animals fail in human trials, wasting years of work and substantial capital. Organ chips offer human-relevant readouts for toxicity and efficacy earlier in the process. As more validation data emerge and technology improves in reproducibility and throughput, sponsors are expected to move chips from exploratory use into routine decision making across pipelines. Investors in biotechnology also reward companies that present human-relevant data, since such evidence signals lower translational risk and supports financing for programs that would otherwise struggle to attract capital in a cautious market.
⮞In December 2025, the U.S. Senate passed S.355, the FDA Modernization Act 3.0, which would update drug development rules to reflect non-animal testing methods.
Restraints: Standardization Gaps and High System Costs Restrain Growth in the Organ on a Chip Market
Standardization gaps limit adoption. Regulators expect chips to be qualified for a defined context of use, with reproducibility across independent laboratories and agreed protocols, and these requirements take years to meet. Differences in cell sources, device materials, and assay design make cross-study comparisons difficult. Sponsors may hesitate to replace established animal studies until qualification precedents are clear, which slows the shift from pilot projects to routine regulatory submissions. Qualification dossiers require extensive experimental data and sustained collaboration with regulators, and few vendors have the resources to complete the process, which concentrates early progress among a handful of well-funded developers.
Cost and complexity add friction. Instruments, specialized consumables, and trained personnel make initial investment significant, and throughput is lower than conventional plate-based assays. Smaller laboratories may find it difficult to justify the expense. Sourcing consistent primary cells or stem cell-derived tissues is challenging, and device materials such as PDMS can absorb small molecules and distort results. Vendors are working on alternatives, but improvement takes time. Training users in microfluidic handling is another hurdle, since inconsistent technique can introduce variability, and many organizations lack staff with the necessary mix of cell biology and engineering expertise to operate systems reliably.
⮞The FDA draft guidance on streamlined nonclinical safety studies for oncology biologics and conjugated products, dated May 2026, remained in draft form as of 29 May 2026.
Opportunities: Neurology Models and Multi-Organ Platforms Create Opportunities in the Organ on a Chip Market
Neurology presents a large opportunity because central nervous system candidates fail at exceptionally high rates and animal models translate poorly. Brain chips that recreate the blood-brain barrier and neural circuits could improve selection of candidates for Alzheimer's disease, Parkinson's disease, and psychiatric conditions. Vendors that partner with stem cell suppliers and neuroscience groups can develop validated models and attract premium pricing from sponsors seeking better early signals. Pharmaceutical companies have signaled willingness to pay for models that cut late-stage failure, particularly in neurodegeneration where unmet need is large and development timelines are long, and early partnerships between chip developers and neuroscience teams are already forming.
The multi-organ and personalized systems provide additional opportunities for growth. Integration of the liver, kidney, heart, and gut tissue models enables testing of pharmacokinetics and off-target effects in one integrated system. Patient-specific cells may be employed to identify how each individual would react to certain medication, contributing to the development of precision medicine and stratification in clinical trials. Combining the technology with artificial intelligence and automation will increase its throughput potential, and these capabilities will be appealing for investment by instrumentation vendors and CROs. The ability to lease validated systems on an ongoing basis will reduce the initial barrier of entry for customers, providing a stable cash flow for vendors to develop further innovations and expand geographically.
⮞Emulate stated in November 2025 that central nervous system drug candidates fail at a rate above 99%, and launched its Brain-Chip R1 with FUJIFILM Cellular Dynamics to address that gap.
Recent Developments:
- In August 2026, Bruker announced a majority investment in MIMETAS, a Leiden-based developer of the OrganoPlate platform. Financial terms were not disclosed, and the transaction links an instrumentation leader with a specialist in organ-on-chip technology. The combination is expected to broaden distribution of organ-on-chip tools through established instrument channels. Bruker plans to integrate the platform with its imaging systems.
- In June 2026, Xellar Biosystems raised USD 50 million in a Series A financing to build a platform that combines three-dimensional human tissue models with artificial intelligence for drug development. The capital will support laboratory expansion and the hiring of engineers and biologists. The company is based in Boston.
- In May 2026, InSphero acquired PhenoVista Biosciences, adding imaging and assay development expertise to its three-dimensional tissue model portfolio. The company had earlier launched its 3D InSight DIGIT platform in April 2026. The acquisition strengthens the company's capabilities in high-content image analysis for toxicology and efficacy screening. The deal broadens its service offering for pharmaceutical customers.
- In October 2026, Hesperos received an NIH National Institute of Allergy and Infectious Diseases Phase II grant to develop a Malaria-on-a-Chip model, extending its Human-on-a-Chip platform into infectious disease research. The project builds on the company's earlier work on multi-organ systems for drug testing. The work will examine antimalarial drug safety and efficacy in human tissue models.
Organ on a Chip Market Key Players are:
- Emulate
- MIMETAS
- CN Bio
- InSphero
- AlveoliX
- Hesperos
- BiomimX
- TissUse
- Dynamic42
- NETRI
- React4Life
- Xellar Biosystems
Organ on a Chip Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 186.55 Million |
| Market Size by 2035 | USD 1.78 Billion |
| CAGR | CAGR of 25.33% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Offering (Products and Services) • By Organ Type (Lung, Liver, Heart, Kidney, and Others) • By Application (Drug Discovery, Toxicology Research, and Disease Modeling) • By End User (Pharma and Biotech Companies, CROs, and Academic and Research Institutes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Emulate, MIMETAS, CN Bio, InSphero, AlveoliX, Hesperos, BiomimX, TissUse, Dynamic42, NETRI, React4Life, Xellar Biosystems |

Frequently Asked Questions
Key players in the market include Emulate, MIMETAS, CN Bio, InSphero, AlveoliX, and Hesperos, among others.
Key opportunities include neurology models for central nervous system drug testing and multi-organ and personalized platforms.
Regulatory momentum toward non-animal methods and high drug attrition are the major growth factors, as they push developers toward human-relevant predictive models.
The Products segment dominated the market in 2025 with approximately 54.20% share, since every study begins with chips, instruments, and consumables.
North America dominated the market in 2025 with approximately 43.63% share, supported by academic research strength, venture capital, and regulatory signals favoring human-relevant models.
