
Guidewires Market Report Scope & Overview:
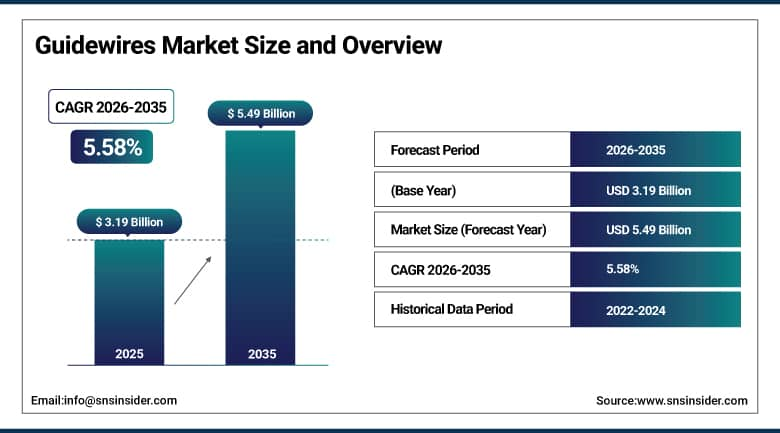
The Guidewires Market was valued at USD 3.19 Billion in 2025 and is expected to reach USD 5.49 Billion by 2035, growing at a CAGR of 5.58% from 2026 to 2035.
The Guidewires Market is witnessing constant growth due to rising aging population, increasing prevalence of cardiovascular diseases and peripheral vascular diseases, and increasing use of minimally invasive surgery. In interventional medicine, the guidewire serves as the guide for other devices to reach their position, and accurate access becomes the objective for which guidewire technology strives. The increasing number of percutaneous coronary intervention, endovascular treatment, and neurovascular procedures further drive the demand for guidewires in applications of cardiology, radiology, and neurosurgery. Apart from that, positive reimbursement scenario in developed nations, innovations in coating and core technologies, and improving healthcare facilities in developing nations are also responsible for this trend.
In February 2025, Asahi Intecc Co., Ltd. announced the launch of its ASAHI Miracle Neo 3 guidewire, featuring a blunt tip designed to enhance safety and vessel protection while improving precision in complex coronary interventions.
To Get More Information On Guidewires Market - Request Free Sample Report
Guidewires Market Trends:
-
Growing adoption of hydrophilic coatings and variable stiffness designs is improving torque response for chronic total occlusion crossing in complex coronary interventions.
-
Rising development of bioresorbable and smart guidewires offering real-time procedural data is emerging as a key area of manufacturer research investment.
-
Expanding use of neurovascular guidewires in mechanical thrombectomy procedures is broadening the category’s applications beyond traditional cardiology use.
-
Increasing integration of AI-enabled navigation and augmented reality is expected to reduce fluoroscopy use, leading to safer, faster procedures.
-
Growing interest in customized 3D-printed guidewires tailored for unique patient anatomies is opening new avenues for personalized interventional care.
U.S. Guidewires Market Outlook:
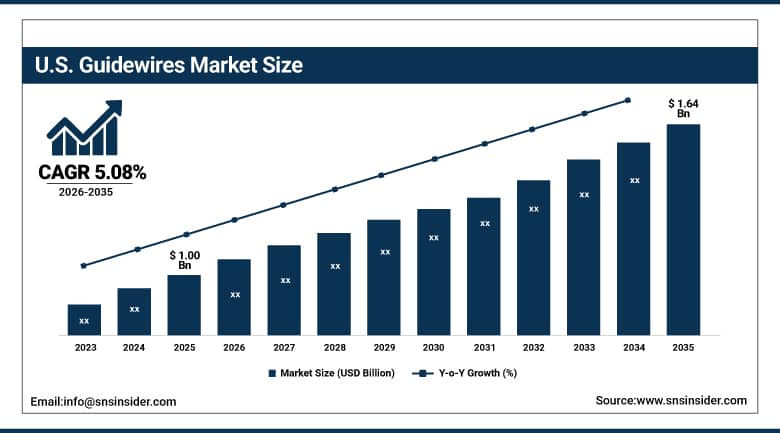
The U.S. Guidewires Market was valued at approximately USD 1.00 Billion in 2025 and is projected to reach USD 1.64 Billion by 2035, growing at a CAGR of 5.08% during 2026–2035.
The U.S. Guidewires Market is expanding at a steady pace because of the high volumes of percutaneous coronary intervention performed globally, the developed healthcare system, and reimbursement policies. The increased cases of urological conditions, cardiovascular conditions, and peripheral artery disease are significantly increasing the demand for the products. Increased cases of minimally invasive surgery and the geriatric population create continuous demand for the products. Innovations in the industry, like real-time deflectable neurovascular guidewires, which permit the physician to control the distal end of the product, are influencing the customer choice.
In June 2025, the U.S. Food & Drug Administration cleared a new ultra-slim hydrophilic coating guidewire from Terumo Corporation, designed for crossing chronic total occlusions in complex coronary interventions with enhanced maneuverability and precision.
Guidewires Market Segment Analysis:
-
By Product Type, Coronary Guidewires segment dominated the Guidewires Market in 2025 with 43.19% share; Neurovascular Guidewires segment is the fastest-growing segment.
-
By Material, Stainless Steel segment dominated the market in 2025 with 50% share; Nitinol segment is the fastest-growing segment.
-
By Application, Cardiology segment dominated the market in 2025 with 45% share; Neurology segment is the fastest-growing segment.
-
By End User, Hospitals segment dominated the market in 2025 with 65% share; Ambulatory Surgical Centers segment is the fastest-growing segment.
By Product Type, Coronary Guidewires Dominates the Guidewires Market While Neurovascular Guidewires Register the Fastest Growth
Coronary Guidewires dominates the Guidewires Market, accounting for 43.19% of revenue in 2025, owing to the sustained high volume of percutaneous coronary intervention and structural heart procedures performed worldwide for cardiovascular disease treatment. Coronary guidewires benefit from decades of engineering refinement in torque transmission, tip flexibility, and coating technology that support reliable navigation through tortuous coronary anatomy. The high procedural volume and established clinical protocols for coronary intervention are reinforcing this segment’s continued market leadership.
Neurovascular Guidewires is experiencing the fastest growth driven by increasing mechanical thrombectomy and neurointerventional procedures addressing stroke and other cerebrovascular conditions. Rising clinical adoption of minimally invasive approaches for treating complex neurovascular conditions is compelling manufacturers to expand specialized, deflectable guidewire offerings capable of navigating the brain’s intricate arterial network. Growing regulatory clearances for real-time steerable neurovascular devices are opening up substantial opportunities for commercial utilization in this segment.
By Material, Stainless Steel Dominates the Guidewires Market While Nitinol Registers the Fastest Growth
Stainless Steel dominates the Guidewires Market due to its cost efficiency, proven durability, and long-established position as the foundational material for guidewire cores across a broad range of interventional applications. Stainless steel guidewires benefit from extensive manufacturing infrastructure and decades of clinical use establishing reliable performance characteristics. The cost efficiency and established manufacturing base for stainless steel guidewires are reinforcing this segment’s continued market leadership.
Nitinol is experiencing rapid growth driven by its superior flexibility, kink resistance, and biocompatibility compared to traditional stainless steel, characteristics that reduce complications during procedures and enhance clinical outcomes. Rising adoption of hybrid guidewire designs combining nitinol’s shape memory properties with stainless steel’s support characteristics is compelling manufacturers to expand nitinol-based product lines. Growing demand for guidewires capable of navigating increasingly complex and tortuous vasculature is opening up substantial opportunities for commercial utilization in this segment.
By Application, Cardiology Dominates the Guidewires Market While Neurology Experiences the Fastest Growth
Cardiology dominates the Guidewires Market due to sustained high procedural volumes across coronary intervention, structural heart procedures, percutaneous coronary intervention, and transcatheter aortic valve replacement that rely fundamentally on guidewire navigation. Cardiology applications benefit from well-established clinical protocols and reimbursement pathways supporting continued procedural growth. The high procedural volume and established clinical infrastructure for cardiology applications are reinforcing this segment’s continued market leadership.
Neurology is growing rapidly on account of increasing mechanical thrombectomy and neurointerventional procedure volumes addressing stroke treatment and other cerebrovascular conditions. Rising clinical evidence supporting minimally invasive neurovascular intervention over traditional surgical approaches is compelling healthcare systems to expand neurointerventional program capacity. Advances in specialized neurovascular guidewire design enabling safer navigation of delicate cerebral vasculature are opening up substantial opportunities for commercial utilization in this segment.
By End User, Hospitals Dominates the Guidewires Market While Ambulatory Surgical Centers Register the Fastest Growth
Hospitals dominates the Guidewires Market because they perform most complex cardiovascular, neurovascular, and peripheral interventions requiring comprehensive support infrastructure and specialized interventional teams. Hospital-based catheterization laboratories and interventional suites benefit from established relationships with device manufacturers and comprehensive procedural capabilities. The comprehensive procedural capability and established infrastructure at hospitals are reinforcing this segment’s continued market leadership.
Ambulatory Surgical Centers are expanding rapidly as selected minimally invasive procedures shift toward outpatient settings, driven by cost efficiency and patient preference for reduced hospital stays. Rising confidence in performing appropriate interventional procedures outside traditional hospital settings is compelling ambulatory centers to expand their interventional capabilities. The increased shift of appropriate minimally invasive procedures to outpatient settings is facilitating the growth of this segment.
Regional Analysis:
|
Region |
Country |
Share (2025) |
|
North America |
United States |
84.20% |
|
Europe |
Germany |
21.60% |
|
Asia Pacific |
China |
33.20% |
|
Middle East & Africa |
UAE |
17.30% |
|
Latin America |
Brazil |
23.60% |
North America Guidewires Market Insights
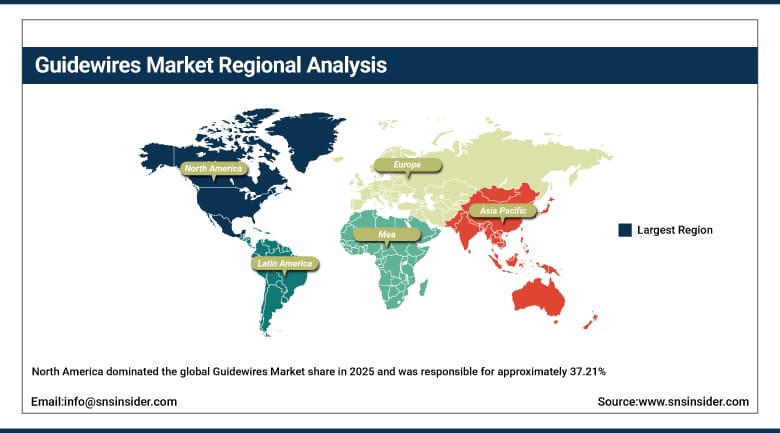
North America dominated the global Guidewires Market share in 2025 and was responsible for approximately 37.21% of global revenue due to high percutaneous coronary intervention procedure volume in the U.S., advanced healthcare infrastructure, and favorable reimbursement for interventional procedures in the country. North America is the headquarter of major guidewires producers like Boston Scientific, Abbott, and Teleflex, which is facilitating innovation in product range. Cardiovascular and neurovascular diseases are becoming increasingly common in the region, thus further driving demand for the product. Infrastructure of hospitals and ASCs across the United States and Canada is also enhancing the availability of products in the region.
The United States accounted for approximately 84.20% of the North American market in 2025 due to its dominance as a leading manufacturer of devices and highest interventional procedures in the world. Canada is helping in regional growth through sustained demand for cardiovascular and peripheral vascular interventions.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Guidewires Market Insights
The Guidewires Market in the Asia Pacific region is projected to show the highest CAGR over the forecast period 2026-2035 due to increased healthcare spending, improved healthcare infrastructure and growing number of patients that require cardiovascular and neurovascular interventions. Countries like China, Japan and India have shown rapid growth due to increasing numbers of middle-class people using advanced interventional cardiology and neurology procedures. Increased product innovation and increased consumer awareness about the minimally invasive procedures is also driving the market growth. The growing demand for high-quality guidewires products is increasing the Asia Pacific growth rate above other markets.
China holds around 33.20% share of the Asia Pacific market in 2025, which can be attributed to its improving healthcare infrastructure and increased demand for interventional cardiology procedures. India and Japan are also contributing significantly to market growth in the region, with Japan having a well-established medical device manufacturing industry.
Europe Guidewires Market Insights
In 2025, Europe was responsible for a considerable share in the Guidewires Market owing to their established healthcare system and use of minimally invasive interventional techniques in major member countries. The increasing demands for coronary and neurovascular guidewires in Germany, France, and the United Kingdom is driving product innovations. The increasing convergence with respect to regulation as per EU Medical Device Regulation and an increase in clinical trial evidence are adding strength to the market presence of Europe.
Germany emerged as the market leader in Europe with a regional share of 21.60% in 2025 due to its robust healthcare framework and established interventional cardiology practices. France and the United Kingdom are also making a considerable contribution to regional growth owing to the presence of leading medical device companies in the region.
Middle East & Africa and Latin America Guidewires Market Insights
Growth within the Middle East & Africa region is being witnessed as a result of the development in the healthcare infrastructure within the Gulf countries, as well as investments in cardiovascular and interventional facilities. The Latin American region too is gaining from the expansion of healthcare infrastructure and increasing consumer preference for minimally invasive treatments within the region.
UAE emerged as the leading player in the Middle East & Africa region in 2025, accounting for 17.30% of the regional market share, owing to investments in healthcare infrastructure and interventional cardiology facilities. Brazil accounted for 23.60% of the Latin American market in 2025 on account of the growth in cardiovascular interventions, while Mexico too contributed to regional growth.
Market Dynamics:
Growth Drivers: Rising Cardiovascular Disease Prevalence and Minimally Invasive Procedure Adoption Driving Market Growth
The primary drivers supporting the growth of the guidewires market are the expanding geriatric population base, increased occurrence of lifestyle disorders, and prevalence of heart conditions needing interventions. With the increasing trend of minimally invasive vascular and endoluminal surgeries taking place of conventional surgical methods, there is a growing realization among health care providers regarding the potential of sustained growth for guidewires, thereby resulting in the expansion of the global guidewires market.
An expanding volume of PCI procedures and advancements in advanced coronary, peripheral, and neurovascular guidewires have led to the expansion of applications within this category. Innovations in hydrophilic coating, nitinol cores, and variable stiffness guidewires are driving product development trends within the guidewires market.
Restraints: Procedural Complications and Regulatory Compliance Challenges Limiting Market Expansion
Despite favorable demand, the category faces restraints associated with procedural complications, including vessel injury or wire perforation, that can occur during complex interventional cases and affect clinical adoption confidence. Regulatory variations across regions regarding medical device approval pathways and clinical evidence requirements continue to influence market entry timelines for new guidewire technologies. Time-consuming exchanges required during multi-lesion cases can complicate procedures and affect procedural efficiency in complex clinical scenarios.
High costs associated with clinical validation, regulatory submission, and quality certification also contribute to elevated development expenses, limiting speed to market for smaller manufacturers. Furthermore, increasing competition among established Tier 1 manufacturers and emerging specialized device companies is intensifying pricing pressure. As the category matures, manufacturers must balance procedural safety, regulatory compliance, and cost efficiency to maintain clinical trust and support sustained expansion across cardiology and neurology applications.
Opportunities: Smart Guidewire Technology and Emerging Market Expansion Creating New Growth Avenues
There are several significant areas for the innovative product development in the guidewires market, which include the development of smart guidewire technology, implementation of AI-powered navigation systems and expansion of business in emerging markets. The development of guidewires that provide the operators with the information regarding the procedure being done will help to satisfy the demand related to the need for more precise interventions and better decision-making support during procedures. The implementation of technologies aimed at reducing radiation exposure, including optical guidewires and augmented reality navigation systems, is another area where there is demand from clinicians.
The innovation that includes the development of customized 3D printed guidewires will help to differentiate products by making them unique in terms of the specific anatomy of the patient. Collaborations between well-known manufacturers, which will help to leverage their complementary capabilities and increase efficiency, is another opportunity for accelerating the process of innovation. Bioresorbable guidewire material development is another innovative area that will help companies to increase differentiation in particular clinical cases.
Recent Developments:
-
February 2025: Asahi Intecc Co., Ltd. launched its ASAHI Miracle Neo 3 guidewire, featuring a blunt tip for improved vessel protection in complex coronary interventions.
-
June 2025: The U.S. FDA cleared a new ultra-slim hydrophilic coating guidewire from Terumo Corporation for crossing chronic total occlusions.
-
July 2026: Rapid Medical announced FDA clearance of its Drivewire 35 steerable guidewire for stroke and other intravascular procedures.
-
July 2026: Imperative Care launched its Ikon 24 Pro guidewire, a neurovascular guidewire purpose-built for stroke procedures.
Guidewires Market key players are:
-
Boston Scientific Corporation
-
Medtronic plc
-
Terumo Corporation
-
Abbott Laboratories
-
Cook Medical
-
ASAHI INTECC Co., Ltd.
-
B. Braun Melsungen AG
-
Teleflex Incorporated
-
Stryker Corporation
-
Cardinal Health, Inc.
-
Merit Medical Systems, Inc.
-
Olympus Corporation
-
Becton, Dickinson and Company (BD)
-
AngioDynamics, Inc.
-
Johnson & Johnson
-
Integer Holdings Corporation
-
ConMed Corporation
-
Biotronik SE & Co. KG
-
Nipro Corporation
-
MicroPort Scientific Corporation
Guidewires Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.19 Billion |
| Market Size by 2035 | USD 5.49 Billion |
| CAGR | CAGR of 5.58% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Coronary Guidewires, Peripheral Guidewires, Neurovascular Guidewires, Others) • By Material (Stainless Steel, Nitinol, Polymer) • By Application (Cardiology, Neurology, Others) • By End User (Hospitals, Ambulatory Surgical Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Boston Scientific Corporation, Medtronic plc, Terumo Corporation, Abbott Laboratories, Cook Medical, ASAHI INTECC Co., Ltd., B. Braun Melsungen AG, Teleflex Incorporated, Stryker Corporation, Cardinal Health, Inc., Merit Medical Systems, Inc., Olympus Corporation, Becton, Dickinson and Company (BD), AngioDynamics, Inc., Johnson & Johnson, Integer Holdings Corporation, ConMed Corporation, Biotronik SE & Co. KG, Nipro Corporation, MicroPort Scientific Corporation. |
Frequently Asked Questions
Key players include Boston Scientific Corporation, Abbott Laboratories, Medtronic plc, Terumo Corporation, and Cook Medical LLC, among others.
Key opportunities include smart guidewire technology with real-time procedural data, AI-enabled navigation and augmented reality systems, expansion into emerging markets, customized 3D-printed guidewires, and bioresorbable material development.
The market is driven by the growing geriatric population base, increasing number of lifestyle disorders, and rising prevalence of cardiovascular diseases.
The Coronary Guidewires segment dominated the Guidewires Market in 2025, accounting for 43.190% of revenue share.
The North America region dominated the Guidewires Market in 2025, accounting for approximately 37.21% of global market share, driven by the United States’ high procedural volumes and favorable reimbursement policies.
