
Packaging Material Market Report Scope & Overview:
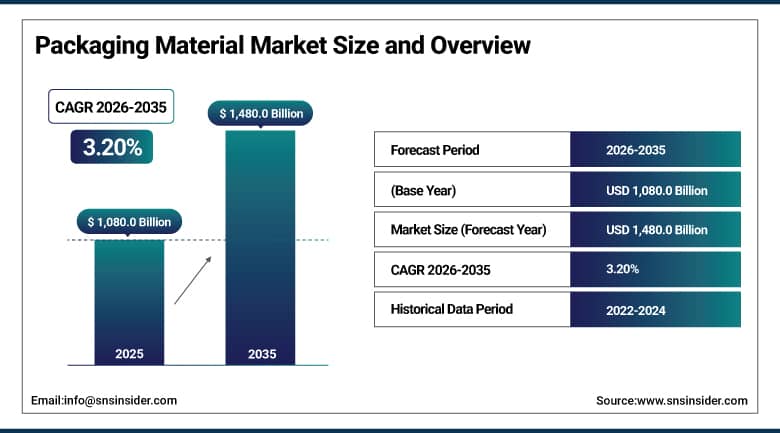
The Packaging Material Market was valued at USD 1,080.0 Billion in 2025 and is expected to reach USD 1,480.0 Brillion by 2035, growing at a CAGR of 3.20% from 2026 to 2035.
The packaging material market is witnessing significant growth due to the importance of packaging materials in the protection of goods in terms of transportation, storage, and marketing. The packaging material consists of paper, rigid and flexible plastic, glass, metal, and bio-materials that are used in various forms like bottles, boxes, jars, and films in food and beverages, household, personal care, and industry segments globally. In addition to this, the growth of the market is also being boosted due to increasing urbanization and industrialization in the developing countries requiring new packaging options and increasing last-mile logistics efficiency and sustainable packaging material due to regulatory and consumer trends.
As per PMMI, the Association for Packaging and Processing Technologies, the packaging industry sold a total market size of 1,431.5 billion units, with the Asia Pacific region representing a significant player expected to reach 1,724 billion units, reflecting the substantial scale of global packaging material demand supporting increasingly diverse consumer and industrial applications worldwide.
To Get More Information On Packaging Material Market - Request Free Sample Report
Packaging Material Market Trends
- Rising availability of low-cost supplies needed for financially viable packaging solutions continues to drive market growth in Asia Pacific, particularly across rapidly industrializing economies.
- Growing higher plastic consumption across numerous industries continues to promote the fastest market growth in Asia Pacific, driven by rising urbanization and industrialization in developing countries.
- Increasing proliferation of global e-commerce and last-mile logistics efficiency is driving strong demand for protective, durable packaging materials supporting increasingly complex distribution networks.
- Expanding shift toward sustainable packaging materials prompted by regulatory changes and consumer preferences is reshaping material selection across the broader packaging industry.
- Strategic partnerships among packaging material manufacturers, brand owners, and logistics providers are supporting development of increasingly diverse, sustainable packaging material portfolios.
The U.S. Packaging Material Market Outlook
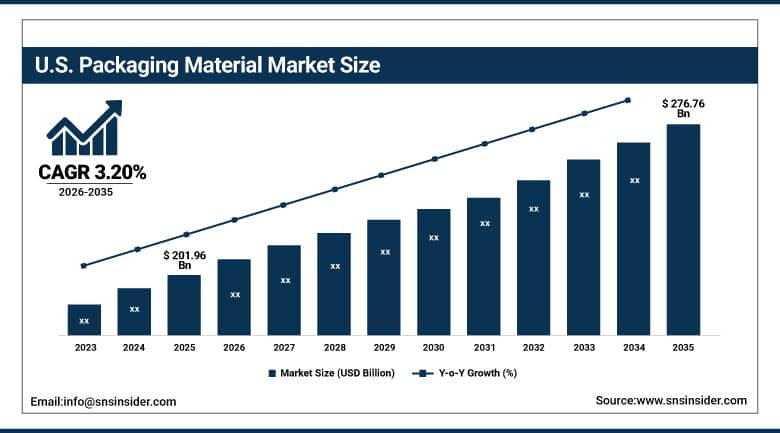
The U.S. packaging material market was valued at USD 201.96 Billion in 2025 and is projected to reach USD 276.76 Billion by 2035, growing at a CAGR of 3.20% during 2026–2035.
Manufacturers of the country's top packaging materials keep on increasing production capacities, as the result of innovations associated with the recycling and reuse of these materials in order to lower the impact of these processes on the environment. The increase in demand for innovative packaging products keeps on fueling the demand for packaging materials in the country's food, beverage, and other product manufacturing sectors.
In June 2025, Amcor announced an investment in its Nicholasville, Kentucky facility to expand PCR packaging capabilities, supporting production of packaging with high recycled content. This is an important investment that will enhance the U.S.’s capability to produce sustainable packaging materials in response to rising demand for these circular and low-carbon alternatives.
Packaging Material Market Segment Analysis
- By Material, paper dominated the packaging material market with a 34.60% share in 2025, while rigid plastic is the fastest-growing material segment with a CAGR of 4.80% from 2026–2035.
- By Product, bottles dominated the packaging material market with a 28.60% share in 2025, while box is the fastest-growing product segment with a CAGR of 5.20% from 2026–2035.
- By End-User, food & beverages dominated the packaging material market with a 42.60% share in 2025, while household products is the fastest-growing end-user segment with a CAGR of 5.60% from 2026–2035.
By Material, paper dominated the packaging material market, while rigid plastic is the fastest-growing segment.
In terms of material, the paper segment was leading in the world market during 2025. The paper segment continues to hold dominance within the material segments due to its sustainability reputation and wide applicability for boxes, cartons, and wrapping, making it the ideal material selection option in eco-friendly food and beverages, e-commerce, and personal care packages.
By material, the rigid plastic segment is expected to expand rapidly in the market with a strong CAGR of 4.80% in the coming years. Growing demand for durable, protective packaging supporting e-commerce and last-mile logistics is driving rising rigid plastic segment growth, as manufacturers increasingly develop recyclable rigid plastic formulations meeting evolving sustainability requirements.
By Product, bottles dominated the packaging material market, while box is the fastest-growing segment.
By product, the bottles segment registered its dominance over the global market in 2025. Bottles remain the dominant product category owing to their broad applicability across beverage, personal care, and household product packaging, representing the most widely produced and commercially established packaging format across the global packaging industry worldwide.
By product, the box segment is expected to witness the fastest growth in the market with a CAGR of 5.20% over the forecast period. Growing e-commerce and last-mile logistics demand for protective, stackable packaging formats is driving rising box segment growth, as manufacturers increasingly develop lightweight, durable corrugated and rigid box solutions supporting expanding online retail distribution.
By End-User, food & beverages dominated the packaging material market, while household products is the fastest-growing segment.
Based on end-user, the food and beverages sector accounted for the largest share of the global market in 2025. The food and beverages category continues to be the dominant end-user application because of the critical function of packaging materials in keeping the items fresh, maintaining their safety and offering extended shelf life, constituting the biggest and most mature application segment leading to the overall consumption of packaging materials globally.
Based on end-user, the household products sector will hold the largest market share with the highest CAGR of 5.60% from 2026 to 2035. Increasing consumer preference for packaging materials that facilitate the packaging of household cleaning, personal care, and consumer goods products is fueling the growth of the segment.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
Asia Pacific Packaging Material Market Insights
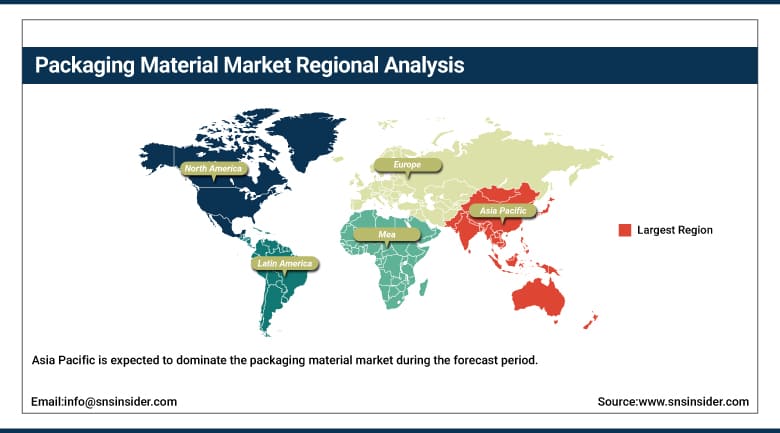
Asia Pacific is expected to dominate the packaging material market during the forecast period. The fastest market growth in Asia Pacific is promoted by the higher plastic consumption in numerous industries, alongside rising urbanization and industrialization in developing countries.
China is the Asia Pacific region's largest market for packaging solutions, which is followed by Japan, India, and South Korea. The availability of low-cost supplies needed for financially viable packaging solutions continues to drive market growth in Asia Pacific, supported by expanding domestic manufacturing infrastructure across the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Packaging Material Market Insights
North America is expected to register the fastest CAGR in the packaging material market during the forecast period, supported by increasing investments in sustainable packaging, material recycling, and reuse initiatives aimed at reducing carbon footprints. The United States was the leading player in the North America packaging material market in 2025 because of the growing demand for innovative, recyclable, lightweight, and versatile packaging materials within various industries including food and beverages, healthcare, and consumer goods.
The use of recycled material along with circular packaging is encouraging manufacturers to increase their capabilities regarding sustainable materials. On the other hand, Canada is playing its part in the development of the regional market due to its increasing production capacity of sustainable packaging and growing demand for eco-friendly packaging materials.
Europe Packaging Material Market Insights
The Europe packaging material market was a major contributor in 2025. This is attributed to the region's strong sustainability regulations and growing consumer demand for eco-friendly, recyclable packaging materials across member states.
Germany is one of the major markets in Europe owing to its strong packaging manufacturing base and growing consumer demand for sustainable, recyclable packaging solutions. Other countries such as France and the United Kingdom are also contributing to market growth through extensive food and beverage packaging manufacturing capacity.
Middle East & Africa and Latin America Packaging Material Market Insights
Middle East & Africa and Latin American regions are gradually expanding packaging material market participation as consumer goods and food processing manufacturing investment grows across both regions.
Brazil is set to be a prominent Latin American market fueled by growing domestic food and beverage manufacturing capacity. The Middle East & Africa region has UAE and Saudi Arabia investing in modern manufacturing infrastructure that is expanding access to diverse packaging material categories across their growing consumer goods sectors.
Growth Drivers: Rising urbanization and e-commerce expansion driving market growth
High rates of urbanization, rising middle-class consumption, especially in Asia Pacific, and a strong shift toward sustainable packaging materials prompted by regulatory changes and consumer preferences are primarily driving the packaging material market. The increasing trend of global e-commerce and improved efficiency in last-mile logistics operations is expected to drive an increasing demand for durable packaging materials through increasingly intricate supply chains around the world.
Increasing adoption of e-commerce and changing retail distribution channels is also expected to drive demand for more functional and sustainable packaging solutions that can help differentiate brands. Increasing urbanization and industrialization in developing nations, cost-effective sourcing of raw materials to develop sustainable packaging solutions, and improvements in packaging recycling are some other factors driving demand in the forecast period.
Restraints: Raw material price volatility and recycling infrastructure gaps limiting market expansion
One of the main barriers to market growth is fluctuating raw material pricing affecting plastic resin, paper pulp, and metal packaging inputs, which continues to introduce cost uncertainty for packaging manufacturers negotiating long-term supply arrangements with consumer goods brands.
Additionally, limited recycling infrastructure across certain regions continues to complicate end-of-life management for packaging materials, creating tension between functional performance requirements and circular economy sustainability goals. The technical complexity of developing recyclable materials that maintain equivalent protective performance to conventional packaging further requires substantial ongoing research and development investment.
Opportunities: Expansion of sustainable materials and e-commerce packaging innovation creating new growth avenues
The strong shift toward sustainable packaging materials prompted by regulatory changes and consumer preferences represents a substantial market opportunity for manufacturers capable of developing recyclable, biodegradable, and reduced-material packaging solutions addressing evolving environmental compliance requirements.
There is a considerable growth opportunity in the continued expansion of e-commerce-optimized packaging materials supporting last-mile logistics efficiency and protective performance. The expansion of urbanization and rising middle-class consumption in emerging markets across Asia Pacific and Latin America is likely to unlock substantial new demand throughout the forecast period.
Recent Developments
- 2025: Smurfit WestRock expanded its fiber-based packaging production capacity, strengthening its ability to supply growing e-commerce application demand for sustainable, protective packaging solutions.
- 2025: Amcor launched an updated recyclable flexible packaging film for food and beverage brands, offering manufacturers a sustainable alternative meeting growing consumer demand for eco-friendly materials.
- 2026: Ball Corporation expanded its aluminum can manufacturing facility, strengthening its ability to supply growing beverage packaging customer demand for infinitely recyclable metal packaging.
- 2026: Mondi Group launched a new paper-based packaging solution designed to replace single-use plastic applications, targeting consumer goods brands seeking sustainable material alternatives.
Packaging Material Companies are:
- Amcor plc
- Mondi Group
- Berry Global Inc.
- Smurfit Kappa Group plc (Smurfit WestRock)
- Ball Corporation
- Sealed Air Corporation
- International Paper Company
- WestRock Company
- Sonoco Products Company
- Crown Holdings, Inc.
- Tetra Pak International S.A.
- DS Smith Plc
- Stora Enso Oyj
- Packaging Corporation of America
- Greif, Inc.
- Huhtamaki Oyj
- CCL Industries Inc.
- Winpak Ltd.
- Constantia Flexibles Group GmbH
- Veritiv Corporation
Packaging Material Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1,080.0 Billion |
| Market Size by 2035 | USD 1,480.0 Billion |
| CAGR | CAGR of 3.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Paper, Rigid Plastic, Metal, Flexible Plastics, Glass, Wood, Others) • By Product (Bottles, Box, Containers and Jars, Bags and Sacks, Pouches, Closures and Lids, Films and Wraps, Others) • By End-User (Food & Beverages, Household Products, Pharmaceuticals and Healthcare, Personal Care and Cosmetics, Automotive, Electrical and Electronics, Chemicals, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Mondi Group, Berry Global Inc., Smurfit Kappa Group plc (Smurfit WestRock), Ball Corporation, Sealed Air Corporation, International Paper Company, WestRock Company, Sonoco Products Company, Crown Holdings, Inc., Tetra Pak International S.A., DS Smith Plc, Stora Enso Oyj, Packaging Corporation of America, Greif, Inc., Huhtamaki Oyj, CCL Industries Inc., Winpak Ltd., Constantia Flexibles Group GmbH, Veritiv Corporation |
Frequently Asked Questions
Key players include Amcor plc, Mondi Group, Berry Global Inc., Smurfit Kappa Group plc (Smurfit WestRock), and Ball Corporation, among others.
Key opportunities include sustainable packaging adoption, increasing demand for recyclable materials, and expansion of circular packaging and material recycling solutions.
The market is driven by high rates of urbanization, rising middle-class consumption especially in Asia Pacific, and a strong shift toward sustainable packaging materials.
The Paper segment dominated the Packaging Material Market in 2025.
The Asia Pacific region dominated the Packaging Material Market in 2025, valued at USD 281 billion.
