
Cellulose Film Packaging Market Report Scope & Overview:
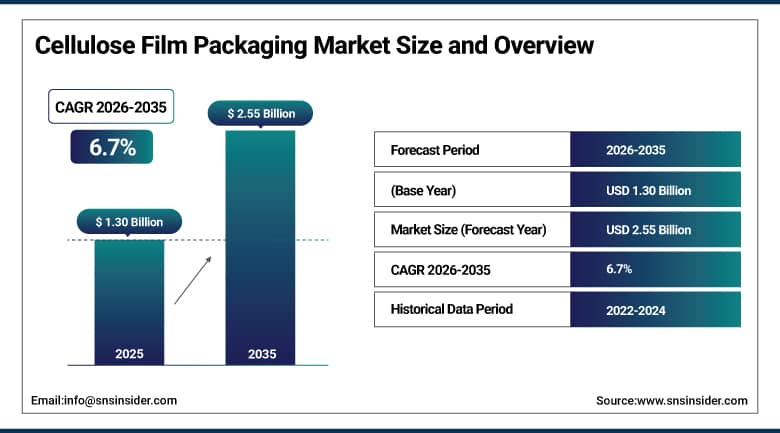
The Cellulose Film Packaging Market was valued at USD 1.30 Billion in 2025 and is expected to reach USD 2.55 Billion by 2035, growing at a CAGR of 6.7% from 2026–2035.
Cellulose film, better known by its original trade name Cellophane, is made by dissolving wood pulp or cotton linters into a viscose solution and casting it into a thin, transparent sheet that's fully biodegradable and, in many formulations, home compostable. It offers the kind of optical clarity and moisture barrier that made it the default candy wrapper and cigarette overwrap for most of the twentieth century, before cheaper petroleum-based plastics displaced it almost everywhere. Rising plastic bans and genuine improvements in coated, functional cellulose film performance are now pulling demand back toward the material its synthetic successors were built to replace.
Futamura, working with flexible packaging converter Repaq and machine builder GK Sondermaschinenbau, launched a fully compostable liquid sachet solution in May 2025 built around the company's NatureFlex cellulose film technology, capable of wrapping ketchup, mustard, cooking sauces, or hand cream. Liquid sachets had been one of the genuinely stubborn problems in compostable packaging, since a barrier film thin enough to form a proper heat seal around a wet, often oily fill tends to be exactly the kind of film that's hardest to make reliably compostable, and it took a three-way collaboration between a film maker, a converter, and a machine builder to actually solve it.
To Get More Information On Cellulose Film Packaging Market - Request Free Sample Report
Cellulose Film Packaging Market Trends
-
Coated cellulose films continue gaining share over uncoated variants, as functional polymer or metallic coatings add moisture resistance, gas barrier performance, and printability that plain cellulose film alone can't provide.
-
Pharmaceutical blister pack lidding is shifting away from PVC and PVDC toward compostable or readily recyclable cellulose-based alternatives, driven by the pharmaceutical industry's own decarbonization commitments.
-
Liquid sachet and pouch packaging, historically one of the hardest applications to convert to compostable materials, is beginning to see genuine commercial cellulose film solutions after years of failed attempts.
-
Regulatory pressure on single-use plastics continues intensifying globally, with government bodies and international agencies citing plastic leakage into aquatic ecosystems as a direct driver of alternative material adoption.
-
Manufacturers are investing in solvent-free production processes that cut manufacturing emissions, addressing environmental concerns that extend beyond the film's end-of-life compostability into its production footprint as well.
U.S. Cellulose Film Packaging Market Outlook
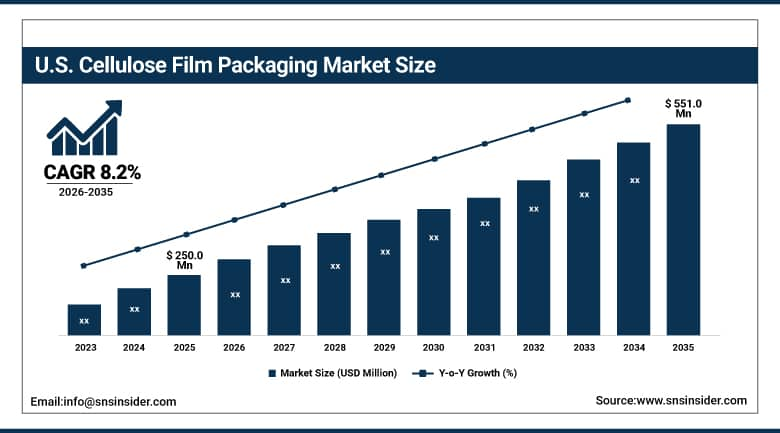
The U.S. Cellulose Film Packaging Market was valued at approximately USD 250.0 Million in 2025 and is expected to reach approximately USD 551.0 Million by 2035, growing at a CAGR of approximately 8.2%.
Demand in the United States is concentrated in premium coated films for food, pharmaceutical, and cosmetics applications, reflecting a market that favors higher-value, functionally engineered cellulose film over the commodity-grade product common in some other regions. Growing state-level plastic packaging restrictions and corporate sustainability commitments from major food and consumer goods brands continue expanding the addressable market for compostable cellulose film alternatives. Domestic production capacity remains limited relative to the country's consumption, keeping American converters and brand owners meaningfully dependent on imported film from established Japanese, European, and Chinese producers.
Eastman Chemical Company, headquartered in Kingsport, Tennessee, is one of the few U.S.-based manufacturers with meaningful cellulose film production capacity, competing directly against the largely Japanese, European, and Chinese-dominated global cellulose film supply base. Futamura also operates a U.S. production site as part of its global NatureFlex and Cellophane manufacturing network, giving American converters and brand owners domestic sourcing options rather than depending entirely on imported cellulose film.
Cellulose Film Packaging Market Segment Analysis
-
By Film Type, the Plain/Cellophane Films segment dominated the Cellulose Film Packaging Market with approximately 54.0% share in 2025, while the Coated Cellulose Films segment is the fastest growing with a CAGR of approximately 7.8%.
-
By Color, the Colorless/Transparent segment dominated the Cellulose Film Packaging Market with approximately 72.5% share in 2025, while the Colored segment is the fastest growing with a CAGR of approximately 7.2%.
-
By Application, the Food & Confectionery segment dominated the Cellulose Film Packaging Market with approximately 38.0% share in 2025, while the Personal Care segment is the fastest growing with a CAGR of approximately 8.4%.
-
By Source, the Wood Pulp segment dominated the Cellulose Film Packaging Market with approximately 78.16% share in 2025, while the Cotton Linters segment is the fastest growing with a CAGR of approximately 6.8%.
By Film Type, plain/cellophane films dominates, coated cellulose films grows fastest
Plain, non-coated cellophane dominated the film-based market segment in 2025 because of its environmental friendly nature, simplicity of production, and affordability compared to other types. Optical clarity and biodegradability of this type of cellulose film without any modification is still considered the first choice in basic packaging requirements like overwraps and candy packaging where no barrier performance is needed.
Coated cellulose film has been witnessing rapid growth since producers have begun applying polymer and metallic coating to it to improve its water resistance, barrier performance, and printability far beyond what the simple cellulose film could provide. Improved functionality has made coated films more suitable for special packaging and labeling applications that before required use of conventional plastic film.
By Color, colorless/transparent dominates, colored grows fastest
Colorless, transparent cellulose film held the large majority of the color segment in 2025, valued for its clear visibility, premium product display quality, and food-contact suitability across transparent wraps, labels, and flexible packaging applications. Brand owners consistently favor transparency for products where visual appeal and shelf presence depend on customers seeing the product itself rather than an opaque wrapper.
Colored cellulose film is growing fastest as brand owners increasingly use tinted and printed film as a genuine design and marketing tool rather than a purely functional wrap. That shift toward using packaging color as active brand differentiation, particularly in confectionery and premium personal care categories, is pulling demand toward colored film formats faster than the broader transparent segment is growing.
By Application, food & confectionery dominates, personal care grows fastest
Food and confectionery held the biggest application share in 2025, owing to the historical presence of cellulose films in the wrappings of candies and other foods, wherein visibility, biodegradability, and food safety are simultaneously required. The increasing usage of biodegradable packaging in food applications is further helping the food and confectionery application maintain its leading position.
Personal care is witnessing the highest rate of growth as more and more cosmetics and personal care manufacturers are using cellulose films for overwrap, labeling, and specialized packaging solutions due to their sustainable positioning. The rising expectations from the consumers regarding sustainable packaging are giving rise to rapid growth in the personal care applications sector.
By Source, wood pulp dominates, cotton linters grows fastest
Wood pulp held the overwhelming majority of the source segment in 2025, remaining the standard raw material for commercial cellulose film production given its cost efficiency and the well-established, FSC-certified forestry supply chains major manufacturers have built around it. Sourcing from fast-growing, sustainably managed forestry operations, such as eucalyptus plantations, keeps wood pulp both the most economical and most readily certified renewable source.
Cotton linters are growing fastest as specialty and premium cellulose film applications increasingly value the particular purity and fiber characteristics cotton-derived cellulose offers over wood pulp alternatives. That premium positioning, along with niche applications where cotton's specific material properties provide a genuine performance advantage, is pulling this source category's growth above the broader, wood pulp-dominated market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.0% |
|
North America |
United States |
80.0% |
|
Europe |
Germany |
25.0% |
|
Latin America |
Brazil |
36.0% |
|
Middle East & Africa |
UAE |
29.0% |
Asia Pacific Cellulose Film Packaging Market Insights
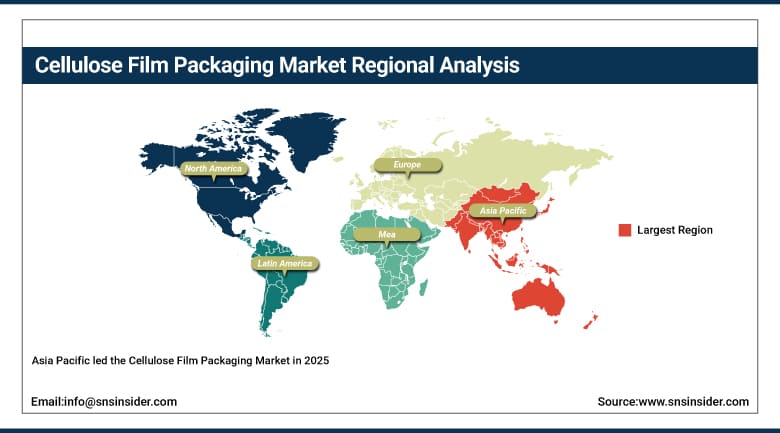
Asia Pacific led the Cellulose Film Packaging Market in 2025, driven by rapid industrialization and expanding food and consumer goods manufacturing across the region's largest and fastest-growing economies. Growing domestic cellulose film production capacity across multiple Asian countries continues reinforcing this leading position relative to import-dependent markets elsewhere.
China's large-scale cellophane and cellulose film manufacturing base, home to several established domestic producers, gives the region substantial baseline production and consumption capacity. Japan's mature cellulose film industry, anchored by established manufacturers with decades of production experience, contributes deep technical expertise, while Southeast Asian markets continue expanding alongside regional food and consumer goods manufacturing growth.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Cellulose Film Packaging Market Insights
North America is anticipated to have the fastest growing region through 2035 driven by growing state-based regulations and sustainability pledges by corporations within the food and consumer goods industries. In the United States, which serves as the driver of this growth, demand is focused on premium films used in the processing of food, pharmaceuticals and cosmetic products.
The Canadian market represents another source of demand, with food processing and consumer goods manufacturing providing demand drivers. In Mexico, demand is heavily import-driven due to the lack of cellulose film production capacity in Mexico. North American markets are largely linked in terms of supply and rely heavily on film imports from Asian and European producers.
Europe Cellulose Film Packaging Market Insights
Europe is one of the highly developed regions that use cellulose film packaging for its high quality. The local producers do not compete with the volume of packaging but use premium coatings for food, pharmaceuticals, and cosmetic purposes. The European regulations for biodegradable and compostable packages continue to ensure steady demand in the region.
The United Kingdom with a cellulose film plant is the base of manufacturing capacity of the region, while France, Italy, and Germany with considerable production of food, candies, and cosmetics drive consumption of the material. The regulations for packaging waste and single-use plastics are shaping the material specifications in Europe more than elsewhere.
MEA & Latin America Cellulose Film Packaging Market Insights
The Middle East and Africa represent a smaller but developing cellulose film packaging market, with the UAE driving demand through growing food processing and consumer goods retail investment tied to broader sustainability initiatives. Growth elsewhere in the region remains tied closely to the pace of broader packaging and consumer goods manufacturing infrastructure development.
Latin America is a growing market led by Brazil, where expanding food and confectionery manufacturing continues driving demand for biodegradable packaging alternatives. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing food processing and consumer goods sectors.
Market Dynamics
Growth Drivers: Plastic bans and biodegradable packaging demand fueling adoption
Rising regulatory pressure on single-use plastics is one of the clearest forces behind rising cellulose film demand, as governments worldwide restrict conventional plastic packaging and international bodies highlight the scale of plastic waste leaking into aquatic ecosystems each year. That regulatory pressure gives cellulose film producers a demand base that isn't entirely dependent on consumer preference shifting on its own.
Growing demand for biodegradable and compostable packaging solutions adds a second major driver, as food, personal care, and consumer goods brands increasingly seek genuine sustainability credentials rather than superficial green marketing claims. Improvements in coated cellulose film performance are reinforcing this shift, since brands no longer need to sacrifice barrier performance to gain compostability.
Restraints: Higher production costs and limited barrier performance versus plastic limiting broader adoption
Cellulose film usually is more expensive to manufacture than plastic film, and the higher cost represents a significant obstacle when the product is price sensitive, and the company does not have sustainability as part of its cost strategy. The high cost sensitivity can be a hindrance even for converters who are aware of the environmental benefits of cellulose film.
The natural deficiencies of uncoated cellulose film when compared to traditional plastic create another hurdle because cellulose film by itself cannot provide sufficient resistance to moisture, oxygen, and grease that is necessary in the packaging of certain food and pharmaceutical products.
Opportunities: Pharmaceutical blister lidding conversion and liquid sachet applications opening new growth avenues
Converting pharmaceutical blister pack lidding from PVC and PVDC to compostable cellulose-based alternatives offers manufacturers a genuine path to capturing steady, regulation-driven demand as the pharmaceutical industry pursues its own decarbonization commitments. Companies that build strong pharmaceutical drug master file relationships are positioned to capture this compliance-driven growth as more contract packaging organizations adopt cellulose-based lidding.
Liquid sachet and pouch applications represent a second significant opportunity, since recently demonstrated compostable solutions for wet, oily fills like sauces and creams open an entirely new packaging category that cellulose film couldn't previously serve reliably. Manufacturers that build genuine liquid sachet technology capability are positioned to capture disproportionate growth as this application matures from demonstration to commercial scale.
Recent Developments:
-
2025: China Lucky Film Corp., Sateri, and other Chinese cellulose film producers continued expanding domestic manufacturing capacity to meet rising regional demand for biodegradable packaging films.
-
2025: Multiple cellulose film manufacturers advanced work on updating pharmaceutical drug master files to include cellulose film specifications, supporting replacement of PVC/PVDC blister lidding with compostable alternatives.
-
2025: Rengo Co., Ltd. and other established Japanese packaging manufacturers continued expanding coated cellulose film product lines aimed at improving moisture and gas barrier performance for food packaging applications.
-
2025: Taghleef Industries and Kuraray continued investing in cellulose film production capacity to serve pharmaceutical blister pack lidding and medical device overwrap applications.
Cellulose Film Packaging Market Key Players
-
Futamura Chemical Co., Ltd.
-
Eastman Chemical Company
-
Innovia Films (Futamura)
-
Sateri Holdings Limited
-
Celanese Corporation
-
China Lucky Film Corporation
-
Chengdu Huaming Cellophane Co., Ltd.
-
Shaoxing Chunming Cellulose Film Co., Ltd.
-
Kuraray Co., Ltd.
-
Taghleef Industries Group
-
Rengo Co., Ltd.
-
Weifang Henglian Cellophane Co., Ltd.
-
Yibin Grace Group Co., Ltd.
-
Daicel Corporation
-
Nitto Boseki Co., Ltd.
-
UPM-Kymmene Corporation
-
Zhejiang Kelong Cellophane Co., Ltd.
-
Sichuan Push Packaging Material Group Co., Ltd.
-
ProAmpac LLC
-
Novamont S.p.A.
Cellulose Film Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.30 Billion |
| Market Size by 2035 | USD 2.55 Billion |
| CAGR | CAGR of 6.7% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Film Type (Plain/Cellophane Films, Coated Cellulose Films, Metallized Cellulose Films, Others) • by Color (Colorless/Transparent, Colored) • by Application (Food & Confectionery, Pharmaceuticals, Personal Care, Tapes & Labels, Bags & Pouches, Others) • by Source (Wood Pulp, Cotton Linters) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Futamura Chemical Co., Ltd., Eastman Chemical Company, Innovia Films (Futamura), Sateri Holdings Limited, Celanese Corporation, China Lucky Film Corporation, Chengdu Huaming Cellophane Co., Ltd., Shaoxing Chunming Cellulose Film Co., Ltd., Kuraray Co., Ltd., Taghleef Industries Group, Rengo Co., Ltd., Weifang Henglian Cellophane Co., Ltd., Yibin Grace Group Co., Ltd., Daicel Corporation, Nitto Boseki Co., Ltd., UPM-Kymmene Corporation, Zhejiang Kelong Cellophane Co., Ltd., Sichuan Push Packaging Material Group Co., Ltd., ProAmpac LLC, Novamont S.p.A. |
Frequently Asked Questions
Key players in the Cellulose Film Packaging Market include Futamura Chemical Co., Ltd., Eastman Chemical Company, Sateri Holdings Limited, Celanese Corporation, and Kuraray Co., Ltd., among others.
Key opportunities in the Cellulose Film Packaging Market include converting pharmaceutical blister pack lidding from PVC and PVDC to compostable cellulose-based alternatives and expanding liquid sachet and pouch applications for wet, oily fills.
The market is driven by rising regulatory pressure on single-use plastics, combined with growing demand for biodegradable and compostable packaging solutions across food, personal care, and pharmaceutical applications.
The Plain/Cellophane Films segment dominated the Cellulose Film Packaging Market, accounting for approximately 54.0% market share.
The Asia Pacific region dominated the Cellulose Film Packaging Market in 2025 with an approximately 41.0% share, driven by rapid industrialization and expanding food and consumer goods manufacturing across the region.
