
Medical Device Packaging Market Report Scope & Overview:
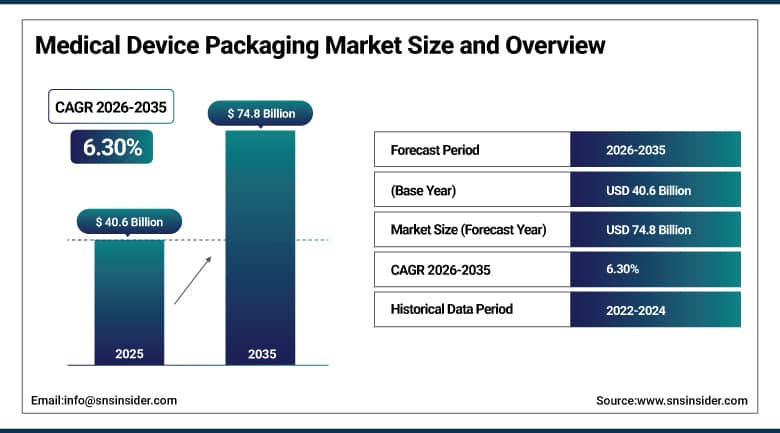
The Medical Device Packaging Market was valued at USD 40.6 Billion in 2025 and is expected to reach USD 74.8 Billion by 2035, growing at a CAGR of 6.30% from 2026 to 2035.
Medical device packaging industry is witnessing an unprecedented rate of growth due to increased number of surgeries, increasing use of single-use medical devices, and stringent sterilization and tracking rules. Medical device packaging acts as the final sterility assurance and compliance link between medical device makers and healthcare settings, which includes pouches, trays, bags, and clamshell packages designed to ensure that the device remains sterile throughout its journey from the point of production till the point of use. Moreover, consolidation within the industry among leading players providing packaging solutions, technological innovation in tracking and ensuring product safety, and regulatory requirement for sterile barrier integrity are contributing to industry growth.
The changes seen in the packaging of medical devices include smart labels using RFID tags for tracking, anti-microbial coatings, and laminate film. This clearly demonstrates how the packaging industry for healthcare has resorted to adopting technologically superior products that help meet regulatory standards and enhance the visibility of the supply chain.
To Get More Information On Medical Device Packaging Market - Request Free Sample Report
Medical Device Packaging Market Trends
- Smart technologies, including RFID labels and antimicrobial coatings, are enhancing traceability and safety in medical device packaging.
- Recyclable mono-material packaging solutions are supporting sustainability goals while maintaining stringent sterile barrier performance requirements.
- Industry consolidation is reshaping competition as leading providers expand cleanroom capacity and specialized sterile packaging capabilities.
- Growing adoption of single-use medical devices is sustaining demand for validated sterile pouches, trays, and wraps.
- Strategic partnerships among packaging manufacturers, healthcare providers, and regulators are advancing compliant, technology-enhanced packaging solutions.
U.S. Medical Device Packaging Market Outlook
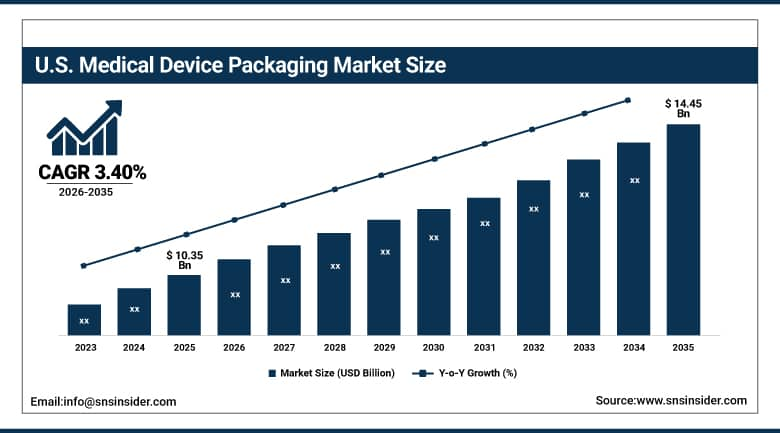
The U.S. Medical Device Packaging Market was valued at USD 10.35 Billion in 2025 and is projected to reach USD 14.45 Billion by 2035, growing at a CAGR of 3.40% during 2026–2035.
The top medical device packaging companies within the nation are increasing their cleanrooms due to increasing amounts of surgical procedures taking place and the increased use of single-use medical devices. FDA and EU MDR sterility assurance standards continue to increase the domestic demand for sterilized pouches, trays, and wraps throughout the diverse healthcare industry in the nation.
In May 2025, Innovative Sterilization Technologies received FDA 510(k) clearance for its ONE TRAY Sealed Sterilization Container System. This invention provides solutions for the increasing demands in the United States for reliable sterilized packaging systems, which continues to innovate in packaging systems that will secure medical equipment during the sterilization, storage, and medical processes.
Medical Device Packaging Market Segment Analysis
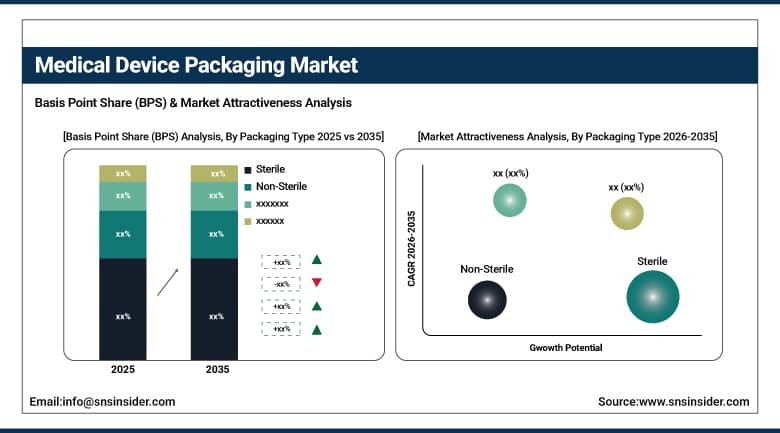
- By Packaging Type, sterile dominated the medical device packaging market with a 58.00% share in 2025, while non-sterile is the fastest-growing packaging type segment with a CAGR of 7.60% from 2026–2035.
- By Product, pouches & bags dominated the medical device packaging market with a 36.00% share in 2025, while trays is the fastest-growing product segment with a CAGR of 7.20% from 2026–2035.
- By Material, plastic dominated the medical device packaging market with a 54.30% share in 2025, while paper & paperboard is the fastest-growing material segment with a CAGR of 6.60% from 2026–2035.
- By End Use/Equipment Type, surgical equipment dominated the medical device packaging market with a 41.60% share in 2025, while disposable consumables is the fastest-growing end use/equipment type segment with a CAGR of 7.40% from 2026–2035.
By Packaging Type, sterile dominated the medical device packaging market, while non-sterile is the fastest-growing segment.
By packaging type, the sterile packaging segment dominated the medical device packaging market with a 58% share in 2025. Sterile packaging is the leading packaging type because the large majority of surgical instruments, implants, and single-use consumables must remain sterile from manufacture through point of use, requiring validated barrier systems produced under ISO Class 7 and ISO Class 8 cleanroom conditions.
The Non-Sterile segment is expected to register the fastest CAGR of 7.60% during the forecast period 2026-2035. Growing demand for non-sterile packaging supporting monitoring and diagnostic equipment, home healthcare devices, and reusable medical accessories is driving rising segment growth, as increasing home healthcare usage continues to expand device categories requiring durable, non-sterile packaging solutions.
By Product, pouches & bags dominated the medical device packaging market, while trays is the fastest-growing segment.
By product, the pouches & bags segment dominated the medical device packaging market with a 36% share in 2025. Pouches and bags remain the dominant product category owing to their versatile, cost-effective sterile barrier performance across a wide range of surgical instruments and single-use consumables, representing the most widely produced format across global medical device packaging manufacturing worldwide.
The Trays segment is expected to register the fastest CAGR of 7.20% during the forecast period 2026-2035. Growing demand for rigid tray packaging offering enhanced device protection, organized presentation, and compatibility with automated sterilization processes is driving rising segment growth across increasingly complex surgical instrument and implant packaging applications.
By Material, plastic dominated the medical device packaging market, while paper & paperboard is the fastest-growing segment.
Plastic material is expected to hold a share of 54.3% in 2025. Plastic remains the dominant material category owing to its established barrier performance, sterilization compatibility, and cost-effective production, including PP/PE formulations widely used across the majority of medical device packaging applications requiring validated sterile barrier integrity worldwide.
The Paper & Paperboard segment is expected to register the fastest CAGR of 6.60% during the forecast period 2026-2035. Growing development of recyclable mono-material packaging solutions is driving rising paper and paperboard segment growth, as manufacturers increasingly seek sustainable alternatives that maintain stringent sterile barrier performance while reducing environmental impact.
By End Use/Equipment Type, surgical equipment dominated the medical device packaging market, while disposable consumables is the fastest-growing segment.
Surgical equipment is projected to account for a 41.6% share in 2025. Surgical equipment remains the dominant end-use category owing to the rise in surgical procedures worldwide requiring validated sterile packaging for instruments, implants, and surgical accessories, representing the largest and most established application driving overall medical device packaging demand worldwide.
The disposable consumables segment is expected to register the fastest CAGR of 7.40% during the forecast period 2026-2035. Expanding adoption of single-use medical devices continues to sustain large, recurring demand for validated sterile packaging, driving rising disposable consumables segment growth as healthcare providers increasingly prioritize infection control through single-use device adoption.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
34.70% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Medical Device Packaging Market Insights
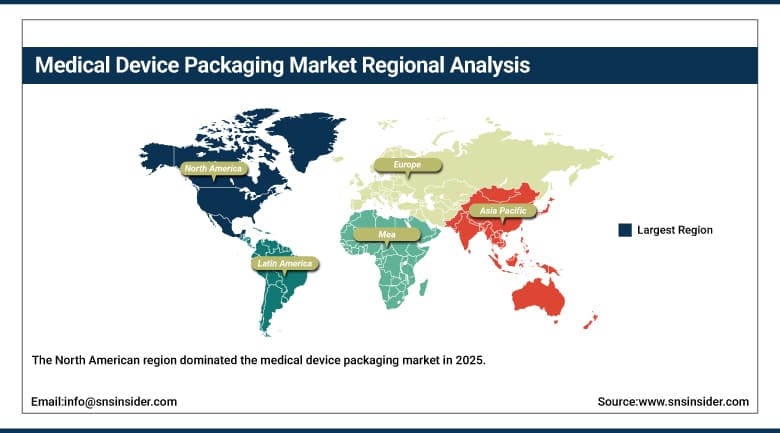
The North American region dominated the medical device packaging market in 2025. It is also anticipated to hold a significant share of the medical device packaging market, driven by rising surgical procedure volumes and stringent FDA sterility-assurance requirements across the region.
The United States will be leading the North America medical device packaging market during the forecast year with CAGR of 3.4%. Canada will be playing its part in the growth of the region due to its rising healthcare manufacturing infrastructure and increasing use of single-use devices.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Medical Device Packaging Market Insights
The European medical device packaging market continues to see steady growth, driven by advanced pharmaceutical infrastructure and major biotechnology centers supporting sustained demand across member states.
Germany is expected to maintain its leadership position with a 34.7% market share in 2025, supported by its advanced pharmaceutical infrastructure and major biotechnology centers. The United Kingdom follows with a significant share, driven by comprehensive pharmaceutical programs and biotechnology development initiatives.
Asia Pacific Medical Device Packaging Market Insights
Asia Pacific is expected to witness the fastest growth rate during the forecast period 2026-2035. The market growth is driven by expanding healthcare infrastructure investment, growing surgical procedure volumes, and rising medical device manufacturing capacity across the region's major and emerging economies.
China is one of the main growth drivers in the Asia Pacific Medical Device Packaging Market, owing to its expanding domestic medical device manufacturing capacity and growing healthcare infrastructure investment. India and Southeast Asian nations are also contributing to regional growth through expanding surgical procedure volumes and rising single-use device adoption.
Middle East & Africa and Latin America Medical Device Packaging Market Insights
Middle East & Africa and Latin American regions are gradually expanding medical device packaging market participation as healthcare infrastructure and medical device manufacturing investment grows across both regions.
Brazil is set to be a prominent Latin American market fueled by growing domestic healthcare manufacturing capacity and rising surgical procedure volumes. The Middle East & Africa region has UAE and Saudi Arabia investing in modern healthcare infrastructure that is expanding access to advanced medical device packaging categories across their growing healthcare sectors.
Market Dynamics
Growth Drivers: Rising surgical procedure volumes and single-use device adoption driving market growth
Rising surgical procedure volumes, expanding adoption of single-use medical devices, stringent sterility and traceability regulations, and large-scale industry consolidation among leading packaging providers are among the primary drivers of the Medical Device Packaging Market. Growth is closely tied to the expanding volume of surgical procedures, the proliferation of single-use medical products, and regulatory mandates governing sterile barrier integrity across global healthcare supply networks.
The growing demand for hospital care at the global level continues to escalate medical device packaging market growth, as stringent FDA and EU MDR sterility-assurance requirements sustain large, recurring demand for validated sterile pouches, trays, and wraps. Rising home healthcare usage, integration of smart technologies enhancing product traceability, and growing investment in cleanroom manufacturing capacity are further supporting demand across the forecast period.
Restraints: Regulatory complexity and high compliance costs limiting market expansion
Among the factors that inhibit market growth is the considerable expenses and complexity involved in ensuring sterile barrier systems are validated to meet FDA and EU MDR regulations, which limits smaller-scale packaging companies from competing with larger manufacturing firms that have already set up their own sterile barrier systems in cleanrooms.
Other factors that have been inhibiting market growth include logistical complexities and regulatory constraints in other international healthcare markets, where packaging needs to be supplied by manufacturing firms that cater to more than one global region. Recyclable mono-material packaging also requires considerable research and development effort.
Opportunities: Expansion of smart packaging technology and sustainable material development creating new growth avenues
The combination of smart packaging and IoT technology, including the RFID/NFC serialization and anti-counterfeiting capabilities, represents a lucrative business opportunity for the manufacturers who are able to come up with such solutions offering enhanced traceability and visibility in the supply chain.
A huge growth opportunity exists for those that develop designs and mono-material solutions which are recyclable and address the growing demand for sustainable solutions without compromising sterile barrier efficacy. The rise in the number of surgical procedures and the use of single-use devices in the developing countries of Asia Pacific and Latin America regions is set to open up tremendous growth opportunities in the forecast period.
Recent Developments:
- 2025: Amcor unveiled the next version of its medical laminates, a mono-material polyethylene (PE) laminate recyclable in PE's direction, offering reduced carbon content while maintaining high performance requirements for device applications.
- 2025: Comar acquired Automatic Plastic Ltd, a custom-based molding company based in Ireland, expanding its custom medical device and specialty packaging solutions portfolio.
- 2026: Nelipak Corporation expanded its cleanroom sterile packaging capacity, strengthening its ability to supply growing surgical instrument customer demand for validated barrier systems.
- 2026: Oliver Healthcare Packaging launched an updated high-barrier sterile pouch designed for single-use medical device applications, offering manufacturers enhanced regulatory compliance and patient safety assurance.
Medical Device Packaging Market key players are:
- Amcor plc
- AptarGroup, Inc.
- Becton, Dickinson and Company
- Cardinal Health, Inc.
- DuPont de Nemours, Inc.
- Nelipak Corporation
- Oliver Healthcare Packaging
- Coveris Holdings S.A.
- Amcor (Bemis Company, Inc.)
- WestRock Company
- Sonoco Products Company
- Sealed Air Corporation
- Constantia Flexibles Group GmbH
- Klöckner Pentaplast Group
- Comar, LLC
- West Pharmaceutical Services, Inc.
- Berry Global Inc.
- Placon Corporation
- Tekni-Plex, Inc.
- Sharp Packaging Services
Medical Device Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 40.6 Billion |
| Market Size by 2035 | USD 74.8 Billion |
| CAGR | CAGR of 6.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Packaging Type (Sterile, Non-Sterile, Active/Smart Packaging) • By Product (Pouches & Bags, Trays, Clamshell & Blister Packs, Boxes, Others) • By Material (Plastic, Paper & Paperboard, Metal, Others) • By End Use/Equipment Type (Surgical Equipment, Disposable Consumables, Therapeutic Equipment, Monitoring & Diagnostic Equipment, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, AptarGroup, Inc., Becton, Dickinson and Company, Cardinal Health, Inc., DuPont de Nemours, Inc., Nelipak Corporation, Oliver Healthcare Packaging, Coveris Holdings S.A., Amcor (Bemis Company, Inc.), WestRock Company, Sonoco Products Company, Sealed Air Corporation, Constantia Flexibles Group GmbH, Klöckner Pentaplast Group, Comar, LLC, West Pharmaceutical Services, Inc., Berry Global Inc., Placon Corporation, Tekni-Plex, Inc., Sharp Packaging Services |
Frequently Asked Questions
Key players include Amcor plc, AptarGroup, Inc., Becton, Dickinson and Company, Cardinal Health, Inc., and DuPont de Nemours, Inc., among others.
Key opportunities include smart packaging adoption, recyclable sterile packaging development, and increasing demand for validated packaging solutions for single-use medical devices.
The market is driven by rising surgical procedure volumes, expanding adoption of single-use medical devices, and stringent sterility and traceability regulations.
The Sterile segment dominated the Medical Device Packaging Market, accounting for approximately 58% market share.
The North America region dominated the Medical Device Packaging Market in 2025, holding a significant share driven by rising surgical procedure volumes.
