
Food Service Disposables Market Report Scope & Overview:
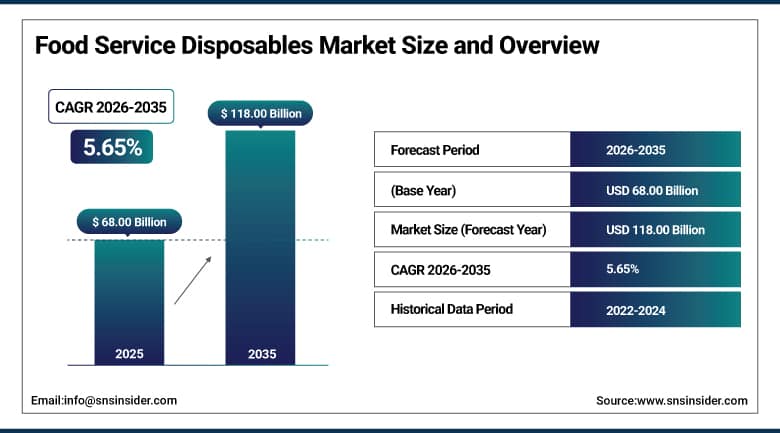
The Food Service Disposables Market was valued at USD 68.00 Billion in 2025 and is expected to reach USD 118.00 Billion by 2035, growing at a CAGR of 5.65% from 2026–2035.
Food service disposables cover every single-use item a restaurant, cafeteria, or delivery kitchen hands a customer, plates, cups, cutlery, containers, napkins, all designed to be used once and thrown away without ever needing to be washed or returned. That single-use design isn't just a convenience choice, it's a genuine hygiene requirement in an industry where cross-contamination between customers is a real liability, which is why disposables remain standard even at restaurants otherwise committed to reducing waste elsewhere. The explosive growth of online food delivery has reshaped this category more than almost anything else in the last decade, since delivery packaging has to survive transit and hold heat or cold in ways dine-in tableware never had to.
Pactiv Evergreen launched a next-generation bagasse plate production line across three U.S. manufacturing facilities in May 2025, targeting annual output of 200 million units with full ASTM D6400 compostability certification. A recent survey of 220 category managers and procurement directors found that 58% now rate sustainability certification as the single most influential factor in disposable plate supplier selection, ahead of price, and nearly three-quarters said they plan to drop suppliers without credible certified-compostable portfolios within the next 18 months, a genuinely fast timeline for an industry that used to compete almost entirely on cost per thousand units.
To Get More Information On Food Service Disposables Market - Request Free Sample Report
Food Service Disposables Market Trends
-
Certified-compostable and PFAS-free product lines continue becoming a baseline procurement requirement rather than a premium differentiator, as major restaurant chains and food delivery platforms tighten supplier sustainability criteria.
-
Growth in online food delivery continues reshaping product design priorities, pushing manufacturers toward leak-resistant, insulated, and tamper-evident formats built specifically for transit rather than dine-in service.
-
Molded fiber and bagasse formats continue gaining share over conventional plastic and foam, as manufacturers scale production of biodegradable alternatives that meet expanding regulatory and brand-owner sustainability requirements.
-
Smart packaging integration, including QR codes for customer engagement, continues emerging as manufacturers look for ways to differentiate disposable products beyond basic functional performance.
-
Subscription-based supply models continue gaining traction among smaller food service operators, letting them secure regular disposable product deliveries without managing inventory and procurement in-house.
U.S. Food Service Disposables Market Outlook
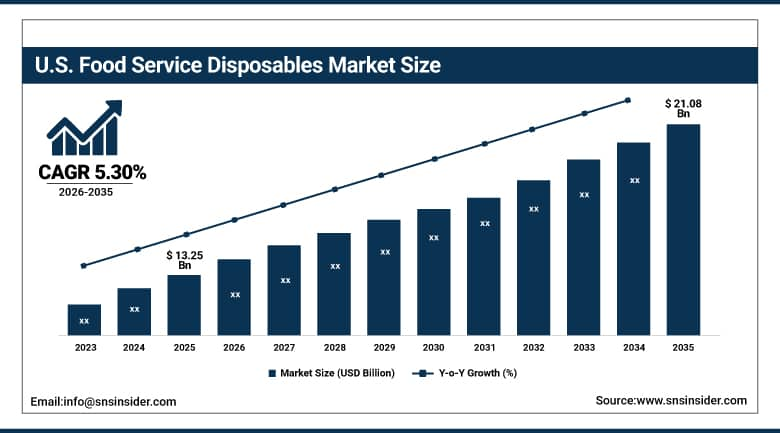
The U.S. Food Service Disposables Market was valued at approximately USD 13.25 Billion in 2025 and is expected to reach approximately USD 21.08 Billion by 2035, growing at a CAGR of approximately 5.30%.
Demand in the United States is anchored by a large quick-service restaurant sector and continued growth in online meal delivery, which has experienced exponential growth in popularity due to the convenience it offers busy consumers. A concentration of the world's largest foodservice disposables manufacturers, several with decades-long supply relationships with major national restaurant chains, continues anchoring domestic production and innovation capacity. Growing procurement pressure toward certified-compostable and PFAS-free products continues reshaping material specification requirements across the industry's largest domestic suppliers.
Dart Container Corporation, based in Mason, Michigan, expanded its ProPlanet line of compostable fiber food containers in August 2025, part of a broader push toward PFAS-free packaging solutions across its domestic manufacturing footprint. As one of the largest American foodservice disposables manufacturers, Dart's own sustainability roadmap decisions carry outsized weight across the industry, since restaurant chains and food delivery platforms sourcing at national scale often follow whichever direction the biggest suppliers move first rather than pushing smaller manufacturers to lead.
Food Service Disposables Market Segment Analysis
-
By Packaging Type, the Rigid segment dominated the Food Service Disposables Market with approximately 77.10% share in 2025, while the Flexible segment is the fastest growing with a CAGR of approximately 7.40%.
-
By Product Type, the Plates segment dominated the Food Service Disposables Market with approximately 38.00% share in 2025, while the Containers & Trays segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Material, the Plastic segment dominated the Food Service Disposables Market with approximately 42.60% share in 2025, while the Bagasse/PLA/Bioplastics segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Application, the Food Service segment dominated the Food Service Disposables Market with approximately 50.20% share in 2025, while the Online Delivery segment is the fastest growing with a CAGR of approximately 8.60%.
-
By End-User, the Restaurants segment dominated the Food Service Disposables Market with approximately 36.60% share in 2025, while the Food Delivery Outlets segment is the fastest growing with a CAGR of approximately 8.80%.
By Packaging Type, rigid dominates, flexible grows fastest
Rigid packaging held the overwhelming majority of the packaging-type segment in 2025, spanning plates, containers, bowls, tubs, mugs, saucers, and lids that together represent the industry's most established and highest-volume product category. Rigid, plastic-made products in particular are witnessing substantial growth, while mugs, saucers, and containers used for hot and cold beverages made from metal and glass provide the insulated protection needed to decrease food spoilage risk from inadequate temperature control during service and transit.
Flexible packaging is growing fastest as bags, wraps, and pouches continue gaining share for takeout and delivery applications where lighter weight and lower material use offer genuine cost and shipping advantages over rigid alternatives. Growing e-commerce and food delivery volume, combined with rising sustainability pressure favoring lower-material-use formats, continues reinforcing this above-average growth trajectory relative to the broader, rigid-dominated packaging-type mix.
By Product Type, plates dominates, containers & trays grows fastest
Plates held the largest share of the product-type segment in 2025, driven by catering expansion, fast-food penetration, and rising demand for convenience solutions across restaurants, institutional food service, and event catering. That combination of high-frequency daily use and broad application across nearly every food service setting keeps plates the dominant product category by a wide margin over other disposable formats across the industry.
Containers and trays are growing fastest as trays and containers lead in food delivery and storage solutions, a category directly tied to the explosive growth of online and offline food delivery platforms. Rising demand for leak-resistant, insulated, and tamper-evident container designs built specifically for transit continues reinforcing this above-average growth trajectory relative to the broader, plate-dominated product mix.
By Material, plastic dominates, bagasse/PLA/bioplastics grows fastest
Plastic was the dominant material component in 2025 because of its low cost, moisture-resistance properties, and wide-ranging ability to be molded into nearly any kind of disposable item, from cups to cutlery to containers. Because of plastic’s suitability for fast-molding and thermo-forming processes, it is still the default material in most food service disposables manufacturing operations, despite increasing pressure against traditional plastic products.
Bagasse, polylactic acid, and other bioplastics are experiencing rapid growth due to expansion in the development of biodegradable products that satisfy the needs of environmentally conscious consumers and brand owners in the wake of new production lines achieving full compostability certification. Increasing regulations and environmental preferences ensure that the growth rates seen for biodegradable products remain above average compared to the entire plastics-based material spectrum.
By Application, food service dominates, online delivery grows fastest
Food service accounted for the largest application share in 2025, reflecting the sheer scale and daily frequency of in-restaurant and cafeteria dining occasions that continue generating the industry's highest-volume disposable product consumption. That established, high-frequency demand pattern keeps traditional food service the anchor application by a wide margin over newer, delivery-focused application categories across the broader market.
Online delivery is the fastest-growing application as deliveries of food via a wide range of online and offline platforms have become one of the e-commerce industry's fastest-growing offerings, with widespread availability of apps giving food businesses access to new customer channels. That structural shift toward delivery-based dining continues pulling this application category's growth well ahead of the broader, traditional-food-service-dominated application mix.
By End-User, restaurants dominates, food delivery outlets grows fastest
Restaurants accounted for the largest end-user share in 2025, anticipated to dominate the market given the sheer scale and consistency of daily disposable product consumption across dine-in, takeout, and catering operations worldwide. That combination of high transaction volume and broad geographic distribution keeps restaurants the anchor end-user category across the entire food service disposables market, regardless of which specific product or material trend is currently accelerating.
Food delivery outlets are the fastest-growing end-user category as increasing popularity of meal kit delivery services and third-party delivery platforms continues expanding demand for disposable products engineered specifically for transit durability and temperature retention. Growing consumer preference for convenience and increasing penetration of online meal delivery, especially in developing regions, continues reinforcing this above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
47.40% |
|
North America |
United States |
81.20% |
|
Europe |
Germany |
25.30% |
|
Latin America |
Brazil |
35.70% |
|
Middle East & Africa |
UAE |
29.90% |
Asia Pacific Food Service Disposables Market Insights
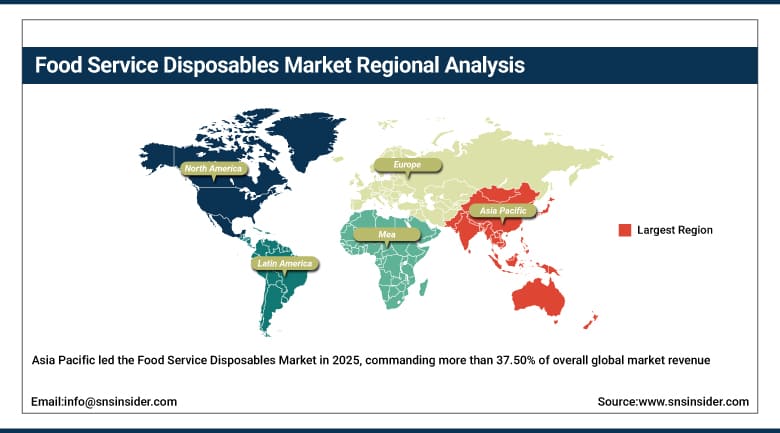
Asia Pacific led the Food Service Disposables Market in 2025, commanding more than 37.50% of overall global market revenue, driven by the increasing popularity of quick-service restaurants across developing regions given busy lifestyles and hectic work schedules. China dominated the regional market with a major revenue share, reflecting the country's massive food service and delivery infrastructure, while rising disposable incomes and rapidly expanding organized retail across the region's largest economies continue reinforcing this leading position.
India's rapidly expanding café culture and food delivery penetration are drawing significant new investment in disposable product manufacturing capacity, while Japan and South Korea represent more mature, quality-focused markets with established hygiene and packaging standards. Southeast Asian markets continue following a similar urbanization-driven growth trajectory as regional food service and delivery infrastructure expands across the broader region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Food Service Disposables Market Insights
North America is expected to register the fastest regional growth through 2035, supported by rising demand for convenient packaging in the growing food delivery sector and the continued exponential growth in popularity of online meal delivery platforms. The United States anchors this leadership, home to a large quick-service restaurant sector and deep concentration of the world's largest foodservice disposables manufacturers.
Canada contributes a meaningful share through its own food service and delivery sector, while Mexico's market continues expanding alongside growing organized food service investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production networks.
Europe Food Service Disposables Market Insights
Europe is a mature and sustainable disposables market in food services that is influenced by the wide-ranging European Union packaging waste legislation and high consumer demand for compostable and recyclable disposables products. Germany is the backbone of the regional market due to its thriving food service industry and disposables manufacturing companies developing materials that are certified compostable.
Other significant contributors in terms of volume are France, Italy, and the UK due to their strong food services and deliveries industries that are changing in accordance with the EU sustainability standards. The trend towards molded fiber and bioplastic alternatives becomes even more apparent in the region than in many other global markets.
MEA & Latin America Food Service Disposables Market Insights
The Middle East and Africa represent a smaller but developing food service disposables market, with the UAE driving demand through growing hospitality, tourism, and food delivery investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader food service and organized retail infrastructure development across neighboring markets.
Latin America is a growing market led by Brazil, where expanding quick-service restaurant and food delivery sectors continue driving demand for cost-efficient disposable products. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing food service sectors serving both domestic consumption and urban delivery growth.
Market Dynamics
Growth Drivers: Online food delivery growth and QSR expansion fueling adoption
Rising demand for convenient packaging in the growing food delivery sector is one of the clearest forces behind rising food service disposables demand, as deliveries of food via a wide range of online and offline platforms have become one of the e-commerce industry's fastest-growing offerings. That structural shift toward delivery-based dining gives the market a demand base tied directly to a consumption pattern that continues expanding rather than plateauing across nearly every major economy.
Growth of quick-service restaurants, especially in developing regions, adds a second major driver, as busy lifestyles and hectic work schedules continue expanding QSR penetration and, with it, sustained demand for the disposable products these operations depend on for every transaction. Rising urbanization and on-the-go consumption patterns continue reinforcing this demand base across both developed and emerging markets simultaneously.
Restraints: Environmental regulation and raw material price volatility limiting margin stability
Increasing regulations and consumer preference for sustainable and biodegradable packaging solutions add a genuine restraint for manufacturers still reliant on conventional plastic formats, as expanding restrictions on single-use plastics across multiple jurisdictions force costly reformulation and material transition investment. That regulatory pressure adds real compliance complexity for manufacturers serving customers across multiple, inconsistently regulated markets simultaneously.
Periodic price fluctuations in crude oil, impacting plastics, and pulp, impacting paper-based disposables, add a further restraint, with the rising price of environmentally friendly materials like PLA and molded fiber having raised the mean unit price of eco-friendly disposables specifically. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-product demand remains steady.
Opportunities: Certified-compostable format conversion and delivery-optimized design opening new growth avenues
Format conversion into certified-compostable is a way for manufacturers to have access to premium business in the form of restaurant chains and food delivery platforms, which are increasingly insisting on certification of sustainability as a basic prerequisite to become their suppliers instead of being optional to differentiate themselves. Firms who can manage to grow their sales of certified-compostables, which will have to be certified by a credible body such as ASTM D6400, are likely to grow in disproportionately.
Another key opportunity comes in the form of delivery-optimized product design. With the online ordering business growing at a fast rate, there is increased demand for packaging formats that are resistant to leakage, are insulated and are tamper-proof, designed specifically with deliveries in mind and not converted from existing dine-in formats. Firms that develop this expertise of delivery-optimized design will capture disproportionate growth.
Recent Developments:
-
August 2025: Dart Container Corporation expanded its ProPlanet line of compostable fiber food containers, advancing PFAS-free packaging solutions.
-
Q2 2024: Pactiv Evergreen announced a $50 million investment to expand its manufacturing facility in Ohio, increasing capacity for paper-based disposable products.
-
Q2 2024: Huhtamaki launched a new line of compostable cutlery for the European foodservice market, expanding its eco-friendly disposable product offerings.
-
2025: Huhtamaki continued restructuring its raw material sourcing toward certified-sustainable fiber streams, targeting 100% sustainably sourced primary fiber across food service lines by 2030.
Food Service Disposables Market Key Players
-
Dart Container Corporation
-
Berry Global Inc.
-
Pactiv Evergreen Inc.
-
Huhtamaki Oyj
-
Genpak, LLC
-
Sabert Corporation
-
Georgia-Pacific LLC
-
Novolex Holdings, LLC
-
International Paper Company
-
Amcor plc
-
Fabri-Kal Corporation
-
Smurfit WestRock plc
-
Sealed Air Corporation
-
Sonoco Products Company
-
Graphic Packaging International, LLC
-
Reynolds Consumer Products Inc.
-
Winpak Ltd.
-
Vegware Ltd.
-
BioPak Pty Ltd.
-
Platinum Packaging Group
Food Service Disposables Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 68.00 Billion |
| Market Size by 2035 | USD 118.00 Billion |
| CAGR | CAGR of 5.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Packaging Type (Rigid, Flexible) • by Product Type (Plates, Cups & Glasses, Containers & Trays, Cutlery, Napkins, Bags, Straws & Stirrers, Others) • by Material (Plastic, Paper & Paperboard, Bagasse, Polylactic Acid (PLA)/Bioplastics, Aluminum, Others) • by Application (Food Service, Online Delivery, Institutional) • by End-User (Restaurants, Hotels & Motels, QSRs/Tea-Coffee-Snack Shops, Retail & Vending Machines, Food Delivery Outlets, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Dart Container Corporation, Berry Global Inc., Pactiv Evergreen Inc., Huhtamaki Oyj, Genpak, LLC, Sabert Corporation, Georgia-Pacific LLC, Novolex Holdings, LLC, International Paper Company, Amcor plc, Fabri-Kal Corporation, Smurfit WestRock plc, Sealed Air Corporation, Sonoco Products Company, Graphic Packaging International, LLC, Reynolds Consumer Products Inc., Winpak Ltd., Vegware Ltd., BioPak Pty Ltd., Platinum Packaging Group |
Frequently Asked Questions
Key players in the Food Service Disposables Market include Dart Container Corporation, Berry Global Inc., Pactiv Evergreen Inc., Huhtamaki Oyj, and Genpak, LLC, among others.
Key opportunities in the Food Service Disposables Market include certified-compostable format conversion meeting tightening procurement standards and delivery-optimized product design for transit durability and temperature retention.
The market is driven by rising demand for convenient packaging in the growing food delivery sector, combined with growth of quick-service restaurants especially in developing regions.
The Plates segment dominated the Food Service Disposables Market, accounting for approximately 38.00% market share.
The Asia Pacific region dominated the Food Service Disposables Market in 2025 with more than 37.50% share, driven by the increasing popularity of quick-service restaurants across developing regions.
