
Pancreatic and Biliary Stents Market Report Scope & Overview:
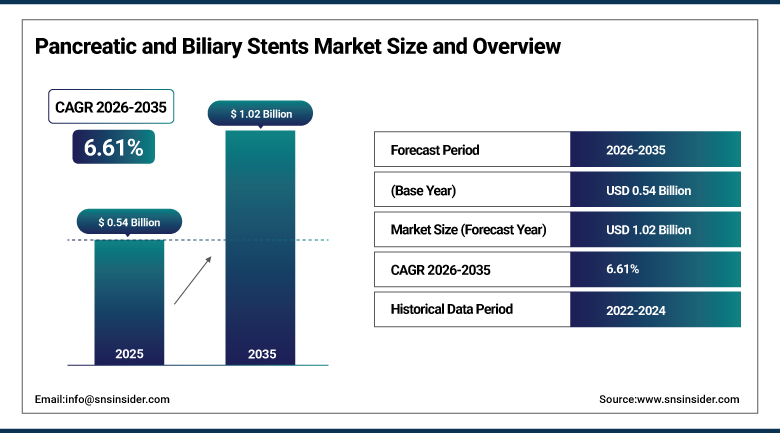
The Pancreatic and Biliary Stents Market was valued at USD 0.54 Billion in 2025 and is expected to reach USD 1.02 Billion by 2035, growing at a CAGR of 6.61% from 2026-2035.
The Pancreatic and Biliary Stents Market covers endoscopic, endoscopic ultrasound-guided, and percutaneous drainage for malignant and benign obstructions in the common bile duct and pancreatic duct, comprising of plastic stents in straight and pigtail designs, self-expanding metal stents in uncovered, partially covered, and fully covered varieties, as well as lumen-apposing metal stents for endoscopic ultrasound-guided gallbladder drainage and pancreatic fluid collections. A pancreatic and biliary stent is a tube, which can be made up of either plastic or metal, placed in a duct or lumen inside the body to keep an open pathway in the bile or pancreatic ducts. Stents are also used in the treatment of biliary and pancreatic leaks or in preventing post-endoscopic retrograde cholangiopancreatography pancreatitis. The rising prevalence of pancreatic cancer, biliary obstruction, gallstones disease, and chronic pancreatitis around the globe continues to provide impetus to the market.
In October 2025, Boston Scientific Corporation announced that it received 510(k) clearance from the U.S. Food and Drug Administration and CE Mark approval to market its Advanix Biliary Plastic Stents. These stents are indicated for the treatment of biliary strictures, including biliary stone disease, benign biliary strictures, and suspected or confirmed malignancies of the biliary system, and the product is now available in Europe and other international markets, reinforcing continued regulatory momentum supporting expanded plastic stent product portfolios across major global markets.
To Get more information Pancreatic and Biliary Stents Market - Request Free Sample Report
Pancreatic and Biliary Stents Market Trends
-
Rising clinical preference for self-expanding metal stents in the management of malignant biliary obstructions.
-
Growing adoption of lumen-apposing metal stents for endoscopic ultrasound-guided drainage procedures.
-
Expanding use of endoscopic ultrasound-guided techniques as first-line therapy for peripancreatic fluid collections.
-
Increasing advancements in diagnostic imaging enabling earlier detection of biliary and pancreatic complications.
-
Rising regulatory approval activity supporting expanded plastic and metal stent product portfolios across major markets.
-
Growing off-label application of lumen-apposing metal stents across novel abdominopelvic drainage indications.
U.S. Pancreatic and Biliary Stents Market Outlook
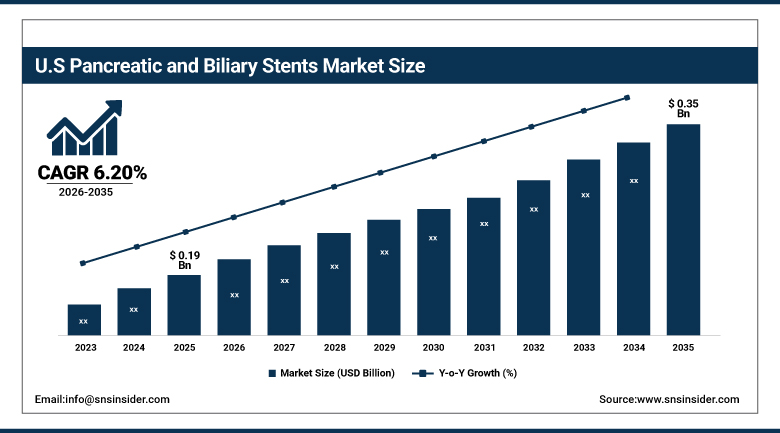
The U.S. Pancreatic and Biliary Stents Market was valued at USD 0.19 Billion in 2025 and is expected to reach USD 0.35 Billion by 2035, growing at a CAGR of 6.20% from 2026-2035.
The U.S. Pancreatic and Biliary Stents Market continues to benefit from the increasing prevalence of pancreaticobiliary diseases and the growing shift toward minimally invasive endoscopic interventions across domestic hospital and ambulatory surgical center settings. Domestic clinical practice continues to reflect the broader industry shift toward endoscopic ultrasound-guided techniques, with lumen-apposing metal stents increasingly utilized for peripancreatic fluid collection drainage, endoscopic ultrasound-guided biliary drainage following failed endoscopic retrograde cholangiopancreatography, and gallbladder drainage in high-risk surgical candidates with acute cholecystitis. Continued advancement in stent design and delivery system technology continues to support expanding clinical adoption across an increasingly broad range of both approved and off-label applications.
Boston Scientific Corporation continued expanding its Hot AXIOS Stent and Electrocautery-Enhanced Delivery System, indicated for endoscopic ultrasound-guided drainage of the bile duct, pancreatic pseudocysts, and the gallbladder.
Pancreatic and Biliary Stents Market Segment Analysis
-
By Product Type, the Self-Expanding Metal Stents segment dominated the Pancreatic and Biliary Stents Market with approximately 62.60% share in 2025, while the Lumen-Apposing Metal Stents segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Application, the Pancreatic Cancer segment dominated the Pancreatic and Biliary Stents Market with approximately 38.60% share in 2025, while the Benign Biliary Strictures segment is the fastest growing with a CAGR of approximately 7.80%.
-
By End-User, the Hospitals segment dominated the Pancreatic and Biliary Stents Market with approximately 68.60% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Procedure Type, the Endoscopic (ERCP) segment dominated the Pancreatic and Biliary Stents Market with approximately 58.60% share in 2025, while the EUS-Guided segment is the fastest growing with a CAGR of approximately 8.40%.
By Product Type, Self-Expanding Metal Stents Dominates the Pancreatic and Biliary Stents Market and Lumen-Apposing Metal Stents Grows Fastest
Self-expanding metal stents hold the largest product type share, attributable to their superior radial strength, reduced risk of occlusion, and increasing clinical preference for self-expandable metal stents in the management of malignant biliary obstructions that require durable and long-term drainage solutions. The rising incidence of malignant biliary obstructions, particularly those associated with pancreatic cancer and cholangiocarcinoma, continues to be a key factor driving sustained adoption of metal biliary stents across the broader market.
Lumen-apposing metal stents represent the fastest-growing product type, as these self-expanding, fully covered devices capable of forming stable anastomoses between adjacent organs and cavities continue to gain adoption for both approved and off-label drainage indications. The ease of deployment and familiarity with the delivery system continues to make lumen-apposing metal stents an increasingly preferred option when conventional endoscopic methods have failed, positioning this product type for sustained above-market growth as procedures utilizing this technology continue to become increasingly widespread.
By Application, Pancreatic Cancer Dominates the Pancreatic and Biliary Stents Market and Benign Biliary Strictures Grows Fastest
Pancreatic cancer represents the largest application segment, as malignant biliary obstruction associated with this condition requires frequent stent placement to improve biliary drainage, relieve jaundice, and enable continued cancer treatment. Growth in this application is primarily driven by the rising global incidence of pancreatic cancer, a significant proportion of which presents with malignant biliary obstruction at the time of diagnosis, continuing to sustain this application's position as the largest source of stent demand.
Benign biliary strictures represent the fastest-growing application, scaling rapidly as minimally invasive endoscopic retrograde cholangiopancreatography management becomes increasingly common for post-surgical injuries, inflammatory strictures, and recurrent obstruction. This expanding clinical application continues to reflect the broader shift toward endoscopic management of benign biliary conditions that previously required more invasive surgical intervention.
By End-User, Hospitals Dominates the Pancreatic and Biliary Stents Market and Ambulatory Surgical Centers Grows Fastest
Hospitals represent the largest end-user segment, reflecting the complexity of pancreatic and biliary stent placement procedures, which typically require specialized endoscopic equipment, advanced imaging capability, and multidisciplinary clinical support available primarily within hospital settings. The scale of hospital-based gastroenterology and interventional radiology programs continues to sustain hospitals' position as the largest end-user category for pancreatic and biliary stent procedures.
Ambulatory surgical centers represent the fastest-growing end-user segment, as continued advancement in endoscopic technique and device design continues to expand the range of pancreatic and biliary stent procedures suitable for outpatient settings. This shift toward ambulatory care delivery continues to reflect broader healthcare system efforts to reduce procedure costs while maintaining clinical outcomes for appropriately selected patients.
By Procedure Type, Endoscopic (ERCP) Dominates the Pancreatic and Biliary Stents Market and EUS-Guided Grows Fastest
Endoscopic retrograde cholangiopancreatography still leads as the most common procedure type, as it continues to be the gold standard first-line treatment for stent placement in both benign and malignant conditions of pancreas and biliary tract. The extensive history of use of this procedure, along with its availability at all gastroenterology departments of hospitals, ensures its leading position in the number of performed stent placement procedures.
Endoscopic ultrasound-guided procedures remain the fastest growing procedure type, since the use of this procedure becomes a preferable option for biliary and pancreatic drainage in case of failures in endoscopic retrograde cholangiopancreatography or its infeasibility. The increasing use of endoscopic ultrasound-guided biliary drainage instead of percutaneous transhepatic biliary drainage, especially in malignant distal biliary obstruction in case of presence of local expertise in this procedure, ensures continued above-market growth.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Pancreatic and Biliary Stents Market Insights
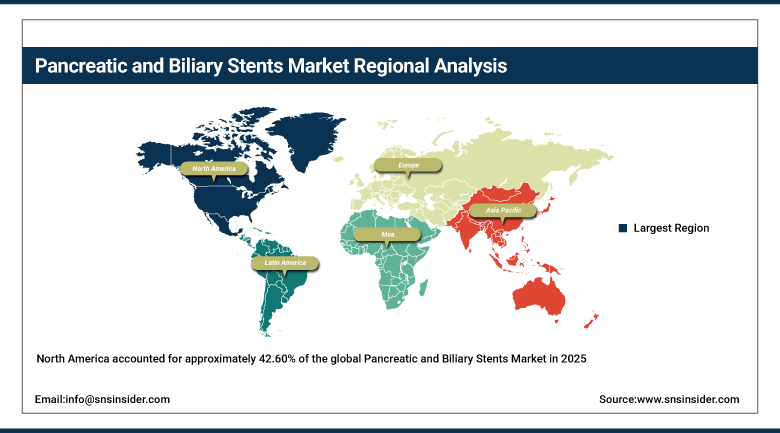
North America accounted for approximately 42.60% of the global Pancreatic and Biliary Stents Market in 2025, making it the largest regional market, supported by the region's advanced healthcare infrastructure, established gastroenterology and interventional radiology practice base, and sustained clinical adoption of minimally invasive endoscopic techniques. The region's concentration of leading medical device manufacturers continues to reinforce North America's position as the largest source of global pancreatic and biliary stent demand.
Canada is contributing incremental regional demand as its own healthcare system continues to expand access to advanced endoscopic procedures. Continued domestic investment in stent technology innovation and regulatory approval activity is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Pancreatic and Biliary Stents Market Insights
Asia Pacific is the fastest-growing regional market, driven by rising incidence of pancreaticobiliary diseases, expanding healthcare infrastructure investment, and growing adoption of minimally invasive endoscopic techniques across China, Japan, and other major regional economies. China's large and aging population continues to drive substantial regional demand for pancreatic and biliary stent procedures as healthcare access and diagnostic capability continue to expand.
Japan's established medical device regulatory framework continues to support market entry for innovative stent technologies, exemplified by recent regulatory approval activity enabling commercial launch of new biliary stent products within the domestic market. South Korea and India contribute additional regional scale through expanding healthcare infrastructure and rising clinical adoption of advanced endoscopic procedures, reinforcing Asia Pacific's position as the fastest-growing market through the forecast period.
Europe Pancreatic and Biliary Stents Market Insights
Europe holds considerable weightage in the global Pancreatic and Biliary Stents market owing to the strong health care setup of Germany. The region's regulations like that of CE Mark are helping new products to gain market entry through quick approvals in the major health care markets of Europe.
The UK, France, and other European nations are contributing to the constant regional demand owing to the provision of endoscopic drainage procedures in the national health care setups. The stent technology manufacturers in the region continue to innovate in terms of stent designs.
MEA & Latin America Pancreatic and Biliary Stents Market Insights
The Middle East & Africa market remains comparatively modest but is expanding as growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia sustains demand for advanced endoscopic procedure capability. Regional governments continue investing in expanding specialized gastroenterology and interventional radiology centers to serve growing domestic demand.
Latin America's market is led by Brazil, where a growing healthcare infrastructure continues to drive gradual pancreatic and biliary stents market growth. Mexico is contributing incremental growth as regional healthcare access continues to expand, with adoption across the broader region concentrated among larger urban medical centers with established endoscopic procedure capability.
Market Dynamics
Growth Drivers: Rising Disease Prevalence and Minimally Invasive Procedure Adoption
The growing number of pancreaticobiliary conditions is the main factor driving the market growth for Pancreatic and Biliary Stents due to the growing incidence of diseases, such as pancreatic cancer, gallstones, and chronic pancreatitis worldwide that result in an expanding target audience needing stent drainage procedures. The rising number of malignant biliary blockages and those linked to pancreatic cancer and cholangiocarcinoma reinforces the need for a reliable and long-term drainage system.
Another important growth driver is the increasing preference for less invasive endoscopic treatment. Owing to the improvements in stent designs and materials, less invasive procedures lead to better outcomes compared to surgical procedures. Improvements in imaging diagnosis, such as ultrasonography and magnetic resonance imaging, allow for early detection of biliary and pancreatic disorders.
Restraints: Procedure Complexity and Device-Related Adverse Events
Procedure complexity represents a meaningful restraint on market growth, as pancreatic and biliary stent placement continues to require specialized endoscopic expertise and equipment that may not be uniformly available across all healthcare settings, particularly in emerging markets with more limited gastroenterology specialist capacity.
Device-related adverse events represent a further restraint, as stent occlusion, migration, and other complications continue to require careful clinical management and, in some cases, repeat intervention. With increasing procedural volume, particularly for lumen-apposing metal stent applications, an increase in adverse event incidence remains a recognized clinical consideration that continues to require ongoing physician training and device refinement.
Opportunities: Product Innovation and Expanding EUS-Guided Applications
Innovation of stents materials and designs is an enormous opportunity, where those companies who have an ability to provide higher biocompatibility, durability, and better deployability are able to satisfy demand of clinicians searching for more efficient drainage devices in complicated cases.
Growth opportunities in the EUS procedures is another field, as lumen-apposing metal stents are gaining popularity in off-label abdominopelvic indications. Those companies that are able to prove their clinical efficiency through additional studies are able to capture demand of advanced endoscopists who are using the device in various drainage procedures.
Recent Developments:
-
In December 2025, Olympus Corporation, W. L. Gore & Associates, and ConMed Corporation announced the transition of commercial support and distribution for the GORE VIABIL Biliary Endoprosthesis in the U.S. This strategic realignment enhances Olympus's footprint in the U.S. fully covered metal biliary stents segment and strengthens market access for the VIABIL biliary stent through Olympus's established endotherapy sales network.
-
In July 2024, CGBIO received product approval from Japan's Pharmaceuticals and Medical Devices Agency for its ARISTENT biliary stents. This regulatory milestone enabled the commercial launch of ARISTENT within the Japanese market, expanding the company's presence in the region's biliary stent segment.
Pancreatic and Biliary Stents Market Key Players
-
Boston Scientific Corporation
-
Medtronic plc
-
Olympus Corporation
-
CONMED Corporation
-
Abbott Laboratories
-
Cook Medical LLC
-
Taewoong Medical Co., Ltd.
-
ENDO-FLEX GmbH
-
ELLA-CS, s.r.o.
-
Becton, Dickinson and Company
-
W. L. Gore & Associates, Inc.
-
Merit Medical Systems, Inc.
-
Micro-Tech Endoscopy
-
M.I.Tech Co., Ltd.
-
Fujifilm Holdings Corporation
-
Standard SciTech Inc.
-
Hobbs Medical, Inc.
-
Gadelius Medical K.K.
-
CGBIO Co., Ltd.
-
Medorah Meditek Pvt. Ltd.
Pancreatic and Biliary Stents Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.54 Billion |
| Market Size by 2035 | USD 1.02 Billion |
| CAGR | CAGR of 6.61% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Plastic Stents, Self-Expanding Metal Stents, and Lumen-Apposing Metal Stents) • by Application (Pancreatic Cancer, Benign Biliary Strictures, Biliary Leaks, and Gallstones) • by End-User (Hospitals and Ambulatory Surgical Centers) • by Procedure Type (Endoscopic/ERCP, EUS-Guided, and Percutaneous) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Denso Corporation, Hanon Systems, Valeo S.A., MAHLE GmbH, Sanden Holdings Corporation, Toyota Industries Corporation, Panasonic Corporation, Halla Mechatronics Corporation, BorgWarner Inc., Bitzer Kühlmaschinenbau GmbH, LG Electronics Inc., Guangzhou Highly Group Co., Ltd., Zhejiang Sanhua Automotive Co., Ltd., Shanghai Baolong Automotive Corporation, Aisin Corporation, Continental AG, Marelli Corporation, Subros Limited, Robert Bosch GmbH, Brose Fahrzeugteile SE & Co. KG |
Frequently Asked Questions
Concerns about the high expense of navigating procedural complexities, Government Regulations are Strict are the main restraints of the Pancreatic and Biliary Stents market.
Prevalence has increased, and Endosonography and self-expanding metal stents (SEMS) are becoming more well-known are all propelling the Pancreatic and Biliary Stents market forward.
North America had the largest share of the Pancreatic and Biliary Stents market.
Boston Scientific Corp, Becton Dickinson and Co, ConMed Corp, Hobbs Medical Inc Medtronic Plc, and, Olympus Corp are the key players in the Pancreatic and Biliary Stents Market.
Ans: The Pancreatic and Biliary Stents market is to grow at US$ 4.7% over the forecast period 2024-2031.
