
Petrochemical Packaging Market Report Scope & Overview:
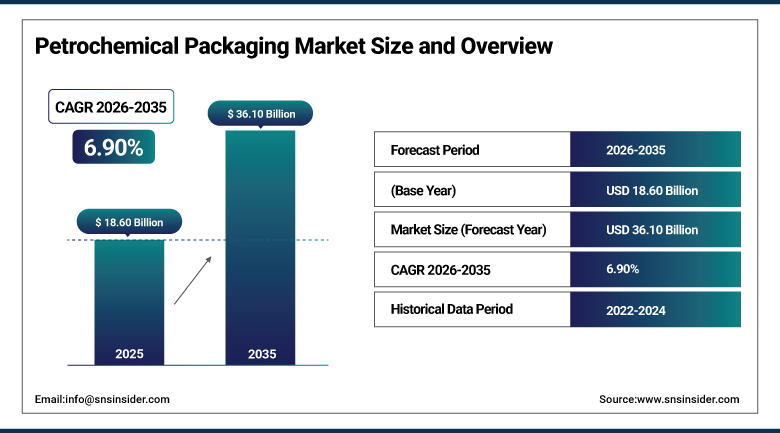
The Petrochemical Packaging Market was valued at USD 18.60 Billion in 2025 and is expected to reach USD 36.10 Billion by 2035, growing at a CAGR of 6.90% from 2026 to 2035.
The Petrochemical Packaging Market exists because petrochemicals themselves are genuinely difficult cargo, often flammable, corrosive, or reactive in ways that demand packaging engineered specifically to contain that risk rather than repurposed from more general industrial formats. Chemical applications alone account for nearly half of total demand, reflecting how directly this packaging category is tied to the broader health of chemical manufacturing and downstream processing industries worldwide. What is changing the category now is a shift toward specialty chemical packaging, higher-value derivatives used in electronics and pharmaceuticals that require more customized containment than bulk commodity petrochemicals ever did, alongside growing adoption of composite materials that combine plastic's chemical resistance with steel's structural durability.
Greif, Inc. entered into a partnership with Mauser Group in March 2025 in a bid to develop sustainable steel drums for the chemical industry that would make it easier to recycle and minimize costs.
To Get more information Petrochemical Packaging Market - Request Free Sample Report
Petrochemical Packaging Market Trends
- Specialty chemical packaging is expanding faster than commodity petrochemical formats as electronics and pharmaceutical demand grows.
- Composite materials combining plastic chemical resistance with steel structural strength are gaining share over single-material designs.
- Automated IBC production lines are shortening lead times for chemical producers scaling specialty formulation capacity.
- Reconditioning and closed-loop container fleet management are becoming standard practice among major industrial packaging suppliers.
- Regional manufacturing partnerships are expanding to secure packaging supply closer to key petrochemical production hubs.
The U.S. Petrochemical Packaging Market Outlook
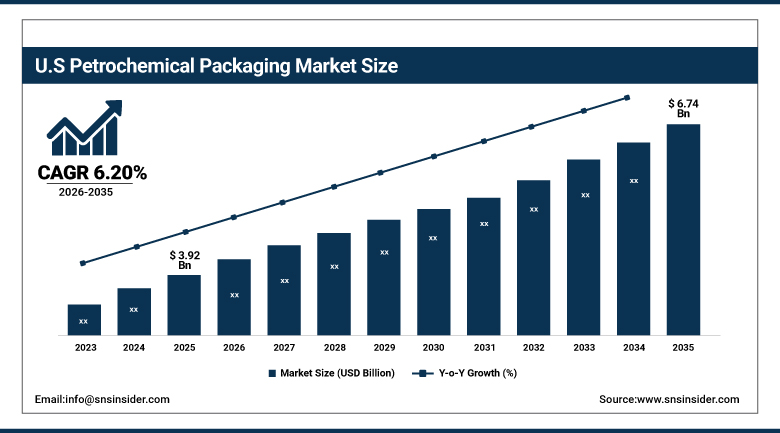
The U.S. Petrochemical Packaging Market was valued at USD 3.92 Billion in 2025 and is projected to reach USD 6.74 Billion by 2035, growing at a CAGR of 6.20% during 2026-2035.
The U.S. petrochemical packaging market is supported by the presence of petrochemical plants in the region along the Gulf Coast. There continues to be high demand for reliable IBCs, drums, and custom-designed packages that will be able to safely transport and store petrochemical materials that are hazardous, corrosive, and heat-sensitive. Packaging companies operating in the U.S. have been expanding their portfolio of services to include container repair, recycling, and fleet management in response to the need of petrochemical manufacturers to lower costs and increase efficiency. Compliance with regulations on packaging and transportation of hazardous materials favors the suppliers of UN-approved packages, certified documents, and tested designs.
In May 2025, Mauser Packaging Solutions introduced a new line of stainless steel IBCs in 125 to 550 gallon sizes, designed for demanding industrial and specialty chemical applications.
Petrochemical Packaging Market Segment Analysis
- By Application, polymers & resins dominates the petrochemical packaging market with polymers & resins holding 47.20% share in 2025 while specialty petrochemicals grows fastest registering a CAGR of 7.20% from 2026 to 2035.
- By Type, flexible packaging dominates the petrochemical packaging market with flexible packaging holding 54% share in 2025 while rigid packaging grows fastest registering a CAGR of 7.60% from 2026 to 2035.
- By Material, plastic dominates the petrochemical packaging market with plastic holding 58% share in 2025 while composite materials grow fastest registering a CAGR of 8.40% from 2026 to 2035.
- By Product Type, drums dominate the petrochemical packaging market with drums holding 36% share in 2025 while intermediate bulk containers grow fastest registering a CAGR of 7.80% from 2026 to 2035.
By Application, polymers & resins dominates the petrochemical packaging market while specialty petrochemicals grows fastest
Polymers & Resins holds 47.20% of the Petrochemical Packaging Market, the largest single category, reflecting how directly this packaging segment is tied to the sheer scale and diversity of chemical manufacturing, from basic industrial feedstocks to finished formulations moving through distribution. Established packaging specifications for this category have matured over decades, keeping demand steady and predictable regardless of shorter-term shifts in individual chemical product cycles.
The specialty petrochemical segment has the highest growth rate of 7.20% CAGR among all end-user applications due to increased need for specialized packaging from the electronics and pharmaceutical industry to preserve the quality of these high-value chemical derivatives that were never meant to be preserved by bulk commodity packaging. The increasing demand for such high-purity chemicals is further supporting this trend.
By Type, flexible packaging dominates the petrochemical packaging market while rigid packaging grows fastest
Flexible Packaging holds 54% of the market by type, the largest single category, valued for its cost-effectiveness and versatility in accommodating the wide range of petrochemical products and viscosities that move through modern chemical supply chains. Lower material use per unit of product shipped also gives flexible formats a genuine logistics cost advantage over rigid alternatives for many petrochemical applications.
Rigid Packaging is growing fastest by type, at a 7.60% CAGR, as bulk chemical producers increasingly favor drums and IBCs for their durability, reusability, and compatibility with reconditioning programs that reduce total packaging cost over a container's full service life. Growing emphasis on container fleet management across the chemical industry continues reinforcing this segment's above-average growth.
By Material, plastic dominates the petrochemical packaging market while composite materials grow fastest
Plastic holds 58% of the market by material, the largest single category, benefiting from its combination of chemical resistance, lower weight relative to steel, and cost efficiency across the wide range of petrochemical formulations that don't require metal's structural strength. High-density polyethylene in particular has become the standard resin for drum and IBC construction, resisting corrosion from aggressive solvents that would degrade lesser materials.
The Composite Materials segment is registering the fastest growth, at a CAGR of 8.40%, because chemical companies appreciate the advantage of designing containers with properties of both plastic's resistance to chemicals and the strength of steel in one single container. Composite IBC designs pairing a plastic inner bottle with a protective steel cage have become the industry standard for this hybrid approach, and continued adoption is reinforcing composite materials' above-average growth.
By Product Type, drums dominate the petrochemical packaging market while intermediate bulk containers grow fastest
Drums hold 36% of the market by product type, the largest single category, reflecting decades of established use across chemical manufacturing where drums remain the standard format for mid-volume liquid and solid petrochemical products. Extensive reconditioning infrastructure built around drum formats specifically gives this product type a genuine cost advantage that newer formats have not fully replicated.
Intermediate Bulk Containers are growing fastest, at a 7.80% CAGR, as bulk chemical producers increasingly favor IBCs for their volume efficiency and reusability, reducing per-unit packaging and handling costs on high-volume shipments compared to smaller-format drums. Automated IBC production lines that shorten manufacturing lead times are reinforcing this segment's above-average growth as producers scale specialty formulation capacity.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.00% |
|
Asia Pacific |
China |
36.40% |
|
Europe |
Germany |
25.20% |
|
Middle East & Africa |
UAE |
18.60% |
|
Latin America |
Brazil |
26.40% |
North America Petrochemical Packaging Market Insights
North America's petrochemical packaging market is mature and steady, supported by a well-established petrochemical industry and advanced logistics infrastructure concentrated along the U.S. Gulf Coast. The region accounted for approximately 24.80% of the global Petrochemical Packaging Market in 2025, and growth here, registering a CAGR of 6.50% during 2026-2035, comes mostly from formulation upgrades and reconditioning capacity expansion rather than first-time adoption, since petrochemical packaging has been standard industrial practice across the region for decades.
The United States accounts for approximately 85.00% of the North American market, reflecting its concentration of petrochemical manufacturing and industrial packaging infrastructure. Canada and Mexico both contribute smaller shares, with Mexico's growing manufacturing base increasingly attracting packaging investment tied to nearshoring trends.
Europe Petrochemical Packaging Market Insights
Europe's petrochemical packaging market is mature and shaped heavily by the EU Packaging and Packaging Waste Regulation, which is pushing converters toward recycled content and reusable container designs faster than in most other regions. Strong chemical manufacturing traditions across the region continue supporting steady demand even as growth in absolute volume terms remains more measured than in faster-expanding regions.
Germany leads the European market with a 25.20% share, supported by its large chemical manufacturing base and advanced packaging engineering industry. France and the United Kingdom follow, with demand in both countries tied to established petrochemical manufacturing and distribution sectors.
Asia Pacific Petrochemical Packaging Market Insights
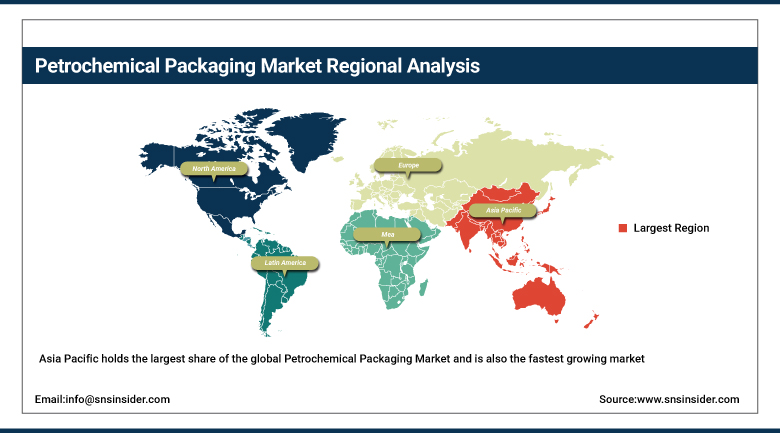
Asia Pacific holds the largest share of the global Petrochemical Packaging Market and is also the fastest growing market, driven by the growing transportation of petrochemicals and dangerous synthetics across the region's massive manufacturing base. China's scale of petrochemical production alone accounts for a large part of that lead, while India's expanding chemical manufacturing sector is adding further meaningful demand as domestic production capacity continues scaling.
China holds roughly 36.40% of the regional market, supported by its dominant position as the world's largest petrochemical producer and exporter. India is growing quickly as domestic chemical production capacity expands, while Japan and South Korea contribute through their established, quality-focused specialty chemical manufacturing sectors.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa and Latin America Petrochemical Packaging Market Insights
Regionally, the Middle East & Africa region is showing the steady growth rate due to increasing capacities of petrochemicals in the Gulf states and the fact that this region is one of the biggest exporters of both raw and processed petrochemicals. The Middle East & Africa region contributed around 7.10% to the total global market of the Petrochemical Packaging market in 2025, which may be less compared to the other well-established regions, yet it is growing rapidly.
In the Middle East & Africa region, the UAE is the leading country having the market share of 18.60% due to its importance as an export hub of petrochemicals. In Latin America, Brazil has a 26.40% share in the market because of its chemical manufacturing base, while Mexico has made contributions through nearshoring packaging investments.
Market Dynamics
Growth Drivers: Petrochemical Production Growth and Specialty Chemical Demand Fueling Market Growth
Expanding petrochemical production capacity, particularly across Asia and the Middle East, is the clearest driver behind this market's growth, as new production capacity almost always translates into new packaging requirements for both raw materials and finished derivatives. Growing demand for specialty chemicals in electronics and pharmaceutical applications is reinforcing this trend, since these higher-value products require more sophisticated, customized packaging than bulk commodity chemicals.
Tightening hazardous materials regulation is adding a further layer of demand stability, as compliant, well-documented packaging becomes less of a discretionary quality choice and more of a genuine market-access requirement for petrochemical producers and distributors.
Restraints: Raw Material Price Volatility and Reconditioning Infrastructure Gaps Limiting Market Expansion
Resin and steel price volatility, tied to broader petrochemical and metal commodity markets, makes it difficult for packaging manufacturers to hold pricing steady with chemical industry customers on long-term supply contracts. Reconditioning infrastructure remains geographically uneven, with well-developed depot networks in mature markets but limited capacity in several emerging regions, which restricts how widely the cost benefits of container reuse can actually be captured.
Transportation costs for empty and reconditioned containers add further complexity, since petrochemical packaging tends to be bulky relative to its value, making regional supply chain efficiency a meaningful factor in overall packaging economics.
Opportunities: Composite Material Innovation and Regional Manufacturing Expansion Creating New Growth Avenues
There is indeed an opportunity for innovation in composite materials as more chemical companies come to appreciate the benefits of using one container which is both chemically resistant and durable at the same time. Composite manufacturers who will be able to produce these materials safely and receive UN dangerous goods certification will benefit from this trend.
Regional manufacturing expansion offers a second clear opportunity, particularly as chemical producers seek to reduce supply chain exposure to global trade disruptions by securing local or regional packaging supply rather than depending entirely on imports.
Recent Developments:
- 2026: Schütz GmbH & Co. KGaA and BASF SE signed an agreement to build an automated IBC production and storage facility at BASF's main plant in Ludwigshafen, Germany.
- 2025: Schütz GmbH & Co. KGaA and National Plastic Factory Company signed a long-term license agreement for IBC production in Saudi Arabia, expanding the company's regional manufacturing footprint.
- 2024: Greif, Inc. and CDF Corporation collaborated to launch a redesigned IBC specifically engineered for transporting sterile pharmaceutical and specialty chemical products.
- 2024: Greif, Inc. expanded its global manufacturing presence with a new IBC production facility in Malaysia, strengthening its footprint across the Asia-Pacific petrochemical packaging market.
Petrochemical Packaging Market key players are:
- Greif, Inc.
- Mauser Packaging Solutions
- SCHÜTZ GmbH & Co. KGaA
- Balmer Lawrie & Co. Ltd.
- Time Technoplast Ltd.
- TPL Plastech Ltd.
- Mondi Group
- Amcor plc
- Sonoco Products Company
- Industrial Container Services, LLC
- Ampac Holdings, LLC
- Environmental Packaging Technologies, Ltd.
- Rak Petropack
- New Pig Corporation
- Snyder Industries, LLC
- CDF Corporation
- Great Western Containers Inc.
- VTIC Thielmann Group
- Krishna Containers Private Limited
- Skolnik Industries, Inc.
Petrochemical Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.60 Billion |
| Market Size by 2035 | USD 36.10 Billion |
| CAGR | CAGR of 6.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Application (Polymers & Resins, Solvents, Specialty Petrochemicals, Petrochemical Derivatives, Others) • By Type (Flexible Packaging, Rigid Packaging) • By Material (Plastic, Metal, Composite, Others) • By Product Type (Drums, Intermediate Bulk Containers, Bags & Sacks, Bottles, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Greif, Inc., Mauser Packaging Solutions, SCHÜTZ GmbH & Co. KGaA, Balmer Lawrie & Co. Ltd., Time Technoplast Ltd., TPL Plastech Ltd., Mondi Group, Amcor plc, Sonoco Products Company, Industrial Container Services, LLC, Ampac Holdings, LLC, Environmental Packaging Technologies, Ltd., Rak Petropack, New Pig Corporation, Snyder Industries, LLC, CDF Corporation, Great Western Containers Inc., VTIC Thielmann Group, Krishna Containers Private Limited, Skolnik Industries, Inc. |
Frequently Asked Questions
Key players include Greif, Inc., Mauser Packaging Solutions, SCHÜTZ GmbH & Co. KGaA, Balmer Lawrie & Co. Ltd., Time Technoplast Ltd., TPL Plastech Ltd., Mondi Group, and Amcor plc, alongside other established industrial packaging manufacturers.
Key opportunities include composite material innovation combining chemical resistance with structural durability, regional manufacturing expansion to reduce supply chain exposure, and growing specialty chemical demand requiring customized containment solutions.
The market is driven by expanding petrochemical production capacity, growing demand for specialty petrochemicals in electronics and pharmaceuticals, and tightening hazardous materials regulation.
The Polymers & Resins segment dominated the Petrochemical Packaging Market in 2025.
The Asia Pacific region dominated the Petrochemical Packaging Market in 2025, driven by the growing transportation of petrochemicals across the region's massive manufacturing base.
