
Philippines GCC Market Report Scope and Overview
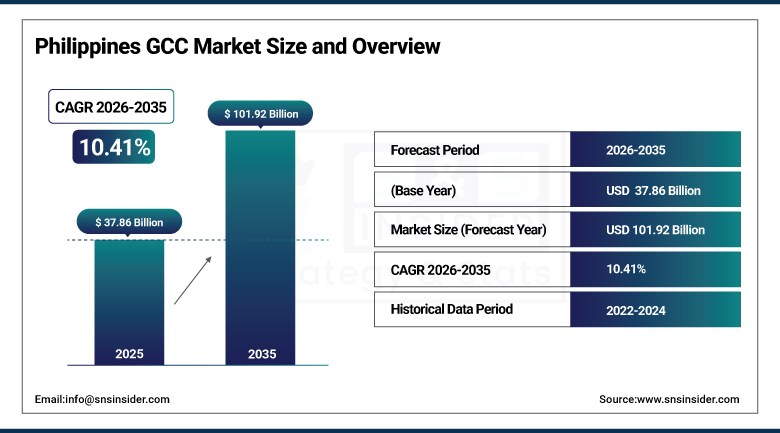
The Philippines GCC Market was valued at USD 37.86 Billion in 2025 and is estimated at USD 41.80 Billion in 2026. The market is forecast to reach USD 101.92 Billion by 2035, registering a CAGR of 10.41% from 2026 to 2035. Growth reflects the move of multinational enterprises from outsourced contact work to owned centers that run finance, technology, analytics, and engineering mandates, together with a supportive incentive regime and a deep English-speaking talent base. Metro Manila accounted for the largest regional share at 57.84% in 2025, while Central Visayas, anchored by Cebu, is expected to expand fastest.
To Get more information Philippines GCC Market - Request Free Sample Report
Key Market Trends & Insights
-
By function: Business process management held the largest market share of 56.92% in 2025.
-
By engagement model: Captive centers held the largest market share of 57.63% in 2025.
-
By industry vertical: Telecom and IT held the largest market share of 31.84% in 2025.
-
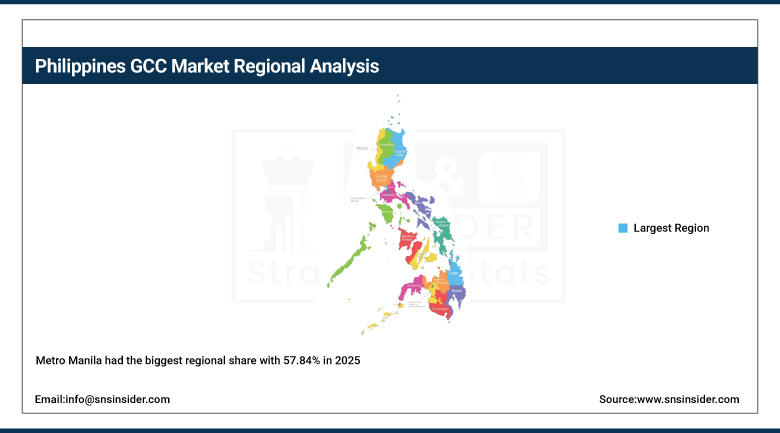
Metro Manila accounted for the largest regional share of 57.84% in 2025.
-
Central Visayas is projected to register the fastest regional CAGR of 12.34% from 2026 to 2035.
-
Makati City and Taguig remain the leading business districts, while provincial hubs gain share as multinationals look beyond the capital.
Growth Outlook
Tax and work arrangements have become more favorable for owned centers. In February 2025, the Department of Finance and the Department of Trade and Industry signed the implementing rules of the CREATE MORE Act, which allow investment promotion agencies to permit registered locators to run up to 50.00% of their workforce from home. Companies can also move their registration between investment promotion agencies, and more than 440 firms had applied to shift from the economic zone authority to the Board of Investments by the time the rules were released. These terms lower operating cost and widen site choice, which suits centers that need flexible hiring.
Real estate policy is also easing. In July 2026, the President lifted a seven-year freeze on new information technology parks and centers in Metro Manila through Administrative Order No. 45, series of 2026, and the economic zone authority said developers can again register qualified office buildings. Occupiers gain access to modern space in established districts that sit close to talent, transport, and financial institutions. The change widens the supply that new centers can choose from, and it supports expansion of existing locators that had been constrained by limited zone-registered space. Developers have already begun to prepare projects that fit the revised rules.
Market Dynamics
Driver: Multinationals Shift From Outsourced Services to Owned Centers With Wider Mandates
Companies that began with outsourced contact work in the Philippines are now building their own centers for finance, technology, analytics, and shared services. In September 2025, the Information Technology and Business Process Association of the Philippines (IBPAP) reported about 170 global capability centers in the country, up from 150 less than two years earlier, and projected 2026 industry revenue of USD 42.00 Billion with 1.97 million workers. Owned centers give firms tighter control of data, quality, and talent, and the Philippines offers a large English-speaking workforce with long experience in regulated work such as banking and healthcare operations. Time zone alignment with North America, Australia, and parts of Europe also allows teams to hand work across the day without delay, which large operators value for continuity.
Industry results show the base that these centers draw on. In January 2026, IBPAP reported that the sector closed 2025 with revenue of about USD 40.00 Billion and about 1.90 million workers, equal to more than 8.00% of national output, and named growth of global capability centers as a priority for 2026. Banks, insurers, healthcare groups, and retailers from the United States, Australia, and Europe are the main sources of new interest, and large employers already in the country continue to add staff. A deep pool of experienced managers also lets new centers staff leadership roles locally. Wage levels that remain competitive against other offshore locations help firms justify further investment, and long tenure among team leaders supports quality in complex processes.
Restraint: Artificial Intelligence, Talent Gaps, and Regional Competition Moderate Growth
Automation is changing the volume of routine work that supports the industry. In July 2026, IBPAP revised its 2028 roadmap and cut its targets because of rapid adoption of artificial intelligence and stronger global competition. The earlier plan pointed to USD 59.00 Billion in revenue and 2.50 million workers, while the revised range runs from USD 43.30 Billion and 1.85 million workers in the downside case to USD 50.50 Billion and 2.14 million workers in the best case. Slower headcount growth lowers the pace at which transaction-heavy centers expand, and it puts weight on moving staff into higher-value roles. Cost pressure from rising wages is already visible in the capital, and it can push lower-value work toward other locations.
Cost constraints and capacity restrictions put further stress on the decision-making process. Other destination countries like India, Poland, and Latin America have more abundant engineering resources and center ecosystem in place, and in some cases, firms divide their mandates across multiple locations. In terms of the Philippines, high demand for technology and analytics personnel increases salary levels in Metro Manila, and premium office space in existing centers becomes constrained. It is imperative that buyers consider the availability of human resources, reliable supply of electricity and Internet, and local training capabilities prior to scaling up to sizeable staffing levels. Smaller firms with limited internal expertise can also struggle with registration steps, labor rules, and data privacy duties, which lengthens the time needed to start operations.
Opportunity: Small Specialist Centers and Provincial Hubs Widen the Addressable Base
Many companies that once found a full center too large a commitment are now opening nano and micro units focused on analytics, engineering, risk, or product work. These teams can start with a few dozen people and grow in steps, often through build-operate-transfer arrangements in which a partner handles hiring, premises, and compliance before the client takes over. The approach lowers entry cost for mid-sized firms and lets large groups test new functions quickly, and it gives service partners a recurring role in setup, talent sourcing, and managed operations. Partners that bundle recruitment, premises, payroll, and compliance into one offer can serve this fast-growing group of buyers.
Provincial cities form a second opportunity. Centers outside Metro Manila gain from lower rents, new office supply, and large graduate pools in Cebu, Davao, Iloilo, Bacolod, and the Clark area. Republic Act No. 12234, or the Konektadong Pinoy Act, was signed into law in August 2025, making it possible for data transmitters to operate without having a franchise. It increases competition within the connectivity sector. Good connections help narrow down the difference between capital and provincial locations and ensure that business continuity plans are kept operational across several cities. Local governments are providing additional incentives such as trainings and facilities, thus making it attractive to be an early mover in each city. Universities in provincial cities are aligning curricula with employer needs in data, software, and finance.
Market Characteristics & Concentration
The Philippines GCC Market is Moderately Fragmented. Global banks, insurers, and technology groups run large owned centers, while outsourcing firms operate shared and managed models for clients that prefer not to build. No single operator holds a majority of activity, and the concentration of work in a few districts of Metro Manila means that landlords, zone operators, and training institutions shape the competitive field as much as the operators themselves. Smaller operators focus on one function or industry, which gives buyers a range of options.
The level of merger and acquisition activity is low. Growth comes mainly through new center openings, expansion of existing sites, and build-operate-transfer handovers rather than acquisitions. Entry depends on incentive registration, labor and data privacy compliance, and the choice of site, and these requirements favor operators with local experience and established relationships with investment agencies and universities. Operators that expand carefully and keep strong client ties tend to hold their positions, because relocation of an established center is costly and slow for the parent company.
Expansion follows a pattern in which firms enter Metro Manila first and then add provincial sites for resilience and cost. Headquarters in the United States, Australia, Europe, and Japan shape scope, with banking, healthcare, and retail groups leading, and each new mandate adds to the demand for managers, engineers, and analysts that local training programs must supply. Provincial growth follows the same pattern, and success there depends on training links with local universities and the readiness of nearby infrastructure.
Analyst Perspective
The Philippines is moving from a place where companies locate outsourced work to a place where they own and steer it. Buyers no longer judge the country only by cost per seat. They look at whether a center can run finance, analytics, and engineering with strong governance and a stable talent supply. Operators that combine incentive planning, provincial expansion, and workforce programs that lift skills in artificial intelligence and data will capture the largest share of new mandates through 2035. Policy support and the shift toward owned centers will widen the buyer base. An SNS Insider Analyst, Santosh Bhul, commented, "Global firms will keep choosing the Philippines when they can build capable teams quickly and keep control of their most sensitive work."
Segment Analysis
Function Insights
Business process management accounted for the largest share of 56.92% in 2025. Finance and accounting, human resources, customer operations, and claims processing form the base of activity, and they run on skills that the Philippines has built over two decades. Owned centers keep these processes close to the parent company while using lower-cost talent, and many firms are now adding analytics and automation layers on top of established workflows. Because the work is steady and recurring, it provides the revenue base that funds expansion into newer functions across the same sites and teams. Process owners at the parent company also keep tight reporting lines to these teams.
IT and digital services are projected to experience the highest growth rate of 11.87%. This is because software engineering, cloud operations, cyber security, data engineering, and artificial intelligence have been included in the recent mandates, and the multinational corporations utilize manpower in Manila and Cebu to increase their capabilities next to their other major technology centers. High salaries for these positions will result in higher earnings per employee, while training and employment academies will be providing more engineers and analysts. The service partners will also enable quick recruitment in the newly established centers. Managers also report that technology hires stay longer when they work on global products.
Engagement Model Insights
Captive centers held the largest share of 57.63% in 2025. Large banks, insurers, energy companies, and retailers prefer to own their centers so they can control data, quality, and culture. For example, large banking groups continue to add thousands of staff each year, according to the industry association. Captives allow firms to move sensitive work, such as risk and treasury operations, into the country, and they offer leaders a long-term base from which to scale teams as mandates widen. Parent companies also gain direct oversight of costs, hiring standards, and service levels, and they can move work between sites in the same network as needs change over time.
Build-operate-transfer hybrids are projected to expand at the fastest CAGR of 12.18% from 2026 to 2035. A partner sets up the center, hires and trains staff, manages premises and compliance, and then hands ownership to the client when operations are stable. The model suits mid-sized firms with no prior presence in the country, and it shortens the time to first hire. Clients keep the option to buy out the operation, and partners earn fees during the build phase, which creates a steady pipeline of new small centers across Metro Manila and provincial cities. Handover terms are negotiated early, which gives both sides clarity on staffing, systems, and costs.
Industry Vertical Insights
Telecom & IT occupied the largest share of 31.84%, as these sectors were amongst the first ones to purchase the services of the Philippines. They perform functions such as technical support, network operations, product operations, and software-related tasks and have a huge number of employees. They require constant coverage in different time zones and have people who work with clients from the USA and Australia. Their contracts are long-term and they are shifting to engineer and platform positions due to reduced support volume via automation.
The BFSI vertical is anticipated to have the highest CAGR of 12.04% during 2026-2035. The banks, insurers, and asset management firms are taking their risk management, compliance management, treasury management, and IT operations to captive centers, and the Philippines has become the favorite choice due to its high regulatory knowledge and a high number of finance professionals. Digital banking, fraud analytics, and data analytics increase the professional content of the captive centers. Increasing compliance regulations in the global banking industry have compelled the companies to maintain their operations in captive environments, aiding in captive center growth.
Regional Insights
Metro Manila had the biggest regional share with 57.84% in 2025. The National Capital Region is home to important business districts of Makati, Taguig, Ortigas, and Quezon City where financial firms and technology companies gather close to their sources of labor, logistical network, and banks. Due to the established economic zones, efficient management, and experience in operations, the region is always the top priority when it comes to establishing new hubs due to their expensive rents and shortage of prime spaces that compels some mandates to go provincial cities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Calabarzon Philippines GCC Market
Calabarzon accounted for 7.43% of the market in 2025, with centers in Laguna, Cavite, and Batangas that serve firms looking for lower rents within reach of Metro Manila. Economic zones and science parks in the region host engineering, shared services, and technology operations, and the area draws workers from several large universities. Commuting links to the capital are still a constraint, and operators place centers close to residential areas to improve retention, which supports a steady flow of mid-sized centers. Proximity to the capital also helps firms keep leadership teams in Metro Manila while larger teams work nearby.
Central Luzon Philippines GCC Market
Central Luzon had 7.75% share of the market in 2025, mainly because of Clark and the entire Pampanga region, which is equipped with freeport facilities, international airport, and high-rises offices, making it ideal for BPOs seeking to operate independently of traffic problems in Metro Manila. The availability of consistent electricity supply, big land spaces, and relatively lower cost of operations are among the features that attract operators, with both captive and outsourcing centers present. Government efforts to market the area to investors also support site selection by firms seeking space away from the capital.
Central Visayas Philippines GCC Market
Central Visayas is projected to register the fastest regional CAGR of 12.34% from 2026 to 2035, and the region held 13.07% of the market in 2025. Cebu is the main hub and the leading provincial destination for information technology and business process work. It was recorded in September 2025 by IBPAP that there were inquiries regarding places outside Metro Manila by some centers. The huge number of graduates, presence of an international airport, and the way of life that helps in retention makes the region good for captive centers. Schools in the region also have programs that provide graduates trained in software and business services.
Western Visayas Philippines GCC Market
Western Visayas accounted for 6.12% of the market in 2025, with Iloilo and Bacolod as the main hubs. Lower rents, a strong supply of graduates, and local government support attract outsourcing firms and a growing number of captive support centers. Business parks in both cities have added new towers in recent years, and operators use the region for voice, back office, and early-stage technology work before moving higher-value functions. Limited flight links and a smaller management pool remain constraints on larger mandates. Local officials also work with employers to align training with hiring needs.
Mindanao Philippines GCC Market
Mindanao held 7.79% of the market in 2025, led by Davao and Cagayan de Oro, which host outsourcing operations and a rising number of support centers. Davao offers a large student population, lower costs, and a local government that supports information technology investment. Companies treat Mindanao as a second site that adds resilience and access to new talent, and as links and digital infrastructure improve, the region is expected to add centers focused on customer operations, finance support, and software testing. Regional universities also supply graduates in engineering and business fields.
Key Philippines GCC Market Company Insights
Companies operating owned centers in the Philippines are broadening mandates from back office and contact work toward analytics, engineering, risk, and product support. Large banks and energy groups lean on scale and long operating records, while newer entrants use build-operate-transfer partners to enter quickly and expand in steps.
Key Philippines GCC Companies:
-
JPMorgan Chase and Co.
-
HSBC Global Service Centre Philippines
-
Citigroup Global Markets Asia Service Center
-
Chevron Holdings Inc.
-
Wells Fargo
-
Asurion
-
Carelon Global Solutions
-
Philtech Inc. (Albertsons Companies)
Recent Developments
-
In May 2026, GCC Forum 2026, co-hosted by KMC Solutions and Asia CEO, drew executives from Carelon Global Solutions and RELX to discuss nano and micro center models.
-
In February 2026, SM Offices announced more than 60,000 square meters of new leasable office space in Cebu City for occupancy by the fourth quarter of 2026.
-
In 2025, Wells Fargo, Asurion, and EY expanded their owned centers in Cebu.
-
In September 2025, JPMorgan Chase was reported to be adding thousands of staff each year in the Philippines with a planned 10.00% headcount rise for 2026.
-
In June 2025, Albertsons Companies, through its capability center Philtech Inc., and Ascendion launched an artificial intelligence focused global capability center in Cebu.
Scope and Research Methodology
The study defines the Philippines GCC Market as the revenue generated by owned, hybrid, and partner-operated global capability centers located in the Philippines that deliver business process, technology, knowledge, and engineering services to their parent organizations and affiliates. Centers serving only the home market, pure third-party outsourcing contracts with no parent link, and general contact center volumes without an enterprise ownership relationship are outside the scope. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The segmentation covers function, engagement model, industry vertical, and region, with regions defined by Philippine administrative groupings. Leading cities and provinces within each region are covered in the analysis, and revenue is attributed to the location where staff are employed.
The research program combines secondary and primary research. Secondary research draws on company annual reports and filings, government and economic zone authority releases, investment agency statistics, trade association data, labor and education statistics, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with center heads, site leaders, human resources and real estate executives, service partners, and investment promotion officials. These discussions validate assumptions on headcount, cost per employee, mandate expansion, and engagement models, and responses are weighted by the seniority and relevance of each respondent.
Market engineering follows a bottom-up build from center counts, headcount, and revenue per employee, cross-checked top-down against national outsourcing industry output and services trade data. Triangulation across both approaches narrows differences before values are finalized. Forecasts reflect drivers such as incentive policy, talent supply, technology adoption, and regional competition, and every estimate passes through an analyst quality review that tests consistency across segments, regions, and years. Sensitivity checks test the effect of changes in headcount growth, wage levels, and automation, and regional estimates are aligned so that every regional value adds to the national total.

Frequently Asked Questions
The market was valued at USD 37.86 Billion in 2025 and is projected to reach USD 101.92 Billion by 2035.
The market is expected to register a CAGR of 10.41% from 2026 to 2035.
Metro Manila led the market with a 57.84% share in 2025.
Central Visayas is expected to grow the fastest, at a CAGR of 12.34% from 2026 to 2035.
Business process management led the function segment with a 56.92% share in 2025, and captive centers led the engagement model segment.
Key players include JPMorgan Chase and Co., HSBC Global Service Centre Philippines, Citigroup Global Markets Asia Service Center, Chevron Holdings Inc., and Wells Fargo.
