
Phospholipids & Lecithin Market Report Scope & Overview:
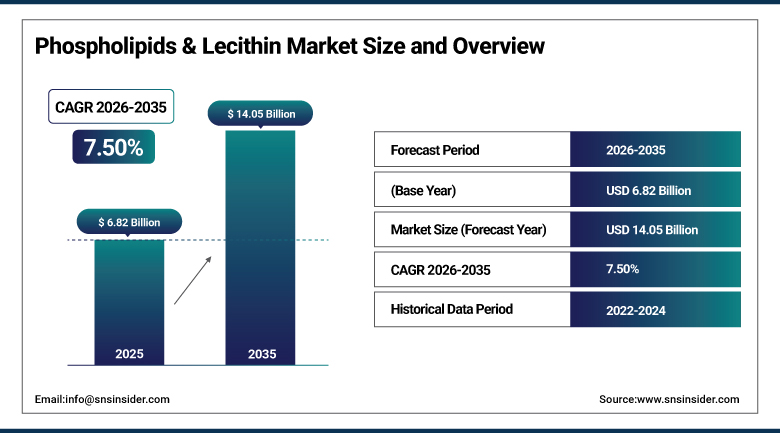
The Phospholipids & Lecithin Market was valued at USD 6.82 Billion in 2025 and is expected to reach USD 14.05 Billion by 2035, growing at a CAGR of 7.50% from 2026 to 2035.
Lecithin has one of the more understated origin stories in the food ingredient world, it is largely a byproduct recovered during vegetable oil refining, phospholipid gums skimmed off crude soybean or sunflower oil before it is further processed, that turns out to be an exceptionally versatile emulsifier, stabilizer, and increasingly a bioactive ingredient in its own right. That byproduct relationship has kept lecithin cost-competitive even as demand has expanded well beyond its traditional chocolate and baked goods applications into pharmaceuticals, cosmetics, and nutraceuticals. High-purity phosphatidylcholine fractions in particular have become essential to liposomal drug delivery systems and parenteral emulsions, where biocompatibility and reproducible quality genuinely matter for patient safety, a use case that barely existed for lecithin a generation ago.
In June 2025, Lipoid GmbH announced a strategic collaboration with BASF SE to expand plant-based phospholipid production capacity, supporting rising demand in infant nutrition and plant-based food formulations.
To Get more information Phospholipids & Lecithin Market - Request Free Sample Report
Phospholipids & Lecithin Market Trends
-
Non-GMO and organic soy and sunflower lecithin variants are gaining share as clean-label expectations spread across food categories.
-
High-purity phosphatidylcholine fractions are expanding rapidly for liposomal drug delivery and parenteral pharmaceutical applications.
-
Sunflower lecithin is capturing share from soy lecithin among allergen-conscious food and cosmetics formulators.
-
Cosmetics and personal care applications are growing quickly as lecithin's emulsifying and skin-penetration properties gain formulator attention.
-
Vertical integration from oilseed crushing through fractionation is becoming a key competitive advantage for pricing power and supply chain transparency.
U.S. Phospholipids & Lecithin Market Outlook
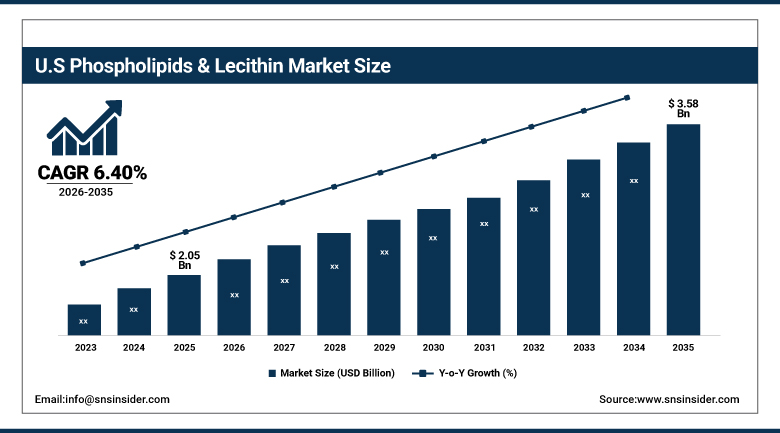
The U.S. Phospholipids & Lecithin Market was valued at USD 2.05 Billion in 2025 and is projected to reach USD 3.58 Billion by 2035, growing at a CAGR of 6.40% during 2026-2035.
Domestic soybean processing scale gives the U.S. a genuine cost and supply advantage in lecithin production, since the ingredient is recovered directly from oil refining operations that the country's massive soybean crushing industry already runs at scale. Clean-label reformulation continues reshaping product development, with major manufacturers increasingly launching non-GMO and organic-certified lecithin variants to meet health-conscious consumer demand across both mature and emerging food categories. Pharmaceutical-grade phospholipid demand has been a particularly strong growth line domestically, as biopharmaceutical manufacturers increasingly rely on high-purity phosphatidylcholine fractions for liposomal drug delivery systems and mRNA vaccine stabilization. Growing interest in plant-based cosmetics formulations is also expanding lecithin's role beyond food and pharmaceutical applications into skincare and personal care products.
In July 2025, Archer Daniels Midland Company secured a major supply contract with a global dairy and cereal producer to provide high-purity soy and sunflower lecithin for spreads and bakery product formulation.
Phospholipids & Lecithin Market Segment Analysis
-
By Source, Soy segment dominated the Phospholipids & Lecithin Market in 2025 with 80% share; Sunflower segment is the fastest-growing segment, registering a CAGR of 8.60% from 2026 to 2035.
-
By Type, Fluid segment dominated the market in 2025 with 52% share; Modified segment is the fastest-growing segment, registering a CAGR of 8.80% from 2026 to 2035.
-
By Application, Food & Beverages segment dominated the market in 2025 with 44% share; Cosmetics & Personal Care segment is the fastest-growing segment, registering a CAGR of 9.20% from 2026 to 2035.
-
By Function, Emulsifiers segment dominated the market in 2025 with 41.20% share; Stabilizers & Antioxidants segment is the fastest-growing segment, registering a CAGR of 8.40% from 2026 to 2035.
By Source, Soy Leads the Phospholipids & Lecithin Market While Sunflower Gains Ground Fastest
Soy holds an overwhelming 80% of the Phospholipids & Lecithin Market by source, reflecting the sheer scale of global soybean processing and the fact that lecithin is essentially recovered as a byproduct of oil refining that the soybean crushing industry already runs at massive volume. That byproduct relationship gives soy lecithin a genuine cost advantage over sources requiring dedicated extraction processes, keeping it the default choice across the vast majority of food, industrial, and lower-tier cosmetic applications.
Sunflower is growing at an 8.60% CAGR, the fastest pace among sources, as allergen-conscious food and cosmetics formulators increasingly favor it as a genuinely allergen-free alternative to soy, which remains one of the most common food allergens globally. Growing consumer preference for non-GMO ingredients has reinforced this shift, since sunflower lecithin does not carry the same genetic modification concerns that soy-derived products sometimes face among certain consumer segments.
By Type, Fluid Dominates While Modified Emerges as the Fastest-Growing Type
Fluid lecithin accounts for 52% market share by type, being the predominant commoditized product primarily owing to its minimal requirement for post-extraction processing, thus resulting in lower costs relative to de-oiled and modified variants. This product is applicable in most food and industrial uses of lecithin where emulsification capabilities matter much more than specific purity levels.
Modified and phospholipid-based products are witnessing the highest growth at a 8.80% CAGR, due to increasing pharmaceutical applications as well as functional foods needing specific purity of phosphatidylcholine fractions, which cannot be supplied through regular fluid or de-oiled lecithin. Injectable grade phospholipids with greater than 99% purity needed for liposomal drug delivery and parenteral emulsions are the premium end products of this segment, generating higher margins than commoditized lecithins.
By Application, Food & Beverages Dominates While Cosmetics & Personal Care Registers the Fastest Growth
Food & Beverages accounts for 44% of application demand, the largest single category, reflecting lecithin's deep-rooted role as an emulsifier across chocolate, baked goods, margarine, and a wide range of processed food products where texture and shelf stability depend on reliable emulsification. Growing consumption of mayonnaise, hollandaise-style sauces, and similar emulsified condiments continues reinforcing this category's lead.
Cosmetics & Personal Care is the fastest-growing application, expanding at a 9.20% CAGR, as lecithin's properties as an emulsifier, moisturizer, and skin-penetration enhancer gain increasing attention from formulators developing natural and plant-based beauty products. Lecithin-based emulsions have demonstrated dramatic solubility improvements for certain active ingredients in topical formulations, a functional benefit that is opening genuinely new product development possibilities beyond lecithin's traditional food and pharmaceutical applications.
By Function, Emulsifiers Dominates While Stabilizers & Antioxidants Registers the Fastest Growth
Emulsifiers account for 41.20% of the market by function, the largest single category, reflecting lecithin's fundamental and most widely recognized role in keeping oil and water-based ingredients stably combined across food, pharmaceutical, and cosmetic formulations. This functional versatility across such a broad range of industries is exactly what has kept emulsification the anchor use case for lecithin despite the ingredient's expanding role in other functional categories.
Stabilizers & Antioxidants is the fastest-growing function, expanding at an 8.40% CAGR, as manufacturers increasingly value lecithin's natural antioxidant properties for extending shelf life in functional foods and nutraceuticals without relying on synthetic preservative compounds. This natural antioxidant positioning aligns well with broader clean-label trends, giving lecithin suppliers a genuine functional selling point beyond emulsification alone.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
86.20% |
|
Asia Pacific |
China |
34.60% |
|
Europe |
Germany |
25.80% |
|
Middle East & Africa |
UAE |
17.30% |
|
Latin America |
Brazil |
27.40% |
North America Phospholipids & Lecithin Market Insights
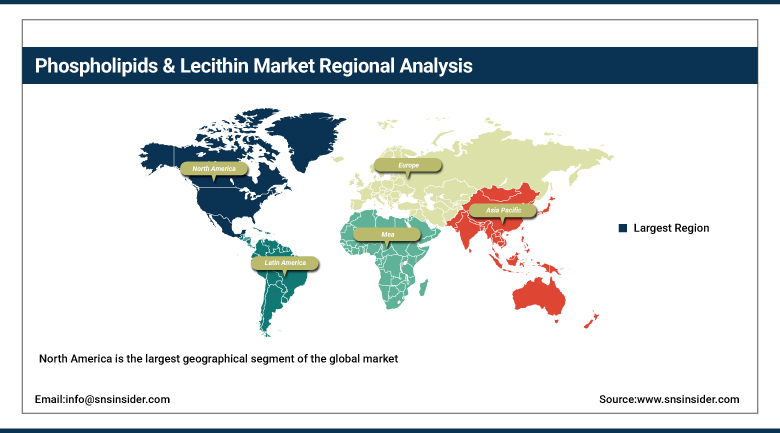
North America is the largest geographical segment of the global market of Phospholipids & Lecithin Market because of the huge capacity of soybean extraction plants present in this region, along with the rising demand for natural, functional ingredients in foods, pharmaceuticals and cosmetics. Rising consumption of pharmaceutical grade phospholipids, especially for liposomal drug delivery systems, is creating momentum for the market which otherwise is a very mature and stable one.
United States constitutes roughly 86.20% of the market size of North America due to the presence of large capacity of soybean crushing and oil extraction units in this country.
 '
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Phospholipids & Lecithin Market Insights
Asia Pacific is growing faster than any other region in this market, driven by technological advancements in extraction processes that are improving product quality and efficiency across the region's expanding oilseed processing industry. Rising health and wellness awareness, combined with growing food, pharmaceutical, and cosmetics manufacturing capacity, continues expanding demand across China, India, and Southeast Asia.
China holds roughly 34.60% of the regional market, supported by its expanding oilseed processing base and growing pharmaceutical and cosmetics manufacturing sectors. India and Southeast Asian markets are growing quickly as food processing and nutraceutical manufacturing both expand, while Japan contributes through its established, quality-focused functional food and cosmetics industries.
Europe Phospholipids & Lecithin Market Insights
The European phospholipids and lecithin market is a mature one, driven by a robust regulatory environment which supports the use of lecithin as a food and feed ingredient since EFSA confirmed that lecithin is safe for consumption by all animal species without any maximum usage restrictions. The growing consumer preference for natural/organic products further fuels growth in this market, especially for non-GMO soy/sunflower lecithins.
In Europe, Germany accounts for 25.80% share of the market, driven by the presence of food manufacturers and pharmaceutical ingredients manufacturing in this country. After Germany, France and the United Kingdom are the next most important markets for phospholipids and lecithin with the demand coming from food, pharmaceutical, and cosmetic manufacturing.
Middle East & Africa and Latin America Phospholipids & Lecithin Market Insights
The Middle East & Africa region is growing steadily as food and pharmaceutical manufacturing both expand across the Gulf states, supported by rising investment in modern food processing infrastructure. Latin America's growth follows a similar arc, driven by Brazil's substantial soybean processing industry and growing regional demand for functional food and pharmaceutical ingredients.
The UAE leads the Middle East & Africa market with a 17.30% share, supported by its role as a regional food and pharmaceutical ingredient distribution hub. Brazil represents 27.40% of the Latin American market, reflecting its position as one of the world's largest soybean processors, with Argentina also contributing through its significant oilseed processing capacity.
Market Dynamics
Growth Drivers: Pharmaceutical Applications and Clean-Label Demand Fueling Market Growth
Increasing adoption of natural phospholipids in drugs and nutraceuticals is by far the most obvious catalyst driving this market's growth, as high purity phosphatidylcholine fractions increasingly become key ingredients in liposomal formulations and parenteral emulsions, where biocompatibility and consistency truly counts for the patients' sake. Increasing demand from consumers for natural and organic products is adding impetus to this trend in the food industry, as continued clean label reformulation drives the demand for non-GMO and organic lecithin formulations.
Cosmetics and personal care applications are emerging as another major area of demand, driven by lecithin's emulsifying and skin penetrative properties.
Restraints: Feedstock Price Volatility and Allergen Concerns Limiting Market Expansion
Soybean price volatility, tied to broader agricultural commodity markets, creates genuine margin pressure at the commodity lecithin tier, where consolidation pressure has been building as producers navigate fluctuating input costs. Soy allergen concerns continue pushing some food and cosmetics manufacturers toward sunflower and other allergen-free alternatives, creating competitive pressure for soy lecithin producers in certain consumer-facing categories.
Regulatory requirements around lecithin sourcing, non-GMO certification, and organic labeling vary considerably across markets, creating genuine compliance complexity for manufacturers trying to sell standardized products internationally.
Opportunities: Pharmaceutical-Grade Purity and Plant-Based Cosmetics Creating New Growth Avenues
Pure pharmaceutical-grade phospholipid fractions offer an interesting area of growth, as more and more biopharmaceutical companies need validated and consistent quality phospholipids for liposomal formulations and stabilization of biological products. Companies that have the capability to deliver on this level of purity and quality will earn higher margins than commodity lecithin manufacturing.
Another obvious area of opportunity is plant-based cosmetics formulations due to the ability of lecithin to increase the solubility of the active ingredients in the formula.
Recent Developments:
-
Q1 2025: Lipoid GmbH opened a new R&D center dedicated to pharmaceutical-grade phospholipid technologies in Germany, alongside launching a new range of non-GMO soybean-derived phospholipids in March 2025.
-
June 2025: Lipoid GmbH announced a strategic collaboration with BASF SE to expand plant-based phospholipid production capacity, supporting rising demand in infant nutrition and plant-based food formulations.
-
July 2025: Archer Daniels Midland Company secured a major supply contract with a global dairy and cereal producer to provide high-purity soy and sunflower lecithin for spreads and bakery product formulation.
-
2024: Archer Daniels Midland Company expanded its sunflower lecithin production capacity by approximately 22%, addressing rising demand for plant-based, clean-label emulsifiers across food and nutraceutical segments.
Phospholipids & Lecithin Market key players are:
-
Archer Daniels Midland Company
-
Cargill, Incorporated
-
Bunge Global SA
-
GIIAVA
-
Patanjali Foods Limited
-
Wilmar International Limited
-
Lipoid GmbH
-
American Lecithin Company
-
Thew Arnott & Co. Ltd.
-
Sternchemie GmbH & Co. KG
-
International Flavors & Fragrances Inc.
-
Lasenor Emul, S.L.
-
Perimondo LLC
-
VAV Life Sciences Pvt. Ltd.
-
Clarkson Grain Company, Inc.
-
Avril Group
-
Advanced Lipids AB
-
Fine Organics Industries Limited
-
NOW Health Group, Inc.
-
Guangtong Biotechnology Co., Ltd.
Phospholipids & Lecithin Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.82 Billion |
| Market Size by 2035 | USD 14.05 Billion |
| CAGR | CAGR of 7.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source (Soy, Sunflower, Rapeseed & Canola, Egg) • By Type (Fluid, De-oiled, Modified) • By Application (Food & Beverages, Pharmaceutical, Nutraceuticals, Cosmetics & Personal Care, Animal Feed) • By Function (Emulsifiers, Stabilizers & Antioxidants, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Archer Daniels Midland Company, Cargill, Incorporated, Bunge Global SA, GIIAVA, Patanjali Foods Limited, Wilmar International Limited, Lipoid GmbH, American Lecithin Company, Thew Arnott & Co. Ltd., Sternchemie GmbH & Co. KG, International Flavors & Fragrances Inc., Lasenor Emul, S.L., Perimondo LLC, VAV Life Sciences Pvt. Ltd., Clarkson Grain Company, Inc., Avril Group, Advanced Lipids AB, Fine Organics Industries Limited, NOW Health Group, Inc., Guangtong Biotechnology Co., Ltd. |
Frequently Asked Questions
Key players include Archer Daniels Midland Company, Cargill, Incorporated, Bunge Global SA, Wilmar International Limited, Lipoid GmbH, American Lecithin Company, Sternchemie GmbH & Co. KG, and Thew Arnott & Co. Ltd., alongside other established phospholipid and lecithin manufacturers.
Key opportunities include pharmaceutical-grade high-purity phospholipid fractions for liposomal drug delivery, plant-based cosmetics formulations leveraging lecithin's emulsifying properties, and expanding non-GMO and organic lecithin variants for clean-label food applications.
The market is driven by increasing adoption of natural phospholipids in pharmaceuticals and nutraceuticals, rising consumer preference for natural and organic ingredients, and growing cosmetics and personal care applications.
The Soy segment dominated the Phospholipids & Lecithin Market in 2025.
The North America region dominated the Phospholipids & Lecithin Market in 2025, supported by the region's massive soybean processing industry and rising demand for natural, functional ingredients.
