
Pine-Derived Chemicals Market Report Scope & Overview:
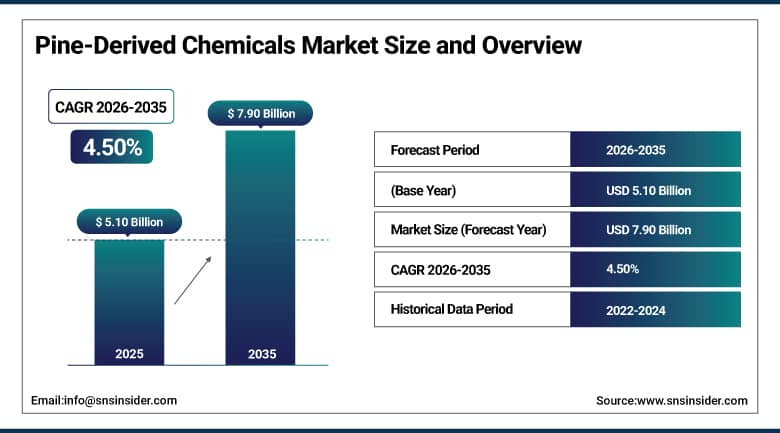
The Pine-Derived Chemicals Market was valued at USD 5.10 Billion in 2025 and is expected to reach USD 7.90 Billion by 2035, growing at a CAGR of 4.50% from 2026 to 2035.
Pine trees produce a surprising amount of chemistry once you start looking, resin, sap, and pulping byproducts that get distilled and processed into rosin, turpentine, tall oil fatty acids, and a handful of other derivatives that quietly show up in adhesives, paints, inks, tires, and increasingly personal care products. Most of this supply comes as a byproduct of the kraft pulping process that paper mills already run at massive scale, which gives pine chemicals a genuine cost and sustainability advantage over petroleum-based alternatives, products made with pine chemicals carry roughly a 50% lower carbon footprint and a 56% reduced non-renewable energy footprint compared to substitutes. That sustainability profile is becoming a bigger part of the sales pitch as manufacturers across construction, coatings, and personal care look for credible bio-based alternatives to petrochemical inputs.
In January 2026, Ingevity Corporation completed the sale of its North Charleston crude tall oil refining assets, restructuring its pine chemicals portfolio toward higher-value specialty derivatives.
To Get More Information On Pine-Derived Chemicals Market - Request Free Sample Report
Pine-Derived Chemicals Market Trends
-
Rising demand for bio-based adhesives, coatings, and lubricants as sustainable alternatives to petrochemicals is expanding pine chemical applications.
-
Personal care manufacturers are increasingly adopting pine-derived surfactants and specialty ingredients for bio-based product positioning.
-
Consolidation among pine chemical producers is reshaping regional supply and feedstock security strategies.
-
Price volatility for crude tall oil and turpentine derivatives is prompting producers to diversify into higher-margin specialty products.
-
Expanding kraft pulping capacity in Asia Pacific is increasing regional feedstock availability for downstream pine chemical processing.
U.S. Pine-Derived Chemicals Market Outlook
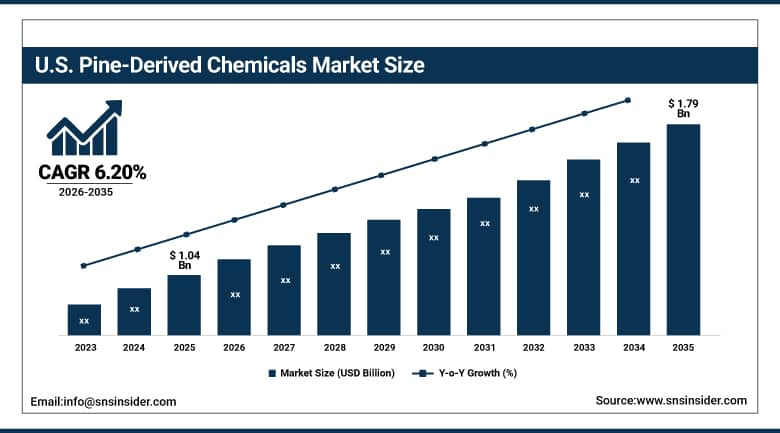
The U.S. Pine-Derived Chemicals Market was valued at USD 1.04 Billion in 2025 and is projected to reach USD 1.79 Billion by 2035, growing at a CAGR of 6.20% during 2026-2035.
Southern U.S. pulpwood production, more than 52 million cords annually with 66 pulp mills operating across the region, gives American pine chemical producers a feedstock base that few other markets can match, since crude tall oil and other pine derivatives are recovered directly from the kraft pulping process paper mills already run at scale. Construction and adhesives applications remain the largest demand categories domestically, tied closely to the broader health of the U.S. building materials and packaging industries. Producers have also been actively repositioning their portfolios toward higher-value specialty derivatives rather than commodity crude tall oil, a shift reflected in recent asset sales and restructuring among major domestic players. Rising raw material, energy, and logistics costs have pushed several producers to implement significant price increases on refined pine chemical products over the past year.
In February 2025, Kraton Corporation announced a general price increase of up to 25% on turpentine-refined products and derivatives, effective April 1, 2025, reflecting rising raw material, energy, and logistics costs.
Pine-Derived Chemicals Market Segment Analysis
-
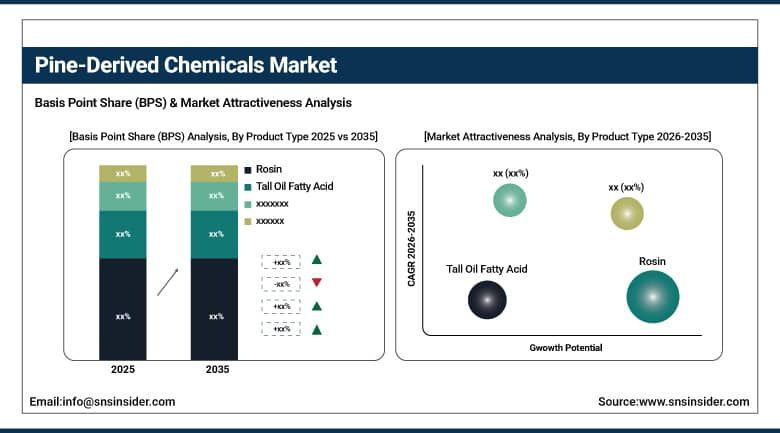
By Product Type, Rosin segment dominated the Pine-Derived Chemicals Market in 2025 with 38.00% share; Tall Oil Fatty Acid segment is the fastest-growing segment, registering a CAGR of 6.20% from 2026 to 2035.
-
By Process, Kraft Process segment dominated the market in 2025 with 62.00% share; Tapping Process segment is the fastest-growing segment, registering a CAGR of 5.80% from 2026 to 2035.
-
By End-Use Industry, Construction segment dominated the market in 2025 with 26.00% share; Personal Care segment is the fastest-growing segment, registering a CAGR of 6.60% from 2026 to 2035.
-
By Application, Adhesives & Sealants segment dominated the market in 2025 with 32.00% share; Food & Beverages segment is the fastest-growing segment, registering a CAGR of 6.80% from 2026 to 2035.
By Product Type, Rosin Leads the Pine-Derived Chemicals Market While Tall Oil Fatty Acid Gains Ground Fastest
Rosin holds 38.00% of the Pine-Derived Chemicals Market, the largest single product category, benefiting from an unusually broad application base that spans adhesives, printing inks, rubber processing, and paper sizing. Its versatility as a tackifying and film-forming agent has made it close to irreplaceable in several of these applications, giving rosin a durable position that newer pine chemical derivatives have not managed to displace even as overall demand shifts toward higher-value specialty products.
Tall Oil Fatty Acid is growing at a 6.20% CAGR, the fastest pace among product types, as demand expands across surfactants, lubricants, and increasingly personal care formulations where its bio-based profile offers a genuine sustainability advantage over petroleum-derived fatty acids. Manufacturers refining crude tall oil into higher-purity fatty acid fractions are capturing meaningfully better margins than commodity crude tall oil sales, which has pushed more producer investment toward this specific derivative.
By Process, Kraft Process Dominates While Tapping Process Emerges as the Fastest-Growing Method
The Kraft Process accounts for 62.00% of the market, the dominant production method, since it recovers pine chemical byproducts directly from the kraft pulping process that paper mills already run at industrial scale for papermaking purposes. This byproduct relationship gives kraft-derived pine chemicals a genuine cost advantage, the raw material is essentially already being generated as part of an entirely separate manufacturing process, requiring no dedicated pine harvesting or tapping operation.
The Tapping Process is growing fastest, at a 5.80% CAGR, as demand increases for gum-based pine chemicals with purity and traceability characteristics that some kraft byproduct streams cannot consistently match. Traditional gum tapping, extracting resin directly from living pine trees, is regaining interest particularly for premium and food-grade applications where sourcing transparency and product consistency matter more than raw cost efficiency.
By End-Use Industry, Construction Dominates While Personal Care Registers the Fastest Growth
Construction accounts for 26.00% of end-use demand, the largest single category, reflecting how widely pine-derived chemicals get used across adhesives, sealants, and coatings applications throughout the building materials supply chain. Growing construction activity globally, combined with rising demand for sustainable, lower-carbon-footprint building material inputs, continues reinforcing this sector's position as the category's largest downstream consumer.
Personal Care is the fastest-growing end-use industry, expanding at a 6.60% CAGR, as cosmetics and personal care formulators increasingly seek bio-based surfactants and specialty ingredients that support natural and sustainable product positioning. This crossover into a genuinely new end-use category represents one of the more significant growth stories in the pine chemicals industry, since personal care commands meaningfully higher margins than the industrial applications that have traditionally defined the category.
By Application, Adhesives & Sealants Dominates While Food & Beverages Registers the Fastest Growth
Adhesives & Sealants hold 32.00% of application demand, the largest single category, benefiting from rosin and rosin ester derivatives' well-established role as tackifying agents in both industrial and consumer adhesive formulations. Packaging, construction, and automotive adhesive applications all draw heavily on pine chemical inputs, giving this application category a broad and diversified demand base that is not overly dependent on any single downstream industry.
Food & Beverages is the fastest-growing application, expanding at a 6.80% CAGR, as food-grade pine chemical derivatives find growing use in chewing gum bases, food coatings, and beverage emulsifiers where their natural origin supports clean-label positioning. This application remains a small share of overall demand relative to industrial categories like adhesives and coatings, but its above-average growth rate reflects genuine expansion into a use case that barely existed for pine chemicals a decade ago.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.40% |
|
Asia Pacific |
China |
34.60% |
|
Europe |
France |
26.20% |
|
Middle East & Africa |
UAE |
17.10% |
|
Latin America |
Brazil |
27.80% |
Asia Pacific Pine-Derived Chemicals Market Insights
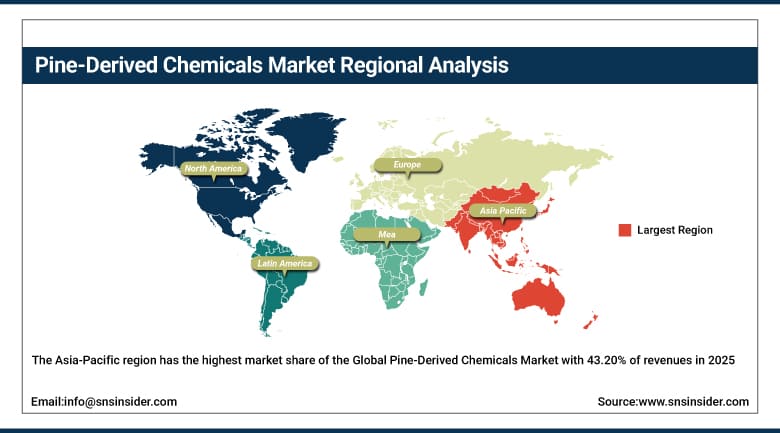
The Asia-Pacific region has the highest market share of the Global Pine-Derived Chemicals Market with 43.20% of revenues in 2025 owing to the increasing pulp and paper industry and the increasing downstream application areas such as adhesive, coating, and building materials. The fast growth and development of the manufacturing industries in China as well as high capital expenditure on the production of chemicals from pines is responsible for the dominance.
China occupies an approximate 34.60% of the regional market due to the rising capacity of the region to produce kraft pulp and chemical processing industries. The other countries that are contributing in the market are India and Southeast Asia due to the increased growth in construction and packaging industries respectively.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Pine-Derived Chemicals Market Insights
North America is growing faster than any other region in this market, driven by the world's largest concentration of kraft pulping capacity and the resulting feedstock availability that supports both crude tall oil recovery and downstream specialty chemical processing at scale. Producer investment in higher-value specialty derivatives, rather than commodity crude tall oil, is reinforcing this growth trajectory as manufacturers reposition their portfolios toward better-margin products.
The United States accounts for approximately 85.40% of the North American market, reflecting its massive Southern pulpwood production base and concentration of pine chemical refining infrastructure. Canada contributes a smaller but steady share, tied to its own forestry and pulping industry.
Europe Pine-Derived Chemicals Market Insights
Europe holds the second-largest share of the global Pine-Derived Chemicals Market, supported by a long tradition of pine chemical production tied to the region's substantial forestry industry, particularly across France and the Nordic countries. Growing demand for bio-based alternatives to petrochemical inputs across coatings, adhesives, and personal care has reinforced steady European demand even as overall growth remains more measured than in Asia Pacific.
France leads the European market with a 26.20% share, anchored by DRT, one of the world's largest pine chemical producers, and the country's substantial forestry and pulping industry. Germany and the Nordic countries follow, with demand tied to established chemical manufacturing and forestry sectors across the region.
Middle East & Africa and Latin America Pine-Derived Chemicals Market Insights
Construction and downstream chemical manufacturing have steadily increased throughout the Middle East & Africa region due to increasing demands for adhesives, coatings, and sealants related to infrastructure. However, growth for Latin America seems more promising since the region benefits from the extensive forestry sector in Brazil and consolidations within the pine chemical industry of the region.
The UAE holds a leading market position in the Middle East & Africa region with 17.10% market share as a result of its position as a construction and chemical distribution center in the region. Brazil accounts for 27.80% of the total market share in Latin America due to its extensive forestry and pine chemical industry base.
Market Dynamics
Growth Drivers: Bio-Based Chemical Demand and Sustainability Positioning Fueling Market Growth
The growing requirement for bio-based substitutes for petrochemical ingredients in adhesives, coatings, and lubricants is the most prominent factor fueling the growth of this market since manufacturers are under pressure not only from regulations but also from the demand of their customers for less CO2-intensive ingredients.
Products produced from pine chemicals have about 50% smaller carbon footprint compared to petroleum-derived counterparts, and it is becoming an increasingly crucial part of their value proposition. The development of kraft pulping facilities, especially in the Asia-Pacific region, is adding support to feedstock availability and further development of downstream pine chemicals processing.
Restraints: Feedstock Price Volatility and Petrochemical Competition Limiting Market Expansion
Prices of crude tall oil and turpentine have shown true volatility over the years due to factors within the broader forestry industry as well as utilization rates in pulping plants, rather than purely pine chemicals demand, which makes it difficult for companies to sustain the pricing levels that are constant with their downstream clients. Petrochemical substitutes, despite their less green profile, can be cheaper from an economic perspective, which may prevent the use of pine chemicals in some commoditized products. Feedstock for pine chemicals is also available mainly in regions where there is high capability to conduct kraft pulping.
Opportunities: Personal Care Expansion and Specialty Derivative Innovation Creating New Growth Avenues
Personal care represents one of the clearest growth opportunities in this market, as cosmetics and personal care formulators increasingly seek bio-based surfactants and specialty ingredients that support natural and sustainable product positioning, a use case that commands meaningfully higher margins than traditional industrial applications. Manufacturers who can develop personal-care-grade pine derivatives stand to capture premium positioning in this expanding category.
Continued investment in refining crude tall oil and rosin into higher-purity, higher-value specialty derivatives offers a second clear opportunity, particularly as producers reposition away from commodity crude products toward better-margin specialty chemistry that can better withstand feedstock price volatility.
Recent Developments:
-
January 2026: Ingevity Corporation completed the sale of its North Charleston crude tall oil refining assets, restructuring its pine chemicals portfolio toward higher-value specialty derivatives.
-
February 2025: Kraton Corporation announced a general price increase of up to 25% on turpentine-refined products and derivatives, effective April 1, 2025, reflecting rising raw material, energy, and logistics costs.
-
March 2024: Grupo Resinas Brasil, one of Brazil's largest pine chemicals producers, acquired a majority stake in Pinopine, a Portugal-based gum rosin derivatives producer.
-
2025: Harima Chemicals Group Inc. continued integrating its pine chemicals and resin businesses to strengthen downstream product differentiation across tall oil fatty acid and rosin ester applications.
Pine-Derived Chemicals Market key players are:
-
Ingevity Corporation
-
Kraton Corporation
-
Eastman Chemical Company
-
DRT (Dérivés Résiniques et Terpéniques)
-
Harima Chemicals Group, Inc.
-
Forchem Oy
-
Arakawa Chemical Industries, Ltd.
-
Foreverest Resources Ltd.
-
Georgia-Pacific Chemicals LLC
-
Lawter, Inc.
-
Segezha Group
-
Resinall Corporation
-
Sunpine AB
-
Guangxi Wuzhou Pine Chemical Co., Ltd.
-
Deler S.A.
-
Chemol Company, Inc.
-
Pine Chemical Group (Smurfit Westrock)
-
Respol Resinas S.A.
-
Yunnan Jinsen Forest Resources Co., Ltd.
-
Guangxi Yulin Pine Chemical Co., Ltd.
Pine-Derived Chemicals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.10 Billion |
| Market Size by 2035 | USD 7.90 Billion |
| CAGR | CAGR of 4.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Rosin, Tall Oil Fatty Acid, Turpentine, Pitch) • By Process (Kraft Process, Tapping Process) • By End-Use Industry (Construction, Personal Care, Automotive, Others) • By Application (Adhesives & Sealants, Paints & Coatings, Surfactants, Printing Inks) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ingevity Corporation, Kraton Corporation, Eastman Chemical Company, DRT (Dérivés Résiniques et Terpéniques), Harima Chemicals Group, Inc., Forchem Oy, Arakawa Chemical Industries, Ltd., Foreverest Resources Ltd., Georgia-Pacific Chemicals LLC, Lawter, Inc., Segezha Group, Resinall Corporation, Sunpine AB, Guangxi Wuzhou Pine Chemical Co., Ltd., Deler S.A., Chemol Company, Inc., Pine Chemical Group (Smurfit Westrock), Respol Resinas S.A., Yunnan Jinsen Forest Resources Co., Ltd., Guangxi Yulin Pine Chemical Co., Ltd. |
Frequently Asked Questions
Key players include Ingevity Corporation, Kraton Corporation, Eastman Chemical Company, DRT (Dérivés Résiniques et Terpéniques), Harima Chemicals Group, Inc., Forchem Oy, Arakawa Chemical Industries, Ltd., and Foreverest Resources Ltd., alongside other established pine chemical manufacturers.
Key opportunities include expanding personal care applications for bio-based surfactants, continued investment in higher-value specialty derivatives, and rising demand for sustainable alternatives to petrochemical-based adhesives and coatings.
The market is driven by rising demand for bio-based alternatives to petrochemicals, expanding kraft pulping capacity in Asia Pacific, and growing sustainability positioning across coatings, adhesives, and personal care industries.
The Rosin segment dominated the Pine-Derived Chemicals Market in 2025.
The Asia Pacific region dominated the Pine-Derived Chemicals Market in 2025, accounting for approximately 43.20% of global market share.
