
Plastic Caps & Closures Market Report Scope & Overview:
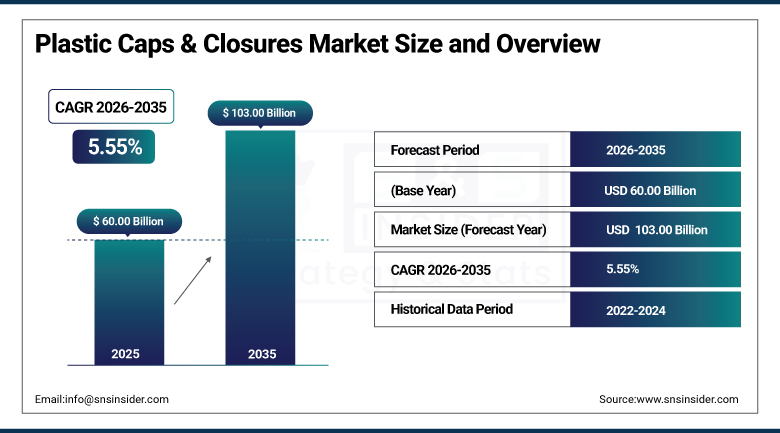
The Plastic Caps & Closures Market was valued at USD 60.00 Billion in 2025 and is expected to reach USD 103.00 Billion by 2035, growing at a CAGR of 5.55% from 2026–2035.
Plastic caps and closures are the small, mass-produced components that seal a bottle, jar, or tube, doing quiet but essential work protecting contents from contamination and tampering while giving a consumer a simple, reliable way to open and reseal a package. They're less expensive than metal alternatives and increasingly engineered for tamper-evidence and child resistance, requirements that have gone from optional to mandatory across pharmaceutical and household chemical packaging in most major markets. Regulatory reshaping has arrived fast in this category recently, since the EU's tethered-cap mandate now requires closures to stay physically attached to beverage containers, forcing a design change across essentially every beverage bottle sold in Europe.
AptarGroup expanded its pharmaceutical dispensing portfolio through the acquisition of Sommaplast in December 2025, deepening its position as the global benchmark for beauty and pharmaceutical dispensing systems. Regulatory approval requirements in pharmaceutical packaging make supplier switching genuinely difficult once a closure design is qualified for a specific drug product, which is exactly why the handful of specialized dispensing closure manufacturers like Aptar keep growing through acquisition rather than losing share to lower-cost, less specialized competitors.
To Get more information On Plastic Caps & Closures Market - Request Free Sample Report
Plastic Caps & Closures Market Trends
-
Tethered-cap designs continue spreading beyond the EU's original mandate, as beverage manufacturers in other regions adopt similar attached-closure formats ahead of anticipated regulatory expansion.
-
Post-consumer recycled content integration continues expanding across closure production, as manufacturers respond to recycled-content mandates requiring 30% recycled beverage bottle content by 2030 in the EU alone.
-
Lightweighting continues advancing through improved molding technology, letting manufacturers reduce resin consumption per unit without compromising sealing performance or filling-line compatibility.
-
Smart and connected closures continue emerging as a genuine product category, with embedded technology supporting product authentication, traceability, and consumer engagement beyond basic sealing function.
-
Consolidation continues reshaping the competitive landscape, as larger integrated packaging companies acquire specialized dispensing and closure manufacturers to broaden their combined product portfolios.
U.S. Plastic Caps & Closures Market Outlook
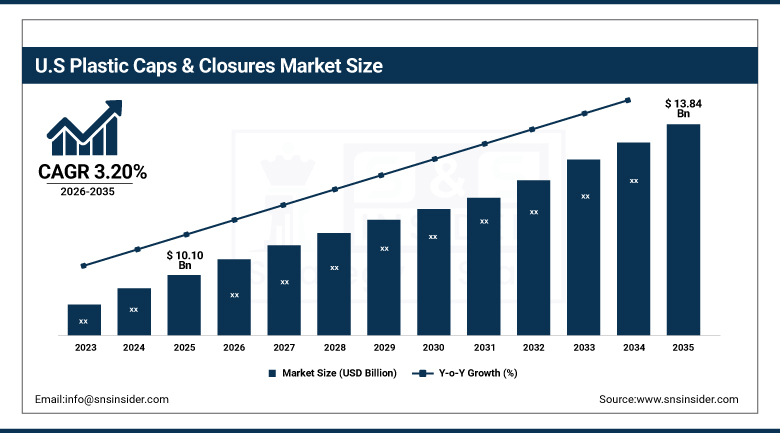
The U.S. Plastic Caps & Closures Market was valued at approximately USD 10.10 Billion in 2025 and is expected to reach approximately USD 13.84 Billion by 2035, growing at a CAGR of approximately 3.20%.
Demand in the United States is anchored by a large, mature beverage industry alongside pharmaceutical and household chemical sectors that depend on tamper-evident and child-resistant closure designs mandated by federal regulation. Domestic growth remains more moderate than the global average, reflecting mature market dynamics and already well-established production infrastructure across most closure categories. A concentration of the world's largest closure manufacturers, several with major American operations, continues anchoring domestic supply even as growth opportunities increasingly concentrate in faster-growing emerging markets.
U.S. federal regulation under 21 CFR 211.132 requires that over-the-counter drug packages accessible to the public use tamper-evident packaging, a rule that has sustained steady domestic demand for certified tamper-indicating plastic closures regardless of broader economic cycles. That regulatory floor gives American closure manufacturers serving the pharmaceutical sector a more predictable revenue base than beverage or food closure makers, whose volumes track more closely with discretionary consumer spending and seasonal demand patterns.
Plastic Caps & Closures Market Segment Analysis
-
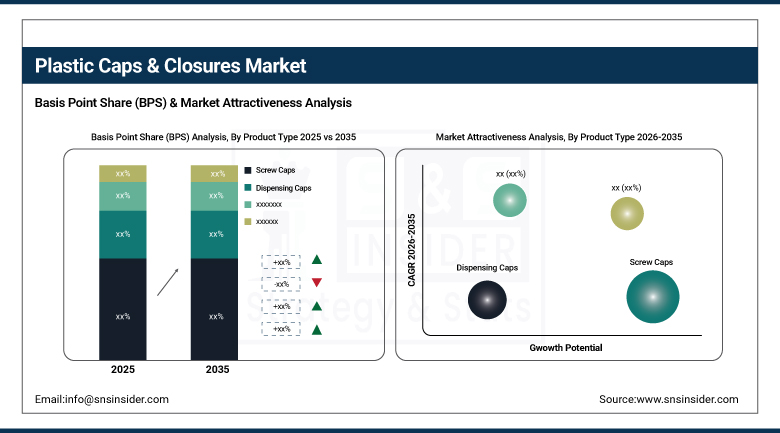
By Product Type, the Screw Caps segment dominated the Plastic Caps & Closures Market with approximately 43.00% share in 2025, while the Dispensing/Flip-Top Caps segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Technology, the Compression Molding segment dominated the Plastic Caps & Closures Market with approximately 52.40% share in 2025, while the Post-Mold TE Band segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Raw Material, the Polypropylene (PP) segment dominated the Plastic Caps & Closures Market with approximately 57.00% share in 2025, while the High-Density Polyethylene (HDPE) segment is the fastest growing with a CAGR of approximately 6.80%.
-
By End-Use Sector, the Beverages segment dominated the Plastic Caps & Closures Market with approximately 38.60% share in 2025, while the Pharmaceutical segment is the fastest growing with a CAGR of approximately 7.40%.
By Product Type, screw caps dominates, dispensing/flip-top caps grows fastest
Screw caps held the largest share of the product-type segment in 2025, favored for their universal compatibility, tamper-evident design, and widespread use across beverage and pharmaceutical applications that make up the bulk of global closure demand. Their compatibility with high-speed filling lines across nearly every bottle format keeps screw caps the practical default across the overwhelming majority of plastic closure production worldwide, regardless of end-use industry or regional market maturity.
Dispensing and flip-top caps are growing fastest as the shift toward smaller pack sizes, travel-friendly formats, and sustainable packaging solutions continues boosting replacement cycles and new product launches across personal care and food categories. That combination of high innovation intensity, frequent product introductions, and strong e-commerce sales growth underpins this product category's above-average growth trajectory relative to the broader, screw-cap-dominated product mix.
By Technology, compression molding dominates, post-mold TE band grows fastest
Compression molding held the largest share of the technology segment in 2025, valued for its cost efficiency and suitability for high-volume, standardized closure production across beverage and food packaging applications. That production efficiency advantage keeps compression molding the default manufacturing technology for the majority of plastic closure output, particularly for the high-volume screw cap formats that dominate the broader product-type segment.
Post-mold TE band technology is growing fastest due to its superior functionality and adaptability, allowing tamper-evident features to be added after the primary molding process for greater design flexibility and compatibility with various cap shapes and sizes. The ability to integrate these bands post-mold makes this technology a preferred choice for manufacturers looking to reduce production complexities and enhance product security, reinforcing this above-average growth trajectory.
By Raw Material, PP dominates, HDPE grows fastest
Polypropylene accounted for the majority share in the raw materials segment owing to its chemical resistance and cost-effectiveness in high volume applications such as beverages, wherein its ability to mold into light structures reduces transportation emissions. Catalysts behind this are the preference for mono-materials in order to facilitate efficient recycling and cost-effectiveness as opposed to the composite closure design, making polypropylene the leading raw material even in the more generalized plastic caps and closures market.
High density polyethylene is witnessing the fastest growth owing to the increasing demand for a durable, yet recyclable raw material in pharmaceuticals that provides protection against moisture better than any other raw material. The combination of durability and regulation-friendly recyclability is continuously driving the growth of this particular raw material segment above the growth of the overall, polypropylene-dominant raw materials segment.
By End-Use Sector, beverages dominates, pharmaceutical grows fastest
Beverages accounted for the largest end-use share in 2025, reflecting rising demand from bottled water, carbonated drinks, and dairy products that collectively represent the closure industry's highest-volume application by a wide margin. Growth of the global beverage industry, combined with sustained consumer preference for bottled and packaged drinks across both developed and emerging markets, continues reinforcing beverages' dominant position within the broader plastic caps and closures market.
Pharmaceutical is the fastest-growing end-use sector as rising healthcare product consumption, combined with increasingly stringent regulatory requirements for secure and compliant packaging, continues expanding demand for tamper-evident and child-resistant closures. Growing global pharmaceutical manufacturing capacity and expanding generic drug production, particularly across emerging markets, continue reinforcing this above-average growth trajectory relative to the broader, beverage-dominated end-use mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.80% |
|
North America |
United States |
80.20% |
|
Europe |
Germany |
25.40% |
|
Latin America |
Brazil |
35.60% |
|
Middle East & Africa |
UAE |
30.60% |
Asia Pacific Plastic Caps & Closures Market Insights
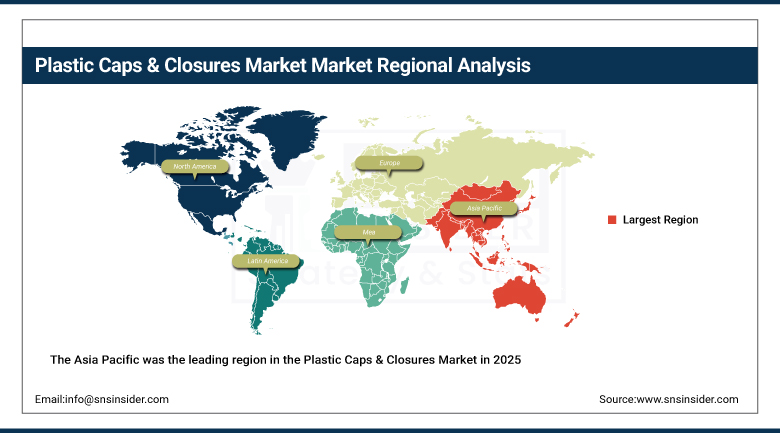
The Asia Pacific was the leading region in the Plastic Caps & Closures Market in 2025, accounting for approximately 40.60% of total market revenue in the global market because of the region's fast urbanization process, fast population growth, and manufacturing activities in its major and fast-growing economies. Growing consumption of packaged beverages, foods, and cosmetics products by the growing middle class in this region has kept it ahead, backed up by manufacturing capacity investments made by various Asian countries with government support.
The large manufacturing base for beverages and consumer goods in China is a strong base demand for this region, while the growing organized retail and pharmaceutical industries in India are making investments in closure manufacturing capacity. The Japanese and South Korean markets are more mature and technology-driven markets, while the Southeast Asian markets are developing in a similar manner to the above region.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa Plastic Caps & Closures Market Insights
Middle East and Africa regions are projected to have the fastest-growing regional market through 2035 driven by the diversification of economies and the increase in consumer goods production in the fastest-developing regions within the area. United Arab Emirates leads this region in terms of growth with an increasing demand for beverages, personal care products, and pharmaceutical retail investments.
This increase in demand is as a result of the diversification strategy of their economy. Saudi Arabia adds to this demand due to its diversification strategy and investments in infrastructure. On the other hand, South Africa is the major driver of demand for the rest of the continent.
North America Plastic Caps & Closures Market Insights
North America is home to a significant market for caps and closures, where the US is responsible for the vast majority of demand due to its well-established beverages, pharmaceuticals, and chemicals industry. Domestic demand will grow at a slower pace compared to the global average due to mature dynamics and existing production capabilities to satisfy the region’s requirements.
Canada adds demand via its domestic manufacturing of beverages and consumer goods, while Mexico’s market will keep growing amid rising manufacturing investment in nearshoring conditions. Supply connections between North American countries bind a significant portion of the region’s demand into one, as leading producers provide to all three countries.
Europe Plastic Caps & Closures Market Insights
Europe is a mature market where caps and closures are highly regulated and can be described as a true regulator of sustainable closure design due to the EU’s regulation requiring tethered closures implemented in July 2024. Germany is an important regional player due to a considerable beverage and pharmaceutical production industry and many closure manufacturers investing heavily in recycled and tethered closure equipment. France, Italy, and the UK also provide important volumes due to a strong beverage and food manufacturing industry responding to growing demands of the new Packaging and Packaging Waste Regulation.
MEA & Latin America Plastic Caps & Closures Market Insights
The Middle East and Africa's growth story is detailed above given its status as the fastest-growing region, while Latin America is a growing market led by Brazil, where expanding beverage and consumer goods manufacturing continues driving demand for cost-efficient plastic closures. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing manufacturing sectors serving both domestic consumption and export-oriented consumer goods markets across the broader region.
Growth across both regions remains tied closely to the pace of broader consumer goods manufacturing and beverage industry infrastructure development, with government-backed economic diversification programs across Gulf states providing an additional layer of investment momentum not present in most Latin American markets.
Market Dynamics
Growth Drivers: Beverage industry expansion and sustainable packaging demand fueling adoption
Expansion of the global beverage industry is one of the clearest forces behind rising plastic caps and closures demand, as rising consumption of bottled water, carbonated drinks, and dairy products worldwide continues driving sustained closure volume growth across nearly every major market. That consistent, high-frequency purchase pattern gives the plastic caps and closures market a demand base that holds up reliably across broader economic cycles and consumer spending fluctuations.
Increasing demand for sustainable packaging solutions adds a second major driver, as brand owners and regulators alike push toward recyclable, mono-material, and lightweight closure designs that reduce environmental impact without sacrificing sealing performance. Advancements in material science and technology, combined with rising consumer preference for customizable designs, continue reinforcing this demand base across beverage, food, and personal care applications.
Restraints: Regulatory redesign costs and raw material price volatility limiting margin stability
Stringent regulatory pressures on plastic use remain a genuine restraint, as tethered-cap mandates and other regulatory redesign requirements create substantial retrofit capital requirements exceeding tens of millions of dollars for multinational operators adapting existing production lines. That regulatory compliance burden falls disproportionately on smaller manufacturers without the capital resources to quickly retool production across multiple facilities and product lines simultaneously.
Fluctuating raw material costs and availability add a further restraint, since closure manufacturers remain exposed to broader propylene and ethylene commodity market swings that directly affect production costs across every closure category and technology. Manufacturers without long-term resin supply contracts are particularly exposed to these swings, which can compress margins even when finished-closure demand remains steady.
Opportunities: Recycled content development and smart closure integration opening new growth avenues
Recycled content development offers manufacturers a genuine path to capturing premium business from brand owners chasing credible sustainability commitments ahead of tightening EU and other regional recycled-content mandates. Companies that successfully develop high-PCR-content closures matching virgin material performance are positioned to capture significant new business as regulatory recycled-content requirements continue expanding across major beverage markets.
Smart closure integration represents a second significant opportunity, as embedded authentication and traceability technology continues expanding beyond basic sealing function into genuine brand protection and consumer engagement tools. Manufacturers that build genuine smart closure capability are positioned to capture premium pricing from brand owners seeking differentiation beyond conventional closure functionality alone.
Recent Developments:
-
December 2025: AptarGroup acquired Sommaplast, expanding its high-tech dispensing and pharmaceutical closure portfolio.
-
2024: Guala Closures invested in new tethered cap production tooling to serve beverage manufacturers complying with EU regulatory requirements.
-
February 11, 2025: The EU's Packaging and Packaging Waste Regulation entered into force, with broad provisions applying from August 2026, reinforcing redesign pressure around recyclability and waste prevention across the closures industry.
-
March 2023: Aptar Closures acquired a majority stake in Gulf Closures, adding beverage-closure manufacturing capacity in the Middle East.
Plastic Caps & Closures Market Key Players
-
Berry Global Inc. (part of Amcor plc)
-
AptarGroup, Inc.
-
Silgan Holdings Inc.
-
Amcor plc
-
Closure Systems International, Inc.
-
Bericap GmbH & Co. KG
-
Mold-Rite Plastics LLC
-
Guala Closures S.p.A.
-
Albea Group
-
Origin Materials
-
Alpek S.A.B. de C.V.
-
TriMas Corporation (Rieke Packaging Systems)
-
United Caps Luxembourg S.A.
-
CL Smith Company
-
Weener Plastics Holding B.V.
-
O.Berk Company, LLC
-
Novembal SAS
-
Blackhawk Molding Co., Inc.
-
Comar, LLC
-
Manaksia Industries Limited
Plastic Caps & Closures Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 60.00 Billion |
| Market Size by 2035 | USD 103.00 Billion |
| CAGR | CAGR of 5.55% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Screw Caps, Dispensing Caps, Flip-Top Caps, Child-Resistant Caps, Others) • by Technology (Compression Molding, Injection Molding, Post-Mold TE Band) • by Raw Material (Polypropylene (PP), High-Density Polyethylene (HDPE), Low-Density Polyethylene (LDPE), Polyethylene Terephthalate (PET), Others) • by End-Use Sector (Food, Beverages, Pharmaceutical, Cosmetics & Toiletries, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Berry Global Inc. (part of Amcor plc), AptarGroup, Inc., Silgan Holdings Inc., Amcor plc, Closure Systems International, Inc., Bericap GmbH & Co. KG, Mold-Rite Plastics LLC, Guala Closures S.p.A., Albea Group, Origin Materials, Alpek S.A.B. de C.V., TriMas Corporation (Rieke Packaging Systems), United Caps Luxembourg S.A., CL Smith Company, Weener Plastics Holding B.V., O.Berk Company, LLC, Novembal SAS, Blackhawk Molding Co., Inc., Comar, LLC, Manaksia Industries Limited |
Frequently Asked Questions
Key players in the Plastic Caps & Closures Market include Berry Global Inc., AptarGroup, Inc., Silgan Holdings Inc., Amcor plc, and Closure Systems International, Inc., among others.
Key opportunities in the Plastic Caps & Closures Market include recycled content development matching virgin material performance and smart closure integration for authentication and consumer engagement.
The market is driven by expansion of the global beverage industry, combined with increasing demand for sustainable, recyclable, and lightweight packaging solutions.
The Screw Caps segment dominated the Plastic Caps & Closures Market, accounting for approximately 43.00% market share.
The Asia Pacific region dominated the Plastic Caps & Closures Market in 2025 with approximately 40.60% share, driven by rapid urbanization, population growth, and expanding manufacturing activities.
