
Polystyrene Packaging Market Report Scope & Overview:
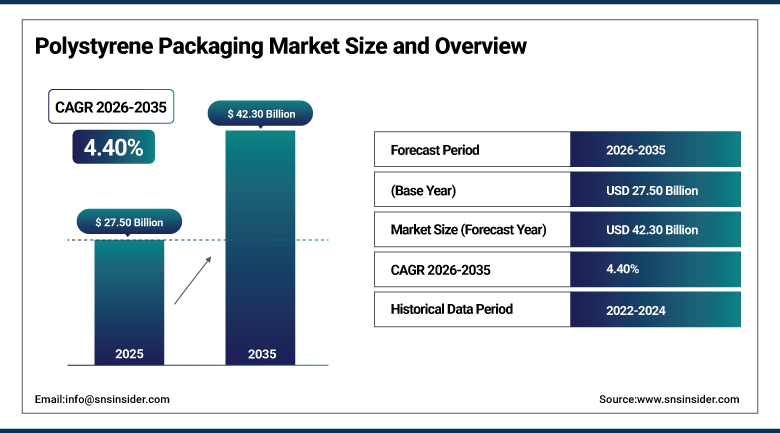
The Polystyrene Packaging Market was valued at USD 27.50 Billion in 2025 and is expected to reach USD 42.30 Billion by 2035, growing at a CAGR of 4.40% from 2026–2035.
Polystyrene packaging spans everything from the rigid clamshell holding a supermarket cut of meat to the expanded foam block cradling a flat-screen television through a cross-country shipment, all built around the same lightweight, moldable plastic that's cheap to produce at scale. Its combination of low cost, effective insulation, and shock-absorbing cushioning has made it difficult to fully displace despite decades of environmental criticism and a growing list of local bans. The industry's real story right now isn't decline, it's a genuine, if incomplete, transformation toward recycled and bio-based content that lets the material keep its practical advantages while shedding some of its worst sustainability baggage.
INEOS Styrolution commercialized a 100% bio-attributed polystyrene in July 2025, Styrolution PS 158K BC100, achieving a 172% reduction in carbon emissions compared to conventional fossil-based polystyrene while remaining fully compliant with global food-contact regulations. Food trays made from the material began appearing on shelves at a major Japanese retail chain earlier that year, a genuinely rare case of a sustainability claim showing up on a real product rather than staying confined to a corporate presentation.
To Get more information Polystyrene Packaging Market - Request Free Sample Report
Polystyrene Packaging Market Trends
-
Chemical recycling through depolymerization continues advancing from pilot to commercial scale, converting post-consumer polystyrene waste directly back into its original liquid monomer for genuine closed-loop, food-grade reuse.
-
Bio-attributed and mass-balance certified polystyrene grades are reaching real retail shelves rather than remaining laboratory demonstrations, giving brand owners a credible carbon-reduction claim without changing product performance or packaging line equipment.
-
Major producers are formalizing recycled-content commitments for European packaging specifically, tying corporate sustainability targets directly to specific percentage thresholds rather than vaguer, longer-term aspirational goals.
-
E-commerce packaging continues driving steady demand for expanded polystyrene's cushioning and insulation properties, particularly for shock-sensitive electronics and cold-chain food and pharmaceutical shipments.
-
Regulatory pressure on single-use foam foodservice packaging continues intensifying in specific jurisdictions, pushing converters toward rigid and recycled polystyrene formats that fall outside the scope of the narrowest foam-specific bans.
U.S. Polystyrene Packaging Market Outlook
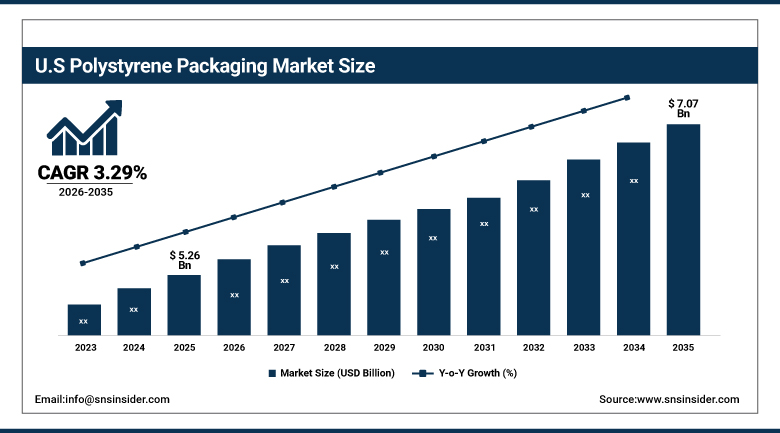
The U.S. Polystyrene Packaging Market was valued at approximately USD 5.26 Billion in 2025 and is expected to reach approximately USD 7.07 Billion by 2035, growing at a CAGR of approximately 3.29%.
The demand within the United States continues to center on food and beverages packaging, consumer electronics protective packaging, and foodservice packaging applications, despite increasing state and local bans being placed on certain foam foodservice products. The domestic manufacturers continue their efforts to invest in recycling technology in order to stay ahead of the regulatory trends and commitments made by brands for their sustainability initiatives. There is an aggregation of major global producers of polystyrene who have significant American manufacturing and research & development capability that will help the U.S. converters and brand owners take advantage of the next generation of materials developments.
Trinseo, a Pennsylvania-based chemical company, unveiled a transparent recycled polystyrene resin using dissolution technology in March 2025, the first of its kind approved for direct food contact in applications including dairy containers, food trays, and hot and cold drink cups. The company's global production footprint, spanning facilities in Europe and the Americas, gives it the flexibility to bring technology developed at one site to market across multiple regions, a capability increasingly important as food-contact recycling regulations continue to vary market by market.
Polystyrene Packaging Market Segment Analysis
-
By Product Type, the Expandable Polystyrene (EPS) segment dominated the Polystyrene Packaging Market with approximately 38.20% share in 2025, while the Extruded Polystyrene (XPS) segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Manufacturing Process, the Injection Molding segment dominated the Polystyrene Packaging Market with approximately 41.60% share in 2025, while the Thermoforming segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Application, the Food & Beverage segment dominated the Polystyrene Packaging Market with approximately 35.80% share in 2025, while the Pharmaceuticals segment is the fastest growing with a CAGR of approximately 7.40%.
By Product Type, EPS dominates, XPS grows fastest
Expandable polystyrene held the largest share of the product-type segment in 2025, valued for its superior insulation properties and shock-absorbing capability that make it the preferred choice for protective packaging across electronics, appliances, and cold-chain food shipments. Its solid-bead foam structure gives it compression resistance well suited to stackable packaging, letting shippers protect fragile goods through multiple handling points without adding significant weight. That combination of light weight and structural reliability has kept EPS the dominant product type despite mounting environmental scrutiny and a steady stream of local restrictions on foam packaging in specific applications.
Extruded polystyrene is growing fastest as its denser, more moisture-resistant foam structure gains preference for applications requiring stronger compressive strength and better long-term dimensional stability than standard expandable foam offers. Rising demand for durable, weather-resistant protective packaging in industrial and cold-chain logistics applications continues pulling this product category's growth ahead of the broader, more established expandable polystyrene segment. Converters investing in XPS-specific extrusion capacity are positioning themselves to capture this above-average growth as specification requirements continue tightening across demanding shipping and storage applications.
By Manufacturing Process, injection molding dominates, thermoforming grows fastest
Injection Molding captured the biggest share of the manufacturing process segment in 2025 due to its precision, consistency, and ability to manufacture complex, high volume and quality packaging parts consistently over long runs. Due to its compatibility with automatic and fast production line, Injection Molding remains the preferred manufacturing process for rigid polystyrene packaging parts in consumer electronics, food packaging and appliance packaging applications. Growing investment in high-speed multi-cavity injection molding equipment continues to reinforce the dominance of this category in the overall manufacturing process mix.
Thermoforming is growing at a faster rate than any other manufacturing process category due to its relatively low tooling costs and faster changeover time suitable for short production runs and more specialized rigid packaging part shapes which cannot be economically produced by Injection Molding due to high tooling cost. This versatility of Thermoforming makes it a preferred manufacturing process for food packaging applications where there is frequent change in packaging shapes to cater to different retail environments.
By Application, food & beverage dominates, pharmaceuticals grows fastest
The food and beverages application accounted for the highest share in 2025, including all disposable food service containers, trays, and clamshells deployed in both grocery retail and food delivery supply chains. The affordability of polystyrene, its insulation capabilities, and its food-safe formulations allow polystyrene to remain an affordable default choice for food packages of different types despite the environmental pressure. Rising trends of packaged food consumption and food delivery around the globe continue to bolster this application dominance within the entire polystyrene packaging industry.
Pharmaceuticals is the most rapidly growing application as the moldability capabilities of polystyrene and its suitability for tamper-evident and sterile packaging continue to widen its usage for blister packs, diagnostics, and medical devices packaging. Rising expenditures on healthcare around the globe and rising pharmaceuticals production capacities, especially in developing countries, continue to contribute to the above-average growth of this application. Cold chain vaccine and biological products require precise packaging that is not prone to contaminations; therefore, pharmaceutical applications are becoming more important for polystyrene packaging industry.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.35% |
|
North America |
United States |
79.62% |
|
Europe |
Germany |
25.14% |
|
Latin America |
Brazil |
35.78% |
|
Middle East & Africa |
Saudi Arabia |
28.93% |
Asia Pacific Polystyrene Packaging Market Insights
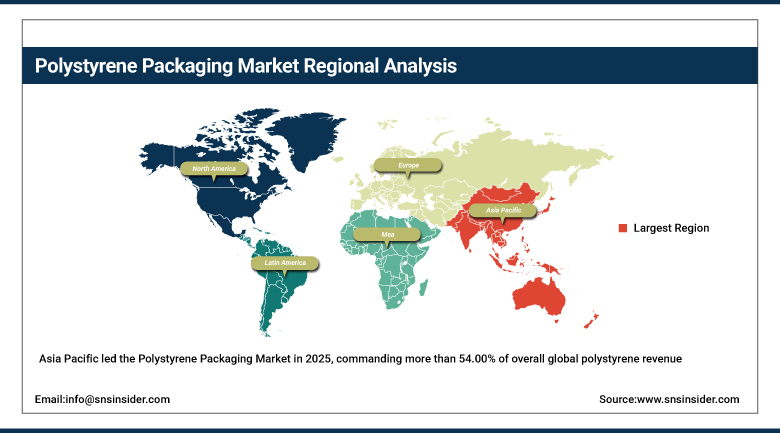
Asia Pacific led the Polystyrene Packaging Market in 2025, commanding more than 54.00% of overall global polystyrene revenue when measured across the material's full range of applications, and is also expected to register the fastest regional growth through 2035 at a CAGR of approximately 6.40%. The region's massive electronics manufacturing base, expanding packaged food consumption, and continued growth of organized retail across China and India all continue reinforcing this leading and accelerating position. Government-supported industrial capacity expansion across multiple Asian economies keeps regional polystyrene production growing in step with rising domestic packaging demand.
China's large-scale consumer electronics and food processing sectors give the region substantial baseline demand, while India's expanding organized retail and pharmaceutical manufacturing sectors are adding meaningful new volume on top of an already sizable production base. Japan and South Korea represent more mature, technology-forward markets with established polystyrene converting industries, while Southeast Asian markets continue following a similar consumption-driven growth trajectory as regional manufacturing and retail infrastructure expands.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Polystyrene Packaging Market Insights
North America represents a substantial polystyrene packaging market, with the United States accounting for the large majority of regional demand through its established food and beverage, consumer electronics, and healthcare packaging sectors. Growing state and municipal restrictions on specific foam foodservice applications continue reshaping product specification across the region, pushing converters toward recycled-content and rigid polystyrene alternatives that fall outside the narrowest local bans.
Canada contributes additional demand through its own food processing and consumer goods manufacturing sectors, while Mexico's market continues expanding alongside growing nearshoring-driven manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major producers typically serving all three markets through shared production and distribution networks spanning the continent.
Europe Polystyrene Packaging Market Insights
Europe has a well-established, sustainability-oriented polystyrene packaging market, defined by the strong recycled content targets set out by key manufacturers and increasing EU packaging waste legislation that focuses on single-use plastic groups. Key market demand is driven by Germany due to its strong consumer goods and food production manufacturing industry base and numerous polystyrene manufacturers that have made significant investments in chemical recycling technology.
France, Italy, and the UK also make their contribution to the market volume through their strong food and electronics manufacturing industries. Commitments in the industry to recycled content standards in European packaging drive brands and converters towards a closed-loop sourcing strategy in the region.
MEA & Latin America Polystyrene Packaging Market Insights
The Middle East and Africa represent a smaller but developing polystyrene packaging market, with Saudi Arabia driving demand through growing petrochemical production capacity and expanding food processing and retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader consumer goods manufacturing and organized retail infrastructure development.
Latin America is a growing market led by Brazil, where expanding food processing and consumer electronics manufacturing continue driving demand for cost-efficient protective and food packaging. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing manufacturing sectors serving both domestic and export-oriented consumer goods markets.
Market Dynamics
Growth Drivers: Cost-effective protective packaging demand and e-commerce growth fueling adoption
Sustained demand for cost-effective, lightweight protective packaging is one of the clearest forces behind rising polystyrene packaging demand, as its combination of low material cost, effective insulation, and shock-absorbing cushioning remains difficult for alternative materials to match at comparable price points. That fundamental cost and performance advantage keeps polystyrene competitive across food, electronics, and pharmaceutical packaging applications even as sustainability pressure continues building against the material.
Continued e-commerce growth adds a second major driver, as expanding online retail and direct-to-consumer shipping volumes drive sustained demand for polystyrene's cushioning and insulation properties in shipping shock-sensitive electronics and cold-chain food and pharmaceutical products. Rising global online shopping penetration across both developed and emerging markets continues reinforcing this demand base independent of broader packaged goods consumption trends.
Restraints: Environmental regulation and recycling infrastructure gaps limiting broader adoption
Tightening environmental regulation targeting single-use foam packaging remains a genuine restraint, as more cities and states restrict specific polystyrene foodservice applications, forcing converters to reformulate products or shift customers toward alternative materials in affected jurisdictions. That regulatory pressure adds real compliance complexity for manufacturers serving customers across multiple, inconsistently regulated markets simultaneously.
Limited recycling infrastructure for polystyrene specifically adds a further restraint, since the material's low density and contamination sensitivity make conventional mechanical recycling economically challenging in many markets without dedicated collection and processing systems. That infrastructure gap limits how quickly genuine circularity can scale even as producers invest heavily in chemical recycling and depolymerization technology as an alternative pathway.
Opportunities: Chemical recycling scale-up and bio-attributed material development opening new growth avenues
Scaling chemical recycling and depolymerization technology offers producers a genuine path to capturing premium business from brand owners seeking credible, food-grade recycled content that mechanical recycling alone can't reliably deliver at scale. Companies that build strong depolymerization infrastructure are positioned to capture disproportionate growth as regulatory recycled-content mandates continue expanding across major packaging markets worldwide.
Bio-attributed and mass-balance certified material development represents a second significant opportunity, letting producers offer meaningfully lower carbon footprint products without requiring brand owners to change existing packaging line equipment or product specifications. Companies that successfully commercialize these certified renewable feedstock products are positioned to capture premium pricing from brand owners pursuing credible sustainability claims across their packaging portfolios.
Recent Developments:
-
September 2025: INEOS Styrolution marked its first commercial delivery of recycled styrene monomer from Indaver's Plastics2Chemicals depolymerization process, converting hard-to-recycle plastics into virgin-quality feedstock.
-
Early 2025: INEOS Styrolution introduced sour cream cups made with 30% recycled polystyrene at ALDI SÜD, following its earlier mechanically recycled yoghurt cup launch at Lidl.
-
2025: INEOS Styrolution began providing Product Carbon Footprint data for its entire product portfolio using a proprietary tracking tool, aimed at giving customers transparent emissions data for sustainability reporting.
-
2025: Trinseo and INEOS Styrolution continued advancing joint recycling infrastructure projects as founding members of Styrenics Circular Solutions, the value chain initiative aimed at increasing styrenics circularity across Europe.
Polystyrene Packaging Market Key Players
-
BASF SE
-
TotalEnergies SE
-
SABIC
-
INEOS Styrolution Group GmbH
-
Trinseo PLC
-
LG Chem Ltd.
-
Alpek S.A.B. de C.V.
-
Formosa Chemicals & Fibre Corporation
-
Americas Styrenics LLC
-
Synthos S.A.
-
Chi Mei Corporation
-
PS Japan Corporation
-
NOVA Chemicals Corporation
-
Kaneka Corporation
-
JSR Corporation
-
Sekisui Plastics Co., Ltd.
-
Sonoco Products Company
-
Genpak, LLC
-
Dart Container Corporation
-
Total Petrochemicals & Refining USA, Inc.
Polystyrene Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 27.50 Billion |
| Market Size by 2035 | USD 42.30 Billion |
| CAGR | CAGR of 4.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Expandable Polystyrene (EPS), Extruded Polystyrene (XPS), Polystyrene Sheet, Polystyrene Foam, Others) • by Manufacturing Process (Injection Molding, Extrusion, Thermoforming, Blow Molding) • by Application (Food & Beverage, Consumer Electronics, Automotive, Pharmaceuticals, Industrial, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | BASF SE, TotalEnergies SE, SABIC, INEOS Styrolution Group GmbH, Trinseo PLC, LG Chem Ltd., Alpek S.A.B. de C.V., Formosa Chemicals & Fibre Corporation, Americas Styrenics LLC, Synthos S.A., Chi Mei Corporation, PS Japan Corporation, NOVA Chemicals Corporation, Kaneka Corporation, JSR Corporation, Sekisui Plastics Co., Ltd., Sonoco Products Company, Genpak, LLC, Dart Container Corporation, Total Petrochemicals & Refining USA, Inc. |
Frequently Asked Questions
Key players in the Polystyrene Packaging Market include BASF SE, TotalEnergies SE, SABIC, INEOS Styrolution Group GmbH, and Trinseo PLC, among others.
Key opportunities in the Polystyrene Packaging Market include scaling chemical recycling and depolymerization technology for food-grade recycled content and developing bio-attributed, mass-balance certified materials with lower carbon footprints.
The market is driven by sustained demand for cost-effective, lightweight protective packaging, combined with continued e-commerce growth requiring cushioning and insulation for shipped goods.
The Expandable Polystyrene (EPS) segment dominated the Polystyrene Packaging Market, accounting for approximately 38.20% market share.
The Asia Pacific region dominated the Polystyrene Packaging Market in 2025 with more than 54.00% share of overall polystyrene revenue, driven by the region's massive electronics manufacturing base and expanding packaged food consumption.
