
Polyurethane Adhesives Market Report Scope & Overview:
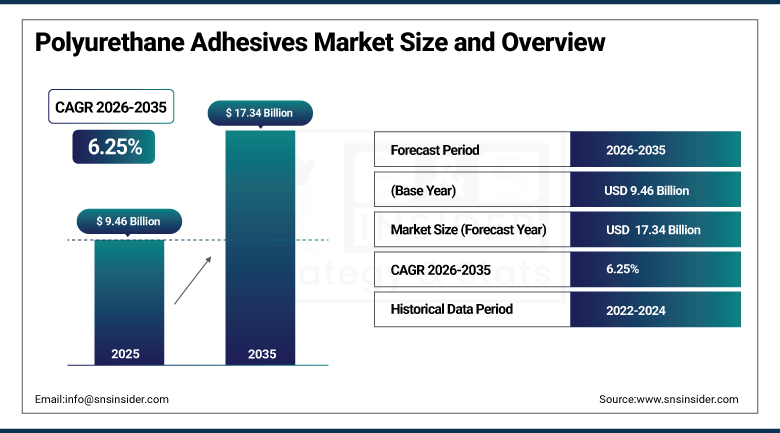
The Polyurethane Adhesives Market was valued at USD 9.46 Billion in 2025 and is expected to reach USD 17.34 Billion by 2035, growing at a CAGR of 6.25% from 2026-2035.
The Polyurethane Adhesives Market is growing, owing to an increase in the number of constructions, infrastructural developments, and the need for bonding materials that can be used in residential as well as commercial projects. The rise in automotive lightweighting programs is another factor that is contributing to the adoption of polyurethane adhesives because these adhesives bond different materials, and there is no use of mechanical fasteners. The rise in the production of furniture, woodworking, footwear, and packaging are some other factors contributing to market growth. The need for flexible and lightweight packaging is generating more opportunities for manufacturers of adhesives. Advancements in technology for reactive hot melt, water-based, and solvent-free polyurethane adhesives have improved their efficiencies.
In March 2025, H.B. Fuller launched Millennium PG-1 EF ECO2, a high-performance commercial roofing adhesive featuring the company's ECO2 Driven technology. The company stated the launch reflects continued investment in sustainability-aligned adhesive formulations for the building and construction sector.
To Get more information On Polyurethane Adhesives Market - Request Free Sample Report
Polyurethane Adhesives Market Trends
-
Growing shift toward 100% solids and reactive hot-melt technology reducing solvent emissions.
-
Rising demand for bio-based and low-VOC polyurethane adhesive formulations across major end markets.
-
Expanding use of structural polyurethane adhesives replacing welds and mechanical fasteners in vehicles.
-
Increasing manufacturer investment in specialty roofing and construction bonding technology.
-
Rising adoption of moisture-curing formulations supporting faster on-site construction assembly.
U.S. Polyurethane Adhesives Market Overview
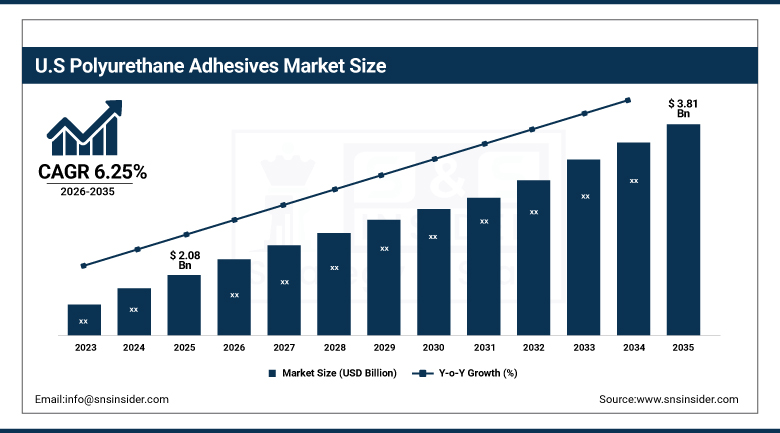
The U.S. Polyurethane Adhesives Market was valued at USD 2.08 Billion in 2025 and is expected to reach USD 3.81 Billion by 2035, growing at a CAGR of 6.25% from 2026-2035.
The U.S. Polyurethane Adhesives Market is growing due to increased construction and infrastructural development along with refurbishment of properties that create a need for strong bonding agents. Increased automobile production and lightweighting projects have contributed to an increase in demand for polyurethane adhesives as a way to join different dissimilar material such as metal, plastic, composite materials, etc. Increased manufacturing of furniture and wood working has further added to the growth of the market as there is an increased demand for moisture resistant and high strength bonding. Furthermore, increased packaging and footwear industry has led to an
In October 2024, 3M launched Fastbond Pressure Sensitive Adhesive 1049, a water-based, solvent-free adhesive delivered through Worthington Enterprises' portable PowerCore cylinder system. The company stated the product addresses demand for convenient, low-emission adhesive dispensing across construction and industrial applications.
Polyurethane Adhesives Market Segment Analysis
-
By Technology, the Solvent-Borne segment dominated the market with a 48.60% share in 2025, while the 100% Solids segment is the fastest growing with a CAGR of 6.61% during 2026-2035.
-
By Resin Type, the Thermoset segment dominated the market with a 56.80% share in 2025, while the Thermoplastic segment is the fastest growing with a CAGR of 6.90% during 2026-2035.
-
By Application, the Building & Construction segment dominated the market with a 31.00% share in 2025, while the Automotive & Transportation segment is the fastest growing with a CAGR of 7.20% during 2026-2035.
By Technology, Solvent-Borne Dominates the Market and 100% Solids/Reactive Hot Melt Grows Fastest
Solvent-Borne technology dominated the market in 2025, a position built on its proven formulation flexibility, established production infrastructure, and strong performance across bonding applications requiring extended open time and deep substrate penetration. Formulators favour this technology precisely because it delivers dependable adhesion across the widest range of porous and non-porous substrates, a combination that continues to make solvent-borne systems the default specification across established footwear, woodworking, and construction bonding applications worldwide, even as environmental regulation continues to reshape the broader technology landscape surrounding solvent-based formulations.
100% Solids Segment is projected to be the fastest-growing technology category over the forecast period. Manufacturers increasingly favour this format for its virtually zero volatile organic compound emissions and rapid green-strength development, which continues to accelerate production line speeds relative to conventional solvent-borne alternatives. As environmental regulation continues tightening across major manufacturing regions, this segment continues to pull ahead of solvent-borne and water-borne alternatives in overall percentage growth even as solvent-borne systems retain the larger overall installed application base.
By Resin Type, Thermoset Dominates the Market and Thermoplastic Grows Fastest
Thermoset resins dominated the market in 2025. Their superior heat resistance, chemical stability, and permanent bond strength once fully cured continue to anchor this segment's leading position across structural and semi-structural bonding applications requiring long-term durability under demanding environmental conditions. Construction and automotive manufacturers alike continue to specify thermoset formulations for applications where bond integrity must be maintained across extended service life and variable temperature exposure.
Thermoplastic resins are expected to be the fastest-growing resin type category over the forecast period. Rising demand for repositionable and heat-reactivatable bonding solutions continues to expand the addressable application base for this resin category beyond its historical footwear and packaging origins into broader industrial assembly contexts. As manufacturers increasingly value the processing flexibility thermoplastic formulations offer relative to permanently curing alternatives, this segment continues to close the gap with thermoset resins in overall market demand.
By Application, Building & Construction Dominates the Market and Automotive & Transportation Grows Fastest
Building & Construction applications dominated the market in 2025. Rising demand for housing and government infrastructure spending continues to represent the single largest driver of overall polyurethane adhesive consumption worldwide, spanning flooring, roofing, panel bonding, and insulation assembly applications across both residential and commercial construction projects. This foundational role continues to sustain construction as the largest application category by a clear margin, even as automotive applications continue gaining ground as vehicle lightweighting programs accelerate globally.
Automotive & Transportation applications are projected to expand fastest over the forecast period. Growing vehicle lightweighting initiatives continue to drive replacement of mechanical fasteners and welds with structural polyurethane adhesives capable of bonding dissimilar substrates including aluminum, composites, and advanced high-strength steel. As automakers increasingly pursue multi-material vehicle architectures to meet fuel efficiency and emissions targets, automotive and transportation applications continue closing the gap with construction in overall market demand.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
China |
39.70% |
|
North America |
United States |
81.90% |
|
Europe |
Germany |
32.50% |
|
Latin America |
Brazil |
43.60% |
|
Middle East & Africa |
United Arab Emirates |
31.40% |
North America Polyurethane Adhesives Market Insights
North America represents a significant regional market for polyurethane adhesives, anchored by the United States' mature automotive, aerospace, and construction industries supporting high-margin structural and specialty adhesive demand. The United States accounts for the substantial majority of regional demand, reflecting both its manufacturing scale and its concentration of leading specialty adhesive producers.
Canada and Mexico contribute additional regional volume through cross-border automotive and construction supply chain integration. Continued domestic investment in sustainability-aligned formulation research is expected to keep supporting steady regional market development even as growth in percentage terms trails faster-scaling Asia Pacific markets building out manufacturing capacity from a smaller existing base.
Europe Polyurethane Adhesives Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established adhesive manufacturers and continued advancement in sustainability-aligned formulation technology developed for automotive and construction applications. Germany's substantial automotive and industrial manufacturing base anchors regional demand, supported by a well-developed regulatory framework that continues to favour early adoption of low-emission adhesive technology across the country and neighbouring markets.
The United Kingdom, France, and Italy contribute additional regional demand, supported by established automotive and furniture manufacturing sectors. Continued European Union regulatory emphasis on volatile organic compound reduction supports steady regional demand for advanced, low-emission adhesive formulations.
Asia Pacific Polyurethane Adhesives Market Insights
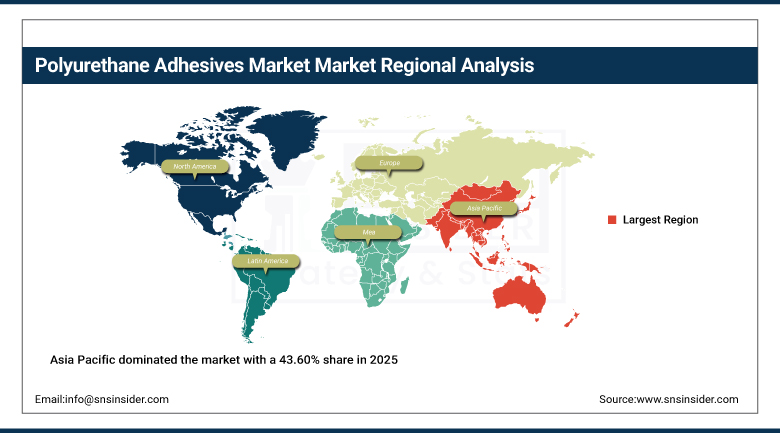
Asia Pacific dominated the market with a 43.60% share in 2025 and is also projected to expand at the fastest pace during the 2026-2035 forecast period, supported by rapid construction activity and expanding automotive manufacturing capacity across the region. China continues to anchor regional demand as construction and automotive supply chains expand across both established coastal manufacturing hubs and rapidly developing inland provinces, supported by sustained government infrastructure investment under successive five-year development plans.
India's expanding manufacturing base and growing construction sector continue adding meaningful regional growth as domestic producers scale capacity to serve rising adhesive demand. Japan and South Korea contribute further depth through established, technically advanced automotive and electronics manufacturing sectors, positioning the wider region to sustain both the largest revenue base and the fastest percentage growth of any global market through 2035.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Polyurethane Adhesives Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand on the strength of its growing automotive and construction manufacturing sector. Gradual growth in domestic manufacturing production continues to support steady regional market development.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding construction and industrial manufacturing investment is gradually increasing demand for specialty bonding solutions. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed industrial manufacturing infrastructure.
Growth Drivers: Construction Activity and Automotive Lightweighting
Construction and infrastructure investments are key driving factors of the Polyurethane Adhesives Market, fueled by increased demand for residential, commercial, and industrial constructions. Polyurethane adhesives are highly adhesive and flexible materials and have high durability and resistance to water. Thus, the material can be used in a number of applications within construction, including bonding concrete, wood, plastic, and glass. Lightweighting in automotive manufacturing is an additional factor that is fueling demand for polyurethane adhesives due to the use of lightweight and dissimilar materials.
The use of adhesives allows joining together different substrates, such as metal, composite, plastic, etc., while minimizing mechanical fastening and welding. In addition, rising demand for flexible and e-commerce packaging increases demand for adhesives for packaging applications. Rising furniture manufacturing and growing demand for aesthetically appealing wood products fuel the need for polyurethane adhesives in woodworking.
Restraints: Raw Material Price Volatility and Regulatory Compliance Costs
The volatility of the price in the raw materials becomes a serious constraint for the Polyurethane Adhesives market as the manufacturers have to use petrochemical-based isocyanates, polyols, solvents, and other chemicals. Fluctuations in the prices of crude oil, energy prices, feedstock, and logistics can influence manufacturing expenses. Small manufacturers can be especially sensitive to such price fluctuations due to low negotiating ability and inability to shift the increased cost to consumers.
The increasing difficulties in complying with the legislation emerge against the background of the continuous tightening of the legislation on the issue of volatile organic compounds, hazardous substances, workers’ safety, and emissions. It becomes necessary for the manufacturers to modify products, perform testing, certification and make changes in manufacturing process in order to meet new regulations.
Opportunities: Bio-Based Formulation Development and Reactive Hot Melt Expansion
Bio-based polyurethane adhesives are among the most promising development trends due to the increasing emphasis on environmental considerations both by manufacturers and end customers. Bio-based polyols and other renewable raw materials may reduce the need for oil-based components in adhesive products and support sustainable goals while preserving their performance properties. Manufacturers that manage to develop cost-efficient formulations with appropriate adhesion properties, durability, moisture resistance, and adequate processability will be able to capitalize on the increased demand for green solutions.
Reactive hot-melt adhesives represent another valuable growth opportunity for the industry because they combine high processing speed with excellent bonding properties and are able to replace solvent-based products. Rapid adoption in various sectors such as construction, woodworking, automotive, footwear, and packaging industries offers prospects for development of the technology. Improvements in terms of equipment compatibility, curing properties, and formulation properties will open new application areas for such products. Manufacturers that seek ways to decrease emissions during production and improve efficiency of their operations may adopt this type of products.
Recent Developments
-
2025: Sika AG completed the acquisition of HPS North America, strengthening the company's specialty construction and industrial adhesive manufacturing footprint across the region.
-
2024: Bostik launched a renewable-content packaging adhesive range containing 80% bio-based material, expanding the company's sustainable bonding solutions for flexible packaging applications.
-
2025: Henkel introduced a range of LED-curable Loctite adhesives, including the AA 3951/3953 and AA 3961/3963 product lines, designed for medical device assembly applications.
-
2025: Huntsman Advanced Materials launched a reformulated ARALDITE epoxy adhesive range free from intentionally added bisphenol A and CMR substances.
Polyurethane Adhesives Companies are:
-
Henkel AG & Co. KGaA
-
H.B. Fuller Company
-
Sika AG
-
Arkema S.A. (Bostik)
-
3M Company
-
Huntsman Corporation
-
Wacker Chemie AG
-
Illinois Tool Works Inc.
-
Avery Dennison Corporation
-
Ashland Inc.
-
DuPont de Nemours, Inc.
-
Mapei S.p.A.
-
Chemique Adhesives & Sealants Ltd.
-
Pidilite Industries Limited
-
Eastman Chemical Company
-
Covestro AG
-
PPG Industries, Inc.
-
Parker Hannifin Corporation (LORD Corporation)
Polyurethane Adhesives Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.46 Billion |
| Market Size by 2035 | USD 17.34 Billion |
| CAGR | CAGR of 6.25% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Solvent-Borne, Water-Borne, 100% Solids, Others) • By Resin Type (Thermoset, Thermoplastic) • By Application (Building & Construction, Automotive & Transportation, Footwear, Packaging, Woodworking, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Arkema S.A. (Bostik), 3M Company, Dow Inc., Huntsman Corporation, Wacker Chemie AG, Illinois Tool Works Inc., Avery Dennison Corporation, Ashland Inc., DuPont de Nemours, Inc., Mapei S.p.A., Jowat SE, Chemique Adhesives & Sealants Ltd., Pidilite Industries Limited, Eastman Chemical Company, Covestro AG, PPG Industries, Inc., Parker Hannifin Corporation (LORD Corporation) |

Frequently Asked Questions
Key players include Henkel, H.B. Fuller, Sika, Arkema (Bostik), 3M, Dow, Huntsman, Wacker Chemie, Illinois Tool Works, and Avery Dennison, among others.
Continued development of bio-based and biodegradable adhesive formulations and the rising demand for bio-based hot-melt adhesive technology represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by rising demand for housing and government infrastructure spending, combined with growing vehicle lightweighting programs favouring adhesive bonding over mechanical fasteners.
By Application, Building & Construction dominated the market in 2025, reflecting sustained demand across flooring, roofing, and panel bonding applications.
Asia Pacific dominated the market with a 43.60% share in 2025, supported by rapid construction activity and expanding automotive manufacturing capacity, led by China.
