
Pupillometer Market Report Scope & Overview:
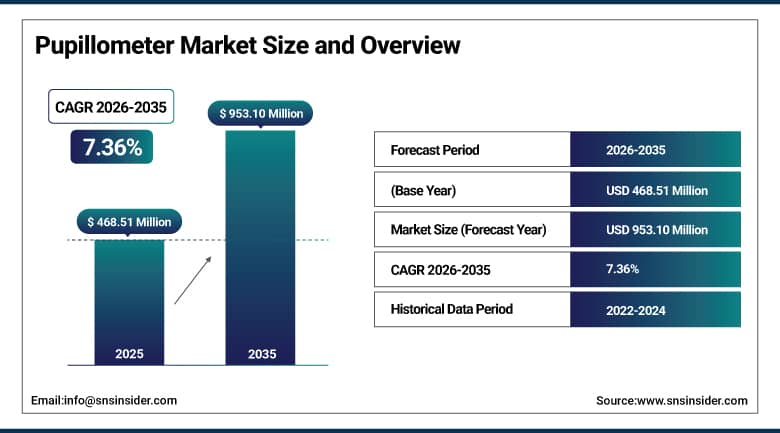
The Pupillometer Market was valued at USD 468.51 Million in 2025 and is expected to reach USD 953.10 Million by 2035, growing at a CAGR of 7.36% from 2026-2035.
The Pupillometer Market covers instruments that measure pupil size, reactivity, and light reflex using infrared video or digital sensors. Ophthalmologists use them to evaluate refractive surgery candidates and neurological disorders affecting the pupil, while neurocritical care teams use hand-held devices to track patients with brain injury, stroke, or cardiac arrest. Automated measurement replaces subjective penlight checks, which vary between observers. Demand is supported by guideline recognition of quantitative pupillometry, wider use in intensive care units, and the introduction of portable and smartphone-based devices that make screening possible outside specialty clinics. Manufacturers range from specialist neurocritical care device makers to large ophthalmic diagnostics groups and early-stage developers of phone-based tools. Distribution typically runs through direct sales teams in hospitals and through distributors in smaller markets, and service contracts, disposable sensors, and software subscriptions create recurring revenue streams beyond the initial device sale.
⮞A substudy of the BOX trial published in Intensive Care Medicine in August 2024, covering 710 comatose cardiac arrest survivors, found that a Neurological Pupil index of 2 or lower predicted an unfavorable outcome with no false positives from admission to 72 hours.
To Get More Information On Pupillometer Market - Request Free Sample Report
Pupillometer Market Trends
- Adoption of the Neurological Pupil index as an objective bedside metric in intensive care
- Development of smartphone-based and virtual reality pupillometry for screening
- Integration of pupillometer data with electronic health records and cloud platforms
- Use of artificial intelligence to interpret pupil dynamics and flag deterioration
- Growing use of pupillometry in anesthesia and pain monitoring research
U.S. Pupillometer Market Outlook
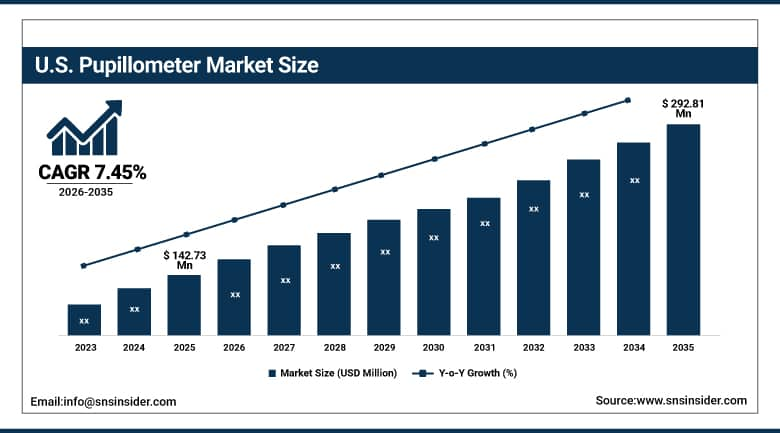
The U.S. Pupillometer Market was valued at USD 142.73 Million in 2025 and is expected to reach USD 292.81 Million by 2035, growing at a CAGR of 7.45% from 2026-2035.
The U.S. Pupillometer Market is the largest national market, supported by a large network of trauma centers, neurocritical care units, and ophthalmology practices. Hand-held automated pupillometers are widely deployed in intensive care units, and guideline recognition of quantitative pupillometry in cardiac arrest and traumatic brain injury care has strengthened hospital purchasing. Many devices are regulated as Class I products exempt from premarket notification, which shortens time to market. Vendors compete on data connectivity, ease of use for nurses, and integration with hospital information systems. Nursing leadership groups and intensive care physicians play a strong role in shaping purchasing, since adoption often begins as a pilot on a single unit and then spreads once staff report that the device saves time and improves communication across shifts.
⮞The Centers for Disease Control and Prevention reports about 214,110 traumatic brain injury-related hospitalizations in 2020 and 68,663 traumatic brain injury-related deaths in 2023, according to its page updated on 27 April 2026.
Pupillometer Market Segment Analysis
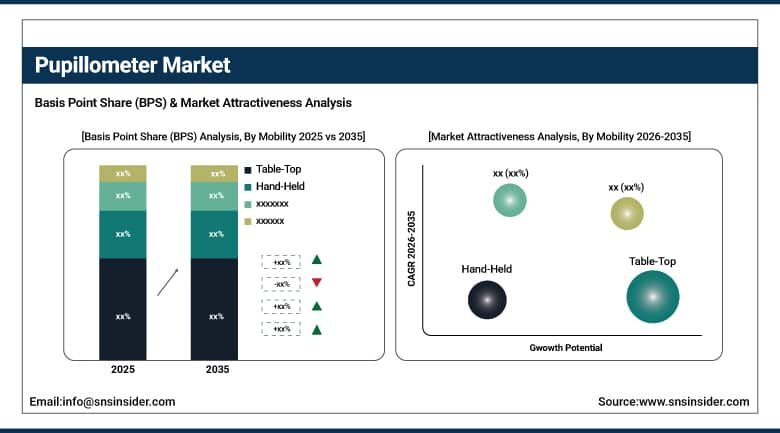
- By Mobility, the Table-Top segment dominated the Pupillometer Market with approximately 54.16% share in 2025, while the Hand-Held segment is the fastest growing with a CAGR of approximately 7.90%.
- By Type, the Video segment dominated the Pupillometer Market with approximately 55.26% share in 2025, while the Digital segment is the fastest growing with a CAGR of approximately 8.07%.
- By Application, the Ophthalmology segment dominated the Pupillometer Market with approximately 59.74% share in 2025, while the Neurology segment is the fastest growing with a CAGR of approximately 8.37%.
- By End User, the Hospitals segment dominated the Pupillometer Market with approximately 52.43% share in 2025, while the Eye Clinics segment is the fastest growing with a CAGR of approximately 8.51%.
By Mobility, Table-Top Dominates Pupillometer Market; Hand-Held to Register Fastest Growth.
Table-top devices lead because ophthalmology practices use them for refractive surgery screening, night vision assessment, and routine eye examinations, and they are often built into multifunction diagnostic platforms. These units offer stable positioning, controlled lighting, and detailed measurement of pupil size under varying conditions. Hospitals and eye centers value their accuracy and software analytics, and installed bases generate steady demand for upgrades and service contracts. Service networks and calibration programs maintained by manufacturers support long equipment lifecycles in practices worldwide.
Hand-held devices are growing fastest as intensive care teams, emergency departments, and field clinicians demand portable tools for bedside neurological checks. These pupillometers deliver quantitative readings in seconds, reduce subjectivity, and connect with electronic records. Smartphone-based and battery-powered designs lower costs and extend use to community clinics and low-resource settings. Developers are also adding artificial intelligence and wireless data transfer to support remote monitoring and trend analysis. Clinical champions in intensive care units often drive early hospital purchasing decisions.
By Type, Video Dominates Pupillometer Market; Digital to Register Fastest Growth.
Video pupillometers lead because infrared video capture records the full light reflex curve, allowing precise measurement of constriction velocity, latency, and dilation. Clinicians can review recorded sequences and compare them over time, which supports research and documentation. The technology is well established in both ophthalmic and neurological devices, and software analysis tools turn raw video into standardized indices used in clinical guidelines and hospital protocols. Large clinical image libraries support algorithm training and validation studies for new software products.
Digital pupillometers are growing fastest because they use compact infrared sensors and processors that reduce size, cost, and power consumption. These designs enable smartphone attachments and wearable formats, and they fit workflows in emergency and primary care settings. Algorithms improve accuracy under variable lighting, and manufacturers are validating them against established video devices. Their lower price makes them attractive for small clinics and emerging markets. Regulators also treat many such devices as lower-risk products, shortening the path to market.
By Application, Ophthalmology Dominates Pupillometer Market; Neurology to Register Fastest Growth.
Ophthalmology leads because pupil measurement is a routine part of refractive surgery planning, cataract assessment, contact lens fitting, and screening for conditions affecting pupil response. Eye clinics and hospital departments own large numbers of devices, and many are integrated with corneal topographers and aberrometers. Rising volumes of laser vision correction and cataract surgery sustain demand, along with growing awareness of pupil size as a factor in night vision quality. Surgeons also rely on pupil data for lens selection decisions.
Neurology is growing fastest as quantitative pupillometry becomes part of standard monitoring for traumatic brain injury, stroke, intracranial pressure, and cardiac arrest. Studies show that abnormal pupil indices relate to higher mortality and poor outcomes, giving clinicians an objective warning signal. Guideline bodies are citing the technique, and intensive care units are adding devices to nursing workflows. Anesthesia and pain research form a smaller but emerging group of applications. Training programs for bedside nurses reinforce correct measurement technique daily.
⮞The Lancet Neurology ORANGE study, which included 514 patients and 40,071 pupillometry measurements, found that 47% had at least one abnormal Neurological Pupil index and that an abnormal result was associated with higher mortality.
By End User, Hospitals Dominate Pupillometer Market; Eye Clinics to Register Fastest Growth.
Hospitals lead because they operate the intensive care units, emergency departments, and ophthalmology departments where pupil assessment is most frequent. Procurement budgets allow for multiple devices across wards, and hospital systems are standardizing on a single platform to compare data between sites. Neurosurgery and trauma services in particular rely on repeated measurements, and teaching hospitals run studies that support guideline adoption and device upgrades. Capital committees often approve devices after pilot units show better documentation quality and staff confidence.
Eye clinics and vision centers are growing fastest as private ophthalmology practices expand and refractive surgery becomes more accessible. These sites invest in compact table-top and digital devices that fit into pre-screening workflows with limited staff. Optometry chains and ambulatory surgery centers add further demand. Expansion of such clinics in Asia and Latin America is increasing the installed base, and leasing arrangements help smaller practices acquire equipment. Financing and leasing plans reduce the upfront burden on small independent practices.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
90.00% |
|
Europe |
Germany |
23.64% |
|
Asia Pacific |
China |
34.81% |
|
Latin America |
Brazil |
52.17% |
|
Middle East & Africa |
Saudi Arabia |
31.28% |
North America Pupillometer Market Insights
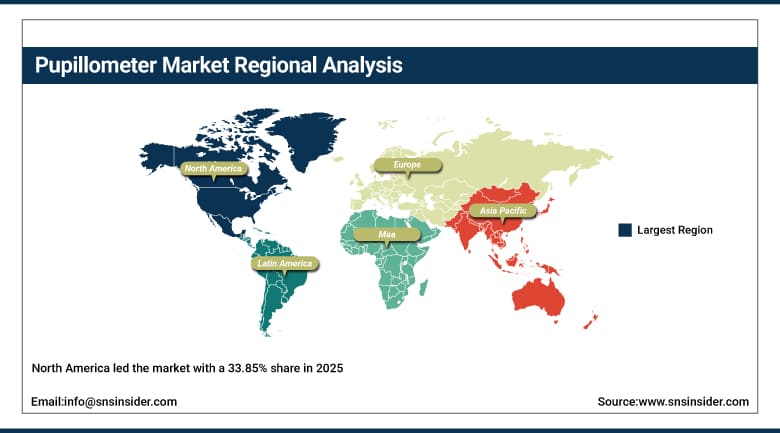
North America led the market with a 33.85% share in 2025, reflecting strong neurocritical care infrastructure, high volumes of refractive surgery, and early adoption of connected medical devices. The United States generates most regional demand, while Canada contributes through hospital procurement and provincial stroke and trauma programs. Several leading hand-held pupillometer developers are based in the region, and clinical research on pupil indices is concentrated in its academic centers. Insurance coverage for refractive and cataract procedures varies, but patient demand for premium vision outcomes supports investment in advanced diagnostics at private practices across the region. Veterans and military health systems also run neurotrauma programs that use pupil assessment.
Guideline recognition has been a defining factor. Professional societies in resuscitation and trauma care have referenced objective pupillometry, and hospitals have responded by adding devices to intensive care workflows. Reimbursement for the devices themselves is limited, so purchases come from capital or operating budgets, often justified by nursing time saved. Mexico is counted within Latin America in this report. Telehealth and remote neurological consultation add further interest in connected devices. Training webinars from manufacturers and professional societies help nurses learn correct technique, and published case series continue to broaden awareness among emergency physicians and neurosurgeons. Hospital-at-home and tele-ICU programs are also exploring remote review of readings.
⮞In November 2020, the American Heart Association's CPR and ECC guidelines were reported by a leading device maker to include automated pupillometry as an objective measure supporting prognosis after cardiac arrest.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Pupillometer Market Insights
Europe ranks second, with Germany, France, the United Kingdom, Italy, and Spain accounting for most demand. Neurocritical care units across the region are adopting automated pupillometry, and ophthalmic table-top devices are widely used in refractive and cataract practice. National health systems weigh evidence carefully, and health technology bodies have reviewed pupillometers while calling for stronger studies. European suppliers offer portable video pupillometers designed for intensive care and anesthesia. Regional ophthalmology societies also hold education events that showcase diagnostic technology to practicing surgeons and technicians. Portable video pupillometers from French suppliers are used in anesthesia.
Regulation under the medical device framework requires clinical evaluation and post-market surveillance, which raises costs for smaller manufacturers but supports quality. Hospitals in Western Europe are the main buyers, and procurement is often managed through regional tenders. Research collaborations between intensive care societies are generating multicenter data, and conference presentations from Spanish and French units show growing clinical interest in comparing manual and quantitative assessments. Language requirements, interoperability standards, and data protection rules add further considerations for suppliers, so companies often partner with local distributors that understand national reimbursement and hospital purchasing procedures. Sustainability goals are encouraging suppliers to design recyclable sensor components.
⮞A National Institute for Health and Care Excellence medtech briefing reviewed six observational studies including 1,217 people with a pupillometer and found that none were conducted in the United Kingdom.
Asia Pacific Pupillometer Market Insights
Asia Pacific is the fastest growing region with an expected CAGR of 8.71% from 2026 to 2035, led by China, Japan, India, South Korea, and Australia. Expanding intensive care capacity, rising refractive surgery volumes, and a growing number of private eye clinics are widening the customer base. Local research groups are validating pupillometry in anesthesia and critical care, and local manufacturers are launching lower-cost devices for regional hospitals. Government programs that build stroke and trauma networks are further expanding the number of intensive care beds equipped with advanced monitoring tools across the region. Hospital chains in Southeast Asia are also standardizing on compact devices for new intensive care units.
India is notable for the development of low-cost handheld and smartphone-based pupillometers by eye institutes and technology firms, which could expand screening in primary care. Japan is a mature ophthalmic device market with strong table-top device use. China is building neurocritical care networks and funding clinical studies. Distribution partnerships with global suppliers remain important, and regulatory approval timelines differ across countries. Public-private partnerships with eye hospitals and nonprofit organizations are helping test new devices in community screening camps, and training of technicians in rural areas is improving the quality and reach of examinations in underserved districts. Mobile health startups are building screening apps around pupil response.
MEA & Latin America Pupillometer Market Insights
The expansion of Latin America is happening slowly because of the investment by private hospitals in Brazil, Mexico, Argentina, and Colombia into devices for neurocritical care and ophthalmology. Mexico is one of the countries belonging to Latin America based on market projections, and Mexico's increasing number of private clinics dedicated to eyes is aiding in the sale of table-top devices. Clinical education materials in Portuguese and Spanish are educating the doctors about quantitative pupillometry, and the distributors play an important part in importation and maintenance of the devices. The regional societies organize congresses where the devices are introduced by the companies, and the financing helps in acquiring the equipment through private clinics in spite of fluctuating currency.
The Middle East and Africa region is led by Gulf countries, where modern hospitals and trauma centers purchase advanced monitoring equipment. Saudi Arabia and the United Arab Emirates are expanding intensive care capacity as part of national health strategies. In Africa, adoption is limited by cost and infrastructure, though low-cost smartphone-based devices may extend access over time. International suppliers rely on regional distributors and partnerships with academic hospitals to build awareness. Joint ventures with local healthcare groups are becoming more common. Government hospitals purchase through national tenders.
Market Dynamics
Growth Drivers: Guideline Recognition and Rising Brain Injury Burden Drive Growth in the Pupillometer Market
Guideline recognition is a major driver. Professional bodies have begun recommending quantitative pupillometry for traumatic brain injury and for prognostication after cardiac arrest, which gives hospitals a clear justification for purchases. Objective measurement reduces disagreement between nurses and physicians, supports early detection of neurological worsening, and improves documentation. As more units adopt protocols that rely on pupil indices, device placement per bed is expected to rise. Hospital quality teams also include pupil monitoring in post-cardiac arrest bundles and neuroprognostication checklists, which further embeds the technology in routine practice and supports consistent training of rotating clinical staff in busy units. Competitive tenders often reference guideline language when specifying devices.
The burden of brain injury and stroke is a second driver. Ageing populations, road traffic injuries, and falls generate large numbers of patients who require repeated neurological checks. Hospitals under staffing pressure value tools that make checks faster and consistent. Growth in intensive care capacity in emerging economies, together with rising refractive surgery volumes, adds to demand for both hand-held and table-top instruments across care settings. Rehabilitation hospitals and long-term acute care units are another emerging setting, since patients recovering from severe injury benefit from repeated objective neurological checks, and insurers favor tools that help avoid unnecessary transfers back to intensive care. Rising sports-related concussion awareness is a further contributor.
⮞The American College of Surgeons revised its traumatic brain injury guidelines on 29 October 2024 to recommend quantitative pupillometry, according to a device maker's news page.
Restraints: High Equipment Costs and Limited Reimbursement Restrain Growth in the Pupillometer Market
The high costs associated with the acquisition of a hand-held pupillometer limit its use especially with regards to the need for disposables and software licensing. Hospitals with limited capital will put off procurement while smaller hospitals rely on penlight examination. Without any individualized payment system for pupillometry, any financial case that would be put together depends upon non-tangible advantages like saving nurse time or avoiding complications. The procurement team also considers other expenses related to training, software integration and sensors that lead to total cost of ownership being higher than the initial cost of acquisition.
Evidence gaps add to the challenge. Health technology assessments have noted that many studies are observational, small, or conducted in a limited number of countries. Clinicians may question how to act on abnormal readings in the absence of standardized thresholds. Measurement can be affected by medications, eye disease, and lighting conditions. Variation between devices and algorithms also complicates data comparison, which slows the transition to universal use. Professional societies may be hesitant to issue strong recommendations until randomized trials link pupillometry-guided management to better patient outcomes, so vendors continue to fund prospective studies that could strengthen the clinical case. Prospective multicenter registries could address several of these uncertainties.
Opportunities: Smartphone-Based Devices and Artificial Intelligence Create Opportunities in the Pupillometer Market
Smartphone-based and low-cost handheld pupillometers offer an opportunity to extend screening beyond hospitals. Eye institutes and technology companies are developing devices that use phone cameras or compact sensors, and these can serve primary care, community outreach, and emergency response. Lower prices make them attractive for emerging markets, where trained specialists are scarce. Partnerships with manufacturers and distributors can accelerate commercialization and training. Telemedicine platforms can integrate captured pupil data so that distant specialists can review findings, and public health programs may adopt such tools for screening at schools, workplaces, and community events. Open-source algorithms may further speed local innovation.
Artificial intelligence provides a second opportunity. Algorithms can analyze pupil dynamics to detect subtle changes that precede clinical deterioration, and they can combine pupil data with vital signs to produce early warning scores. Virtual reality headsets that include pupillometry among broader eye tests are creating new pretest workflows for optometry. Cloud analytics and electronic health record integration allow hospitals to monitor trends across wards and benchmark performance. Regulatory pathways for software that supports clinical decisions are becoming clearer, which should encourage investment from both established manufacturers and technology start-ups seeking to enter the field. Cloud-based platforms can send alerts to clinicians.
Recent Developments:
- In September 2025, NeurOptics reported that quantitative pupillometry was included in consensus guidelines issued by the Extracorporeal Life Support Organization, adding to the clinical guidance that supports use of its NPi platform. The company noted that its NPi-300 device and cloud connectivity were designed to support such protocols in extracorporeal support programs and intensive care units that monitor critically ill patients. The inclusion adds to earlier recognition of the technique in resuscitation and brain injury guidance and may support wider use in extracorporeal programs.
- In September 2026, Heru launched PretestPro software for its Heru Prime virtual reality headset, a tool for streamlined eye exam pretesting that includes quantitative pupillometry and relative afferent pupillary defect detection. The headset combines several eye tests in a single workflow, and the company has said that more than one million eyes have been tested on its platform. Optometry practices are the intended users, with the aim of reducing technician time per patient.
- In January 2026, the L V Prasad Eye Institute and Forus Health signed a memorandum of understanding to bring the PupilN portable, phone-powered pupillometer to market, with global launch expected in the coming months. PupilN is a handheld device developed at the institute's Centre for Technology Innovation, and the partnership aims to prepare the product and a companion screening tool for commercial production and distribution. The institute has described the technology as aimed at expanding access to low-cost diagnostics.
Pupillometer Market Key Players are:
- NeurOptics
- Idmed
- Heru
- Forus Health
- LV Prasad Eye Institute
- Brightlamp
- Konan Medical
- Topcon
- NIDEK
- Reichert
- Visionix
- Haag-Streit
- Plusoptix
Pupillometer Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 468.51 Million |
| Market Size by 2035 | USD 953.10 Million |
| CAGR | CAGR of 7.36% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Mobility (Table-Top and Hand-Held) • By Type (Video and Digital) • By Application (Ophthalmology, Neurology, and Others) • By End User (Hospitals, Eye Clinics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | NeurOptics, Idmed, Heru, Forus Health, LV Prasad Eye Institute, Brightlamp, Konan Medical, Topcon, NIDEK, Reichert, Visionix, Haag-Streit, Plusoptix |

Frequently Asked Questions
Key players in the market include NeurOptics, Idmed, Heru, Forus Health, Konan Medical, and Topcon, among others.
Key opportunities include smartphone-based low-cost devices for primary care and artificial intelligence that detects early neurological deterioration.
Guideline recognition and the rising burden of brain injury are the major growth factors, as they support objective pupil monitoring in intensive care.
The Table-Top segment dominated the market in 2025 with approximately 54.16% share, supported by ophthalmology practices and multifunction diagnostic platforms.
North America dominated the market in 2025 with approximately 33.85% share, reflecting strong neurocritical care infrastructure and early adoption of connected medical devices.
