
Railway Management System Market Report Scope & Overview:
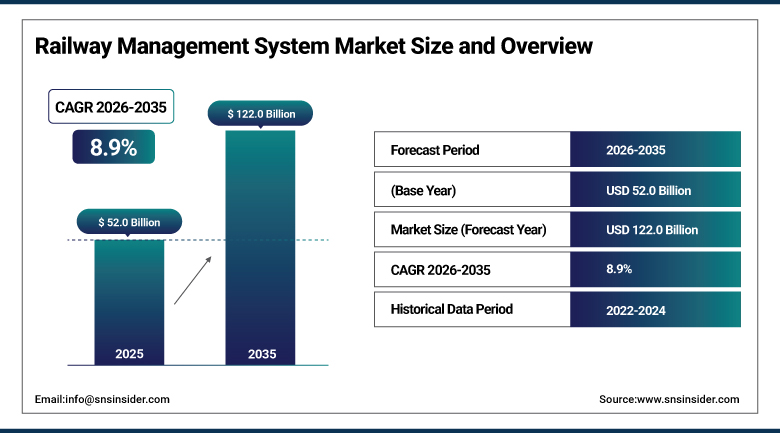
The Railway Management System Market was valued at USD 52.0 Billion in 2025 and is expected to reach USD 122.0 Billion by 2035, growing at a CAGR of 8.9% from 2026–2035.
The Railway Management System Market is witnessing strong growth, owing to the increasing investments made by government and railway bodies in upgrading rail infrastructure to be efficient, well-connected, and automated. Urbanization and increase in the number of passengers are resulting in expansion of metro, high-speed, and conventional railways, and there is a need for effective solutions for managing traffic and controlling trains. Focus on safety, efficiency, and real-time monitoring of rail operations is fostering the implementation of digital signals, communications, and asset management systems in railways. Artificial intelligence, IoT, cloud computing, and predictive analytics are contributing towards effective fleet management, infrastructure maintenance, and scheduling. Moreover, upgrade of existing old railway infrastructure in developed countries along with rapid development of rail networks in developing countries is also contributing to growth in investments in railway management systems.
Deutsche Bahn signed a €6.3 billion framework agreement in February 2025 with Alstom, Hitachi Rail, Siemens Mobility, and MerMec Deutschland to supply and install digital interlocking technology, ETCS signaling, and integrated control systems across the German rail network. The deal commits DB to procuring 15,500 control units by 2028, with implementation running through 2032, and replaces what had been a patchwork of individual project contracts with a single, streamlined procurement framework, itself a sign of how central digital rail management has become to a national operator's long-term infrastructure planning.
To Get more information Railway Management System Market - Request Free Sample Report
Railway Management System Market Trends
-
Cloud-based deployment is gaining ground over on-premise systems, providing railway operators with scalability, remote monitoring, and real-time data access across complex networks.
-
Rising passenger expectations are driving operators to integrate real-time information, Wi-Fi connectivity, and entertainment services as standard features across major routes.
-
IoT and AI-powered predictive maintenance are expanding beyond high-speed and metro networks into conventional rail, helping operators detect equipment issues before disruptions occur.
-
Communication-based train control is expanding across metro and urban transit networks, enabling cities to increase line capacity without constructing entirely new infrastructure.
-
Cybersecurity is becoming a core procurement requirement as signaling and control systems adopt cloud architectures, increasing potential vulnerabilities across safety-critical railway infrastructure.
U.S. Railway Management System Market Outlook
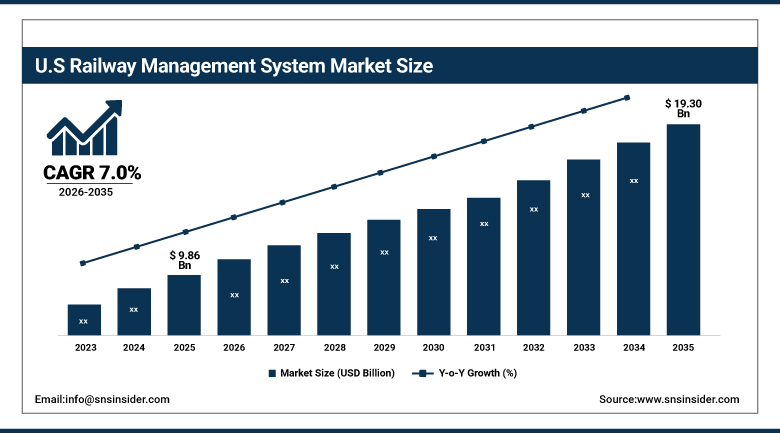
The U.S. Railway Management System Market was valued at approximately USD 9.86 Billion in 2025 and is expected to reach approximately USD 19.30 Billion by 2035, growing at a CAGR of approximately 7.0%.
Demand in the United States spans both conventional freight rail, which moves a substantial share of the country's domestic cargo, and a growing base of urban transit and commuter rail systems modernizing decades-old signaling infrastructure. Federal infrastructure funding continues supporting rail modernization projects, though the country's rail network remains more fragmented across private freight operators and public transit agencies than the centralized national systems common in parts of Europe and Asia. That fragmentation shapes procurement patterns, with individual project contracts remaining more common than the kind of single national framework agreements some other countries have pursued.
Amtrak's ongoing modernization of the Northeast Corridor, alongside urban transit signaling upgrades and high-speed rail feasibility studies in several states, continues to drive demand for AI-enabled, IoT-enabled, and cloud-based signaling systems from suppliers including Siemens Mobility, Alstom, and Hitachi Rail. That investment reflects a broader pattern across the U.S. rail sector, where aging signaling infrastructure is increasingly being replaced project by project rather than through the kind of single national framework agreement Germany's Deutsche Bahn has pursued.
Railway Management System Market Segment Analysis
-
By Offering, the Solutions segment dominated the Railway Management System Market with approximately 63.7% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 10.4%.
-
By Deployment, the On-Premise segment dominated the Railway Management System Market with approximately 67.1% share in 2025, while the Cloud segment is the fastest growing with a CAGR of approximately 12.6%.
-
By Railway Type, the Conventional Railways segment dominated the Railway Management System Market with approximately 64.1% share in 2025, while the Metro & Urban Transit segment is the fastest growing with a CAGR of approximately 11.8%.
-
By Application, the Passenger Transportation segment dominated the Railway Management System Market with approximately 63.7% share in 2025, and is also the fastest growing with a CAGR of approximately 10.2%.
-
By Solution Type, the Rail Traffic Management segment dominated the Railway Management System Market with approximately 28.0% share in 2025, while the Communication & Signaling segment is the fastest growing with a CAGR of approximately 11.2%.
By Offering, solutions dominates, services grows fastest
Solutions held the larger share of the offering segment in 2025, since core technologies, signaling, train control, traffic management, and communications infrastructure, form the foundation of any modern railway management ecosystem. Operators and infrastructure managers continue prioritizing these high-value technology deployments to enhance safety, increase network capacity, and improve operational reliability.
Services are growing fastest as rail operators increasingly require ongoing support to manage complex, digitally enabled networks. As signaling, traffic management, and predictive maintenance systems become more sophisticated, demand rises for system integration, upgrades, and operations outsourcing, particularly as legacy infrastructure modernization projects create long-term service contract opportunities.
By Deployment, on-premise dominates, cloud grows fastest
On-premise deployment accounted for the largest deployment share in 2025, valued for the superior control, security, and reliability it offers over locally stored and managed critical operational data. That level of direct control remains especially important for safety-critical signaling and train control systems, where operators have historically been cautious about ceding infrastructure control to third-party cloud providers.
Cloud deployment is growing fastest as its scalability, cost-efficiency, and ability to provide real-time access to data increasingly outweigh the control advantages on-premise systems have traditionally offered. Integration of IoT and AI technologies is further boosting cloud adoption, since these capabilities depend heavily on the kind of centralized data access and computing power cloud infrastructure delivers more readily than isolated on-premise systems.
By Railway Type, conventional railways dominates, metro & urban transit grows fastest
Conventional railways held the largest share of the railway-type segment in 2025, reflecting the sheer scale of existing conventional rail networks worldwide relative to newer high-speed and metro infrastructure. Ongoing modernization of this large installed base keeps conventional rail the dominant category by both track mileage and total management system investment.
Metro and urban transit is the fastest-growing railway type as expanding urban mass transit infrastructure worldwide drives demand for advanced signaling and traffic management technology capable of supporting higher train frequencies. Cities looking to increase line capacity without the cost and disruption of building entirely new infrastructure are turning to communication-based train control and similar technologies at an accelerating pace.
By Application, passenger transportation dominates and grows fastest
Passenger transportation accounted for the largest application share in 2025, reflecting the scale of global passenger rail networks and the growing sophistication of passenger-facing technology, from real-time information systems to integrated ticketing and connectivity services. Rising passenger expectations continue pushing operators to treat these systems as core infrastructure rather than optional amenities.
Passenger transportation is also the fastest-growing application, an unusual case where the already-dominant segment continues gaining share rather than ceding ground to freight. Expanding urbanization and growing investment in high-speed and metro passenger rail projects worldwide are driving this continued acceleration, even as freight rail modernization proceeds along its own steadier growth path.
By Solution Type, rail traffic management dominates, communication & signaling grows fastest
Rail traffic management systems held the largest solution-type share in 2025, serving as the central nervous system that coordinates train movements, schedules, and network capacity across an operator's entire rail network. Their foundational role in preventing conflicts and maximizing network throughput keeps this the largest single solution category.
Communication and signaling solutions are growing fastest as communication-based train control and other advanced signaling technologies expand rapidly across metro and urban transit networks worldwide. Growing government investment in digital rail infrastructure, exemplified by major national framework agreements in several countries, is directly reinforcing this segment's above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Europe |
Germany |
24.0% |
|
North America |
United States |
79.0% |
|
Asia Pacific |
China |
38.0% |
|
Latin America |
Brazil |
36.0% |
|
Middle East & Africa |
Saudi Arabia |
34.0% |
North America Railway Management System Market Insights
North America remains a substantial railway management system market, with the United States accounting for the large majority of regional demand across both conventional freight rail and growing urban transit modernization. Federal infrastructure funding continues supporting rail modernization projects, though the market remains more fragmented across private freight operators and public transit agencies than the centralized systems common elsewhere.
Canada contributes additional demand through its own freight and passenger rail modernization efforts, while Mexico's market continues expanding alongside growing cross-border freight rail investment. Cross-border supply relationships tie much of North American demand together, with major technology suppliers typically serving all three markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Railway Management System Market Insights
Europe's Railway Management System Market is supported by extensive rail networks, strong government focus on sustainable transportation, and ongoing modernization of signaling and traffic management infrastructure. Increasing adoption of digital rail technologies, automated train control, predictive maintenance, and real-time passenger information systems is improving operational efficiency and safety. Investments in high-speed rail corridors, cross-border connectivity, and smart urban transit are further supporting demand for advanced railway management solutions across the region.
France, the United Kingdom, and Switzerland contribute meaningful volume as well, each with well-established rail networks investing in signaling modernization and digital traffic management. EU-level interoperability requirements and European Railway Agency standards shape technology specification across the region more directly than in most other markets.
Asia Pacific Railway Management System Market Insights
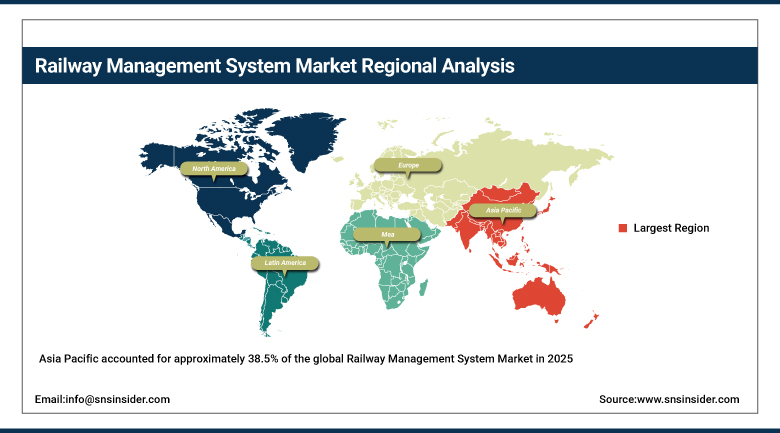
Asia Pacific accounted for approximately 38.5% of the global Railway Management System Market in 2025 and is expected to register the fastest regional growth through 2035. Growth is driven by rapid urbanization, massive high-speed rail expansion, and substantial government investment in digital railway infrastructure across China and India. Expansion of urban mass transit systems across the region's largest cities continues adding significant new demand, alongside modernization of high-speed and conventional rail networks.
China's extensive high-speed rail network and continued metro system expansion give the region substantial baseline demand, while Japan's mature, technology-forward rail sector contributes deep engineering expertise. Southeast Asian markets are following a similar urbanization-driven growth trajectory as regional rail infrastructure investment continues expanding.
MEA & Latin America Railway Management System Market Insights
The Middle East and Africa host a smaller but rapidly developing railway management system market, with Saudi Arabia driving demand through massive infrastructure projects including the Riyadh Metro and Haramain High-Speed Railway, tied to the country's broader Vision 2030 economic diversification strategy. That scale of investment has made Saudi Arabia one of the fastest-growing individual national markets globally.
Latin America is a growing market led by Brazil, where expanding urban transit and freight rail modernization continue driving demand for digital railway management technology. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing rail infrastructure investment programs.
Market Dynamics
Growth Drivers: Urbanization and government infrastructure investment fueling adoption
Rising urbanization and growing passenger and freight volumes are one of the clearest forces behind rising railway management system demand, as expanding urban populations push cities toward mass transit systems that require sophisticated traffic management and signaling technology to operate safely at high frequency. That demographic tailwind gives the market a demand base that should keep expanding for years across the fastest-urbanizing regions.
Substantial government investment in rail modernization adds a second major driver, as national and regional governments worldwide fund digital signaling upgrades, high-speed rail expansion, and urban transit projects to meet growing mobility demand and sustainability goals. Large national framework agreements, of the kind several major European rail operators have recently signed, are reinforcing this investment trend at a scale individual project contracts rarely achieve.
Restraints: High implementation costs and interoperability challenges limiting adoption speed
High capital and integration costs remain a genuine barrier, particularly for operators in emerging markets where modernizing an entire signaling and traffic management network requires investment well beyond what many rail agencies can fund without substantial government backing. That cost barrier can slow modernization timelines even where the operational and safety case for upgrading is clear.
Interoperability and standardization issues add a further restraint, since railway networks that span multiple operators, countries, or legacy technology generations often struggle to integrate new digital systems cleanly with existing infrastructure. That technical complexity can extend project timelines and increase costs well beyond initial estimates, particularly on cross-border or multi-operator networks.
Opportunities: Predictive maintenance and rail infrastructure expansion in emerging markets opening new growth avenues
Predictive maintenance and asset optimization technology offers a genuine path to reducing operator costs while improving network reliability, letting rail operators identify equipment issues before they cause service disruptions rather than relying on fixed maintenance schedules. Providers that build strong predictive maintenance capability are positioned to capture premium service contracts as operators increasingly prioritize lifecycle cost optimization over large upfront capital investments.
Rail infrastructure expansion in emerging markets represents a second significant opportunity, as countries across Asia, the Middle East, and Latin America continue investing heavily in new high-speed, metro, and conventional rail networks that require comprehensive management systems from the ground up. Companies that build strong relationships with governments and infrastructure developers in these fast-growing markets are positioned to capture disproportionate long-term growth.
Recent Developments:
-
December 2025: Siemens Mobility and Sporveien commissioned an advanced CBTC system on the Oslo Metro, the first deployment of its kind in Norway, part of a €270 million modernization that boosted capacity from 28 to 36 trains per hour on an initial network section.
-
December 2025: Wabtec Corporation acquired Frauscher, strengthening its train detection, axle counting, and wayside object-control technology portfolio.
-
July 2026: Hitachi Rail highlighted cloud-based signaling solutions for safety-critical applications, including IEC 62443 Security Level 3-certified systems, reflecting growing emphasis on cybersecurity in next-generation signaling procurement.
-
2024: Alstom expanded its manufacturing footprint in Türkiye through the acquisition of Duray Ulasim Sistemleri, supporting regional component production and supply resilience while divesting its North American conventional signaling business to sharpen its core mobility focus.
Railway Management System Market Key Players
-
Siemens AG
-
Alstom SA
-
Hitachi Rail Ltd.
-
Thales Group
-
Huawei Technologies Co., Ltd.
-
Wabtec Corporation
-
ABB Ltd.
-
Cisco Systems, Inc.
-
IBM Corporation
-
Indra Sistemas S.A.
-
Nokia Corporation
-
Toshiba Corporation
-
Honeywell International Inc.
-
CAF (Construcciones y Auxiliar de Ferrocarriles, S.A.)
-
DXC Technology Company
-
Trimble Inc.
-
Frequentis AG
-
Advantech Co., Ltd.
-
Kyosan Electric Manufacturing Co., Ltd.
-
Fujitsu Limited
Railway Management System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 52.0 Billion |
| Market Size by 2035 | USD 122.0 Billion |
| CAGR | CAGR of 8.9% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Offering (Solutions, Services) • By Deployment (Cloud, On-Premise) • By Railway Type (Conventional Railways, High-Speed Rail, Metro & Urban Transit) • By Application (Passenger Transportation, Freight Transportation) • By Solution Type (Rail Traffic Management, Train Control System, Asset Management, Passenger Information System, Communication & Signaling, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens AG, Alstom SA, Hitachi Rail Ltd., Thales Group, Huawei Technologies Co., Ltd., Wabtec Corporation, ABB Ltd., Cisco Systems, Inc., IBM Corporation, Indra Sistemas S.A., Nokia Corporation, Toshiba Corporation, Honeywell International Inc., CAF (Construcciones y Auxiliar de Ferrocarriles, S.A.), DXC Technology Company, Trimble Inc., Frequentis AG, Advantech Co., Ltd., Kyosan Electric Manufacturing Co., Ltd., Fujitsu Limited. |
Frequently Asked Questions
Key players include Siemens AG, Alstom SA, Hitachi Rail Ltd., Thales Group, and Huawei Technologies Co., Ltd., among others.
Key opportunities include cloud migration, predictive maintenance, cybersecurity, communication-based train control, metro expansion, high-speed rail, and digital infrastructure modernization.
Rising urbanization and growing passenger and freight volumes, combined with substantial government investment in rail modernization and digital signaling infrastructure.
Conventional Railways dominated with approximately 64.1% share in 2025.
Asia Pacific dominated the Railway Management System Market in 2025.
