
Respiratory Care Devices Market Report Scope & Overview:
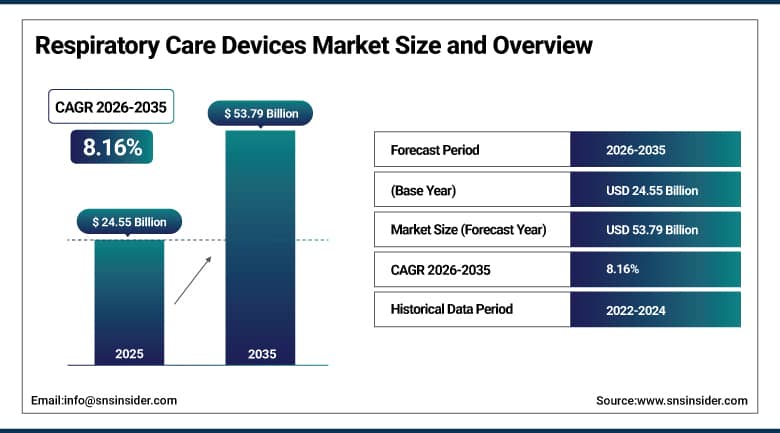
The Respiratory Care Devices Market was valued at USD 24.55 Billion in 2025 and is expected to reach USD 53.79 Billion by 2035, growing at a CAGR of 8.16% from 2026-2035.
Respiratory care devices span the full range of equipment used to diagnose, monitor, and treat breathing disorders, from continuous positive airway pressure machines that keep an obstructed airway open through the night to hospital ventilators that sustain critically ill patients and oxygen concentrators that let people with chronic lung disease continue living independently at home. The category has grown from a narrow set of hospital-based acute-care equipment into a genuinely broad ecosystem spanning therapeutic devices, diagnostic and monitoring tools, and the consumables and accessories, including masks, tubing, and filters, that every therapeutic device requires on an ongoing basis. Growth is supported by the rising global prevalence of chronic obstructive pulmonary disease, asthma, and obstructive sleep apnea, driven by factors including smoking, an ageing population, and worsening air pollution levels in many rapidly industrialising regions.
On December 8, 2025, ResMed received FDA clearance for Smart Comfort, marketed as the first FDA-cleared AI-enabled medical device that recommends personalised comfort settings to help people with obstructive sleep apnea start and stay on CPAP therapy, drawing on more than 100 million nights of de-identified, real-world sleep data to tailor settings for individual patients using the company's AirSense 11 platform.
To Get More Information On Respiratory Care Devices Market - Request Free Sample Report
Respiratory Care Devices Market Trends:
-
Rising integration of artificial intelligence and machine learning to personalise CPAP and ventilator therapy settings.
-
Growing adoption of cloud-connected devices enabling remote patient monitoring and therapy adherence tracking.
-
Expanding home-based respiratory therapy reducing reliance on costly, resource-intensive hospital-based care.
-
Increasing merger and acquisition activity as larger device makers expand into adjacent sleep health categories.
-
Rising demand for portable, travel-friendly oxygen and CPAP devices supporting active patient lifestyles.
-
Growing regulatory emphasis on device safety and post-market surveillance following high-profile industry recalls.
U.S. Respiratory Care Devices Market Overview:
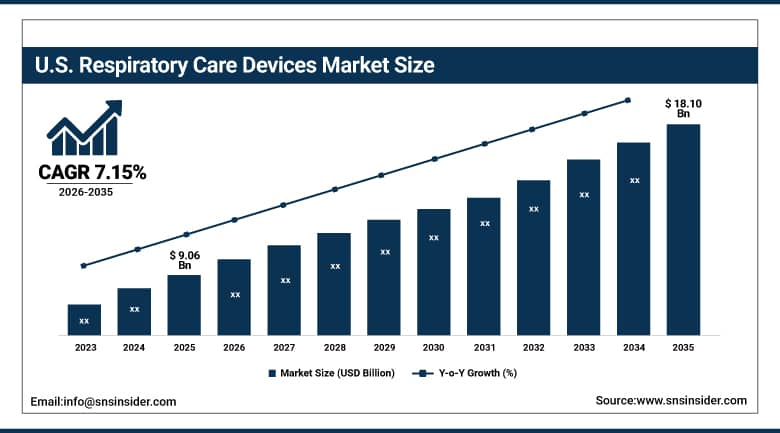
The U.S. Respiratory Care Devices Market was valued at USD 9.06 Billion in 2025 and is expected to reach USD 18.10 Billion by 2035, growing at a CAGR of 7.15% from 2026-2035.
The U.S. Respiratory Care Devices Market benefits from a large and ageing population, broad insurance and Medicare coverage for both hospital-based and home respiratory therapy, and the presence of leading device manufacturers headquartered in the country that continue to compete intensely on digital health capability and therapy personalisation. Widespread awareness of sleep apnea, reinforced by decades of direct-to-consumer marketing and physician referral pathways built around continuous positive airway pressure therapy, continues to sustain one of the largest and most mature CPAP markets anywhere in the world. Healthcare infrastructure investment continues to expand hospital ventilator and monitoring capacity, while a well-established home medical equipment distribution network continues to support the millions of patients managing chronic obstructive pulmonary disease, asthma, and sleep apnea from home rather than through repeated clinical visits.
In April 2025, Dragerwerk AG & Co. KGaA secured U.S. FDA 510(k) clearance for its VentStar Resus heated and VentStar Autobreath heated emergency ventilators, demonstrating substantial equivalence to other legally marketed devices and permitting the company to sell these Class II powered emergency ventilators across the United States for use in acute and emergency respiratory support settings.
Respiratory Care Devices Market Segment Analysis:
-
By Product Type, the Therapeutic Devices segment dominated the market with a 52.35% share in 2025, while the Diagnostic and Monitoring Devices segment is the fastest growing with a CAGR of 9.15% during 2026-2035.
-
By Therapeutic Device Type, the PAP Devices segment dominated the market with a 33.85% share in 2025, while the Ventilators segment is the fastest growing with a CAGR of 8.95% during 2026-2035.
-
By Disease Indication, the Chronic Obstructive Pulmonary Disease segment dominated the market with a 38.70% share in 2025, while the Sleep Apnea segment is the fastest growing with a CAGR of 9.35% during 2026-2035.
-
By End User, the Hospitals segment dominated the market with a 44.15% share in 2025, while the Home Care Settings segment is the fastest growing with a CAGR of 9.55% during 2026-2035.
By End User, Hospitals Dominates the Market and Home Care Settings Grows Fastest
Hospitals dominated the market in 2025 with a 44.15% share. Acute respiratory failure, critical care ventilation, and complex diagnostic sleep and pulmonary function testing all continue to require the infrastructure, specialist staffing, and monitoring capability that only hospital settings reliably provide, and this fundamental role in managing the most clinically severe respiratory cases continues to anchor hospitals as the largest end-user category across the broader respiratory care devices market by a considerable margin over every alternative care setting.
Home care settings are projected to be the fastest-growing end-user category over the forecast period, registering a CAGR of 9.55%, as the therapeutic equipment market has expanded multi-fold in recent years due to the need for long-term home respiratory therapy, driven directly by the global burden of chronic disease and by payer and patient preference alike for managing stable chronic conditions outside costly hospital settings wherever clinically appropriate to do so. Continued advancement in portable, cloud-connected devices designed specifically for home use, paired with expanding remote monitoring capability that gives clinicians confidence to manage patients from a distance, continues to accelerate this shift and drive sustained above-market growth for the home care end-user category.
By Product Type, Therapeutic Devices Dominates the Market and Diagnostic and Monitoring Devices Grows Fastest
Therapeutic devices dominated the market in 2025 with a 52.35% share, and this category, spanning CPAP and BiPAP machines, mechanical ventilators, humidifiers, oxygen concentrators, and nebulizers, continues to represent the largest and most clinically consequential segment of the broader respiratory care devices market. Long-term home respiratory therapy has expanded multi-fold in recent years, driven by the global burden of chronic obstructive pulmonary disease and sleep apnea, and by a consistent preference among both patients and payers for managing chronic respiratory conditions outside the hospital wherever that is clinically appropriate. Because therapeutic devices must be replaced periodically and require an ongoing stream of consumable accessories throughout their service life, this category continues to generate recurring revenue well beyond the initial equipment purchase, reinforcing its position as the clear anchor of the broader market even as diagnostic technology continues to advance rapidly around it.
Diagnostic and monitoring devices are projected to be the fastest-growing product category over the forecast period, registering a CAGR of 9.15%, as expanding home sleep testing capability and rising demand for continuous physiological monitoring continue to widen this category's addressable market well beyond its traditional role inside hospital sleep laboratories. Growing patient willingness to undergo diagnostic testing from the comfort of home, combined with cloud-connected monitoring platforms that let clinicians track therapy effectiveness remotely between in-person visits, continues to accelerate adoption of this category ahead of the broader therapeutic-device-dominated market. Rising integration of pulse oximetry, capnography, and other continuous monitoring modalities into connected care platforms is further expanding the clinical use cases these devices can address.
By Therapeutic Device Type, PAP Devices Dominates the Market and Ventilators Grows Fastest
PAP devices dominated the therapeutic device category in 2025, reflecting the enormous and still substantially underdiagnosed population of patients living with obstructive sleep apnea worldwide. Continuous and automatic positive airway pressure machines remain the established first-line treatment for this condition, and decades of clinical evidence, physician familiarity, and steadily improving comfort technology continue to make PAP therapy the default recommendation across the overwhelming majority of diagnosed cases. The rise of cloud-connected PAP platforms, capable of tracking nightly usage and automatically adjusting pressure settings based on real-world therapy data, continues to reinforce this product type's dominant position by meaningfully improving the patient adherence rates that have historically limited the long-term effectiveness of sleep apnea therapy.
Ventilators are projected to be the fastest-growing therapeutic device type over the forecast period, registering a CAGR of 8.95%, as continued investment in critical care capacity, expanding home mechanical ventilation for patients with chronic respiratory failure, and rising emergency and transport ventilation demand continue to drive above-market growth for this category. Hospitals and emergency medical services worldwide continue to invest in modern, more portable ventilator platforms following heightened attention to respiratory critical care capacity in recent years, and this sustained capital investment cycle continues to support ventilators' accelerating growth relative to the broader PAP-dominated therapeutic device mix.
By Disease Indication, Chronic Obstructive Pulmonary Disease Dominates the Market and Sleep Apnea Grows Fastest
Chronic obstructive pulmonary disease dominated the market in 2025 with a 38.70% share. This progressive, largely irreversible lung condition continues to affect an enormous global patient population, particularly among current and former smokers and populations exposed to significant air pollution, and its chronic, lifelong nature means patients typically require sustained device-based management, including oxygen therapy and ventilatory support, over many years rather than a single course of acute treatment. The scale and persistence of the global COPD patient population, combined with the multiple device categories this single disease indication draws upon, continues to anchor COPD as the clear leading disease indication across the broader respiratory care devices market.
Sleep apnea is projected to be the fastest-growing disease indication over the forecast period, registering a CAGR of 9.35%, as rising obesity rates worldwide continue to expand the population at risk for obstructive sleep apnea, while growing public and physician awareness continues to close the substantial diagnosis gap that has historically left a large share of sleep apnea cases entirely untreated. Expanding home sleep testing accessibility continues to accelerate diagnosis rates, and this improving diagnostic pathway, combined with steadily improving CPAP comfort technology that reduces early therapy discontinuation, continues to sustain above-market growth for this disease indication relative to the broader COPD-dominated indication mix.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
90.15% |
|
Europe |
Germany |
28.75% |
|
Asia Pacific |
China |
36.60% |
|
Latin America |
Brazil |
24.35% |
|
Middle East & Africa |
United Arab Emirates |
21.70% |
North America Respiratory Care Devices Market Insights
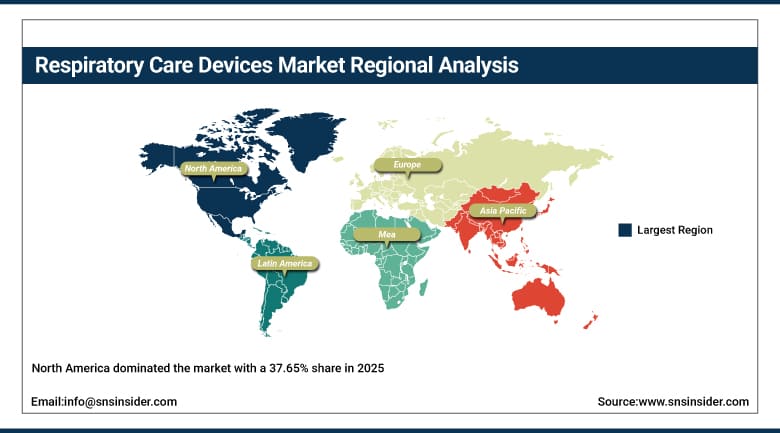
North America dominated the market with a 37.65% share in 2025, anchored overwhelmingly by the United States, which alone represents a substantial majority of overall regional revenue. Robust healthcare systems, deep public awareness of respiratory health, particularly sleep apnea following decades of direct consumer education, and broad insurance coverage extending across both hospital-based acute care and home-based chronic disease management continue to sustain the region's clear leadership position. The concentration of the world's largest respiratory device manufacturers within the region, several of which are headquartered in the United States, further reinforces sustained investment in next-generation digital health and AI-enabled therapy technology that continues to originate first within this market before expanding internationally.
Canada contributes meaningful incremental regional demand through its own publicly funded healthcare system, which continues to extend coverage for both diagnostic sleep testing and home respiratory therapy equipment. Continued expansion of cloud-connected device adoption, combined with sustained hospital capital investment in modern ventilation and monitoring equipment, is expected to keep North America in the lead through the forecast period, even though its growth rate is projected to trail the faster-scaling markets developing across Asia Pacific over the coming decade.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Respiratory Care Devices Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 8.0%. A large and still substantially underdiagnosed patient population, combined with expanding medical device manufacturing capabilities across several major regional economies, continues to make this region genuinely attractive to both global and local respiratory care device manufacturers seeking to establish or expand their regional commercial presence. Rapidly rising air pollution levels in several major regional economies, combined with high and in some cases increasing smoking prevalence, continue to expand the underlying disease burden that ultimately drives device demand across the region.
China anchors regional demand through its enormous population base and rapidly expanding domestic medical device manufacturing industry, which continues to lower device costs and improve accessibility for a broader share of the population than was previously feasible. Japan contributes substantial mature demand given its advanced medical technology infrastructure and exceptionally high proportion of elderly residents, while India and Southeast Asian markets add rapid incremental growth as healthcare infrastructure investment and rising middle-class disposable income continue to widen access to modern respiratory diagnostic and therapeutic equipment across previously underserved populations.
Europe Respiratory Care Devices Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial hospital sector and its position as home to several of the world's leading respiratory device manufacturers with deep clinical research and engineering capability spanning decades. The region's well-developed public health systems and strong clinical guideline development tradition continue to sustain steady demand across every major respiratory device category, from hospital ventilation through home-based sleep apnea therapy and chronic obstructive pulmonary disease management.
The United Kingdom, France, and Italy add consistent regional demand as national health systems continue extending coverage for both diagnostic and therapeutic respiratory devices to a broader share of their eligible patient populations. Advanced medical technology adoption within select Western European markets, combined with continued clinical guideline development across major European respiratory and sleep medicine societies, is expected to sustain steady growth across the broader European market through the forecast period, even as overall growth trails the faster-expanding markets of Asia Pacific.
MEA and Latin America Respiratory Care Devices Market Insights
The Middle East and Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding hospital and specialist respiratory care capacity as part of broader healthcare modernisation strategies targeting rising rates of chronic respiratory and metabolic disease across increasingly urbanised regional populations.
Latin America is anchored by Brazil, where a growing domestic healthcare sector and expanding private insurance coverage continue to sustain steady demand for respiratory care devices across both hospital and home care settings. Mexico contributes further incremental growth as regional access to specialist pulmonology and sleep medicine care continues to widen gradually, supported by continued investment in both public and private healthcare infrastructure across the broader region.
Market Dynamics:
Growth Drivers: Chronic Disease Prevalence and Digital Health Innovation
The increasing global prevalence of respiratory diseases stands as the primary growth driver, as chronic obstructive pulmonary disease, asthma, and sleep apnea continue to affect an enormous and still growing share of the world's population, driven by factors including smoking, an ageing population, and rising air pollution levels across many rapidly industrialising economies. Because these conditions are chronic rather than acute, patients typically require ongoing, often lifelong device-based management, which continues to generate recurring equipment replacement and consumable accessory demand that compounds steadily year after year across an expanding global patient base.
Continued digital health and artificial intelligence innovation represents a second major driver, as cloud-connected devices increasingly capture real-world usage data that clinicians can use to personalise therapy, identify non-adherent patients early, and intervene before treatment failure occurs. Rising patient and physician confidence in remote monitoring technology continues to support the broader shift toward home-based respiratory therapy, and continued advancement in AI-enabled comfort personalisation is beginning to meaningfully improve the historically stubborn adherence rates that have long limited the real-world effectiveness of therapies such as CPAP.
Restraints: Device Recalls and Reimbursement Complexity
High-profile device safety recalls remain a genuine restraint across this market, as prior industry-wide recalls affecting widely used CPAP and ventilator platforms continue to weigh on patient trust and have prompted meaningfully increased regulatory scrutiny and post-market surveillance requirements across the entire respiratory device category, adding compliance cost and complexity for manufacturers seeking to bring new devices to market quickly.
Reimbursement complexity presents a further restraint, as coverage policies for home respiratory therapy equipment continue to vary considerably between countries, and in some cases between individual insurers within the same country, creating genuine uncertainty for both patients and prescribing physicians when deciding which device category and therapy pathway to pursue for a given clinical presentation, particularly for newer diagnostic and monitoring technology that has not yet accumulated the extensive reimbursement track record older device categories enjoy.
Opportunities: Home Therapy Expansion and AI-Enabled Personalisation
Continued expansion of home-based respiratory therapy represents a substantial opportunity, as manufacturers that can deliver genuinely reliable, easy-to-use devices suited to unsupervised home use stand to capture demand from an ageing, increasingly chronically ill population that both prefers and, in many health systems, is increasingly steered toward managing stable respiratory conditions outside costly hospital settings wherever clinically appropriate to do so.
Continued development of AI-enabled therapy personalisation offers a further avenue for growth, as manufacturers that can demonstrate genuinely improved patient adherence and clinical outcomes through machine learning-driven comfort and settings optimisation are positioned to capture premium demand from both patients and health systems increasingly focused on measurable therapy effectiveness rather than simple device availability alone, a shift that continues to reward manufacturers investing most heavily in real-world evidence generation.
Recent Developments:
-
2026, ResMed launched AirConnect Dx in the UK, a digital respiratory-care solution designed to streamline obstructive sleep apnea diagnosis through integrated referral, home sleep testing, reporting, logistics, and patient-support workflows.
-
2026, Fisher & Paykel Healthcare launched the F&P Nova Nasal mask in the U.S., adding a new nasal positive airway pressure interface for obstructive sleep apnea treatment. The mask incorporates SwingFit headgear and a RollFit cushion designed to improve fitting, sealing, and patient comfort.
-
2026, Philips expanded its patient-monitoring ecosystem through collaborations with Respiree, LifeSignals, smartQare, Cuviva and other technology companies, adding wearable and out-of-hospital monitoring capabilities for continuous respiratory and physiological monitoring from hospital through home care.
-
2026, ResMed completed the acquisition of Noctrix Health, adding wearable neuromodulation technology for restless legs syndrome to its sleep and breathing health portfolio. The transaction expands ResMed’s device portfolio into an adjacent non-pharmacological therapy category.
-
2026, Philips highlighted its collaboration with Respiree, integrating Respiree’s wearable biosensor and AI-enabled respiratory monitoring capabilities with Philips’ monitoring ecosystem. The technology supports continuous monitoring of respiratory rate, SpO₂ and other physiological parameters across hospital and home-care settings.
Respiratory Care Devices Market Key Players:
-
Koninklijke Philips N.V.
-
Medtronic plc
-
ResMed Inc.
-
GE HealthCare Technologies Inc.
-
Dragerwerk AG & Co. KGaA
-
Fisher & Paykel Healthcare Corporation Limited
-
Becton, Dickinson and Company
-
Masimo Corporation
-
Vyaire Medical, Inc.
-
ICU Medical, Inc.
-
Hamilton Medical AG
-
Invacare Corporation
-
Teleflex Incorporated
-
Getinge AB
-
Nihon Kohden Corporation
-
Compumedics Limited
-
Chart Industries, Inc.
-
Inogen, Inc.
-
Breas Medical AB
-
Vapotherm, Inc.
Respiratory Care Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 24.55 Billion |
| Market Size by 2035 | USD 53.79 Billion |
| CAGR | CAGR of 8.16% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Therapeutic Devices, Diagnostic and Monitoring Devices, and Consumables and Accessories) • by Therapeutic Device Type (PAP Devices, Ventilators, Humidifiers, Oxygen Concentrators, and Nebulizers) • by Disease Indication (Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Infectious Disease, and Other Respiratory Disorders) • by End User (Hospitals, Home Care Settings, and Ambulatory Surgical Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Koninklijke Philips N.V., Medtronic plc, ResMed Inc., GE HealthCare Technologies Inc., Dragerwerk AG & Co. KGaA, Fisher & Paykel Healthcare Corporation Limited, Becton, Dickinson and Company, Masimo Corporation, Vyaire Medical, Inc., ICU Medical, Inc., Hamilton Medical AG, Invacare Corporation, Teleflex Incorporated, Getinge AB, Nihon Kohden Corporation, Compumedics Limited, Chart Industries, Inc., Inogen, Inc., Breas Medical AB, Vapotherm, Inc. |

Frequently Asked Questions
Key players include Koninklijke Philips N.V., Medtronic plc, ResMed Inc., GE HealthCare Technologies Inc., and Dragerwerk AG & Co. KGaA, among other medical device manufacturers.
Continued expansion of home-based respiratory therapy and continued development of AI-enabled therapy personalisation represent the primary opportunities.
Growth is primarily driven by the increasing global prevalence of respiratory diseases, combined with continued digital health and artificial intelligence innovation.
By Product Type, Therapeutic Devices dominated the market with a 52.35% share in 2025, reflecting sustained demand for CPAP machines, ventilators, and oxygen concentrators.
North America dominated the market with a 37.65% share in 2025, supported by robust healthcare systems and deep public awareness of respiratory health.
