
Satellite Communication (SATCOM) Equipment Market Report Scope & Overview:
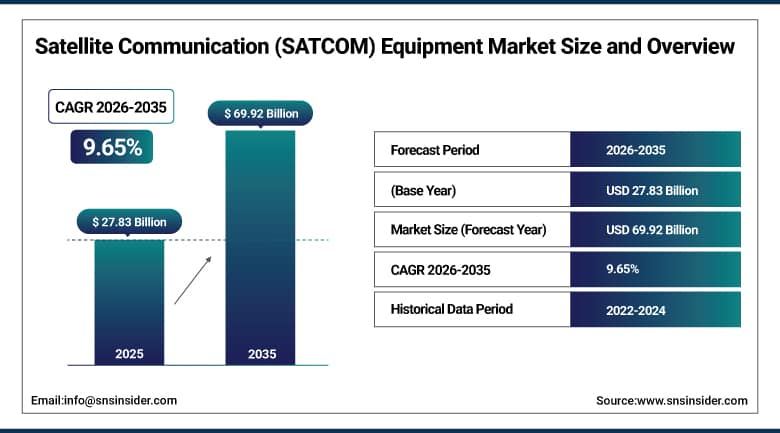
The Satellite Communication (SATCOM) Equipment Market was valued at USD 27.83 Billion in 2025 and is expected to reach USD 69.92 Billion by 2035, growing at a CAGR of 9.65% from 2026-2035.
The primary drivers for the growth in the Satellite Communication (SATCOM) Equipment Market are the rapid deployment of low earth orbit satellite constellations, resulting in continuous demand for ground antennas, modems, and user terminals that can facilitate high throughput and low latency connectivity services for commercial, government, and defense sector applications. Military and defense sector demand for satellite communication services and broadband services in rural and remote locations is driving the addressable market for SATCOM equipment that is available both in fixed and mobile forms. The deployment of high capacity geostationary satellites and the combination of satellite connectivity services with 5G wireless networks are increasing the range of applications of satellite-based communication network infrastructure in the commercial sector.
In June 2024, Gilat Satellite Networks signed a definitive agreement to acquire Stellar Blu Solutions, a U.S.-based avionics solutions provider specializing in next-generation SATCOM terminal solutions for the in-flight connectivity market. Stellar Blu's Sidewinder terminal, an open-architecture electronically steered antenna solution optimized for multi-orbit connectivity, has already been selected by major satellite operators including Intelsat, Panasonic, and OneWeb, illustrating how leading SATCOM equipment providers are expanding their portfolios to capture growing demand across commercial aviation and other high-end mobility markets.
To Get More Information Of This Market - Request Free Sample Report
Satellite Communication (SATCOM) Equipment Market Trends:
-
Rapid growth of low Earth orbit satellite constellations increasing demand for ground and user terminal equipment.
-
Growing adoption of electronically steered antennas supporting multi-orbit, in-motion connectivity applications.
-
Increasing integration of satellite connectivity with terrestrial 5G networks for hybrid communication solutions.
-
Rising demand for high-throughput Ka-band equipment supporting bandwidth-intensive commercial applications.
-
Continued miniaturization of SATCOM terminals expanding addressable applications across mobile platforms.
U.S. Satellite Communication (SATCOM) Equipment Market Outlook:
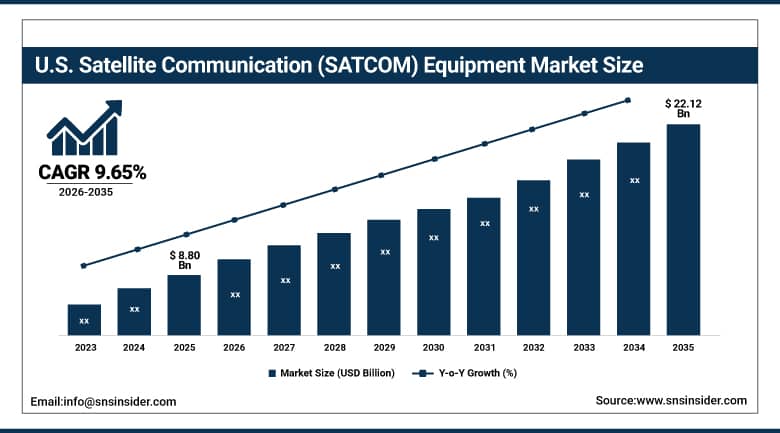
The U.S. Satellite Communication (SATCOM) Equipment Market was valued at USD 8.80 Billion in 2025 and is expected to reach USD 22.12 Billion by 2035, growing at a CAGR of 9.65% from 2026-2035.
U.S. Satellite Communication (SATCOM) Equipment Market Growth is consistently aided by significant investments made by the Department of Defense in reliable and jam-resistant satellite communications infrastructure, the expansion of the number of commercial low earth orbit satellites, and the prevalence of top SATCOM equipment makers and integrators in the country. Domestic demand will further benefit from the ongoing commitment of the government to proliferated satellite systems that provide improved resiliency against new space threats. The rising demand for commercial airline and maritime communications is aiding the demand for electronically steerable antenna terminals providing multi-orbit and multi-constellation connectivity capability.
In October 2025, Viasat was selected by the U.S. Space Force Space Systems Command for a prime contract award under the Protected Tactical SATCOM-Global program, one of five awardees to receive an initial delivery order under a large indefinite-delivery, indefinite-quantity contract. Under the award, Viasat will mature a design for a dual-band X/Ka-band satellite and anchor station architecture supporting a proliferated, small satellite geosynchronous constellation intended to deliver resilience and anti-jam capabilities for government end-users beginning with an initial constellation launch projected for 2028.
Satellite Communication (SATCOM) Equipment Market Segment Analysis:
-
By Component, the Antenna segment dominated the Satellite Communication (SATCOM) Equipment Market with approximately 34.50% share in 2025, while the Modem/Transceiver segment is the fastest growing with a CAGR of approximately 11.80%.
-
By Type, the SATCOM-on-the-Move segment dominated the Satellite Communication (SATCOM) Equipment Market with approximately 58.50% share in 2025, while the SATCOM-on-the-Pause segment is the fastest growing with a CAGR of approximately 10.20%.
-
By Frequency Band, the Ku-Band segment dominated the Satellite Communication (SATCOM) Equipment Market with approximately 31.50% share in 2025, while the Ka-Band segment is the fastest growing with a CAGR of approximately 12.60%.
-
By Vertical, the Government & Defense segment dominated the Satellite Communication (SATCOM) Equipment Market with approximately 62.50% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 11.40%.
By Component, Antenna dominates and Modem/Transceiver grows fastest
The Antennas component segment retains its position as the leading one in the SATCOM Equipment market due to the critical importance of antennas as the primary hardware providing an interface between ground and mobile terminals and orbiting satellites in all types of applications. This component segment sees further development of the technology of electronic steering of antennas, which substitutes parabolic antennas in applications involving airborne and mobile terminal devices due to their cumbersome nature and need for additional components required to perform the steering function. Stable demand for both fixed ground antennas and lightweight mobile terminal antennas supports the leading position of this component segment in the market.
Modems and transceivers are rapidly gaining the status of the fastest-growing component segments due to high dynamics of the development of high-throughput satellite constellations requiring increasingly more complex signal processing technology. The focus of this component segment is put on the development of software-defined modem solutions capable of changing the network and frequency band to provide reliable communication through different satellite constellations. The growth of low Earth orbit constellations together with geostationary satellite networks means that this component segment is set to gain more and more shares of the overall equipment investments.
By Type, SATCOM-on-the-Move dominates and SATCOM-on-the-Pause grows fastest
SATCOM-on-the-Move is still the leader among all the type segments of the Satellite Communication (SATCOM) Equipment Market, offering high speed, beyond-line-of-sight, satellite connectivity for mobile vehicles, vessels, and aircraft for applications in defense, transportation, and broadcasting. SATCOM-on-the-Move is expected to benefit from high military demand for connectivity solutions, which are continuously working while vehicles are moving. Besides, increasing use of SATCOM-on-the-Move in commercial applications is also expected to support this type segment, since continuous connectivity is more important for defense and commercial operators than stationary one, which is usually installed in fixed communication hubs.
SATCOM-on-the-Pause is expected to be the fastest-growing type segment of the Satellite Communication (SATCOM) Equipment Market. This type segment will be driven by increasing demand for quickly deployable and transportable satellite hubs that will be used in military expeditions and emergency responses. SATCOM-on-the-Pause involves the installation of ruggedized terminal systems that can establish high-capacity networks within hours after the installation process begins. Therefore, increasing number of military organizations valuing flexibility and mobility of communication systems rather than permanently established systems will drive SATCOM-on-the-Pause market.
By Frequency Band, Ku-Band dominates and Ka-Band grows fastest
The Ku-Band frequency segment remains the dominant category within the Satellite Communication (SATCOM) Equipment Market, reflecting its established role as the workhorse frequency band for broadcasting, VSAT networks, and mobile connectivity applications across commercial and government end markets. This segment benefits from decades of accumulated satellite fleet capacity and ground equipment standardization, supporting broad interoperability across multiple satellite operators and equipment manufacturers worldwide. Continued reliance on Ku-Band capacity for direct-to-home broadcasting and enterprise VSAT networks sustains this segment's leading position even as newer frequency bands continue to gain share in specific high-throughput applications.
The Ka-Band frequency segment is emerging as the fastest-growing category, driven by deployment of high-throughput satellites that leverage Ka-Band's wider available bandwidth to deliver significantly higher data speeds than legacy Ku-Band systems. This segment focuses on equipment supporting bandwidth-intensive applications including broadband internet, video streaming, and enterprise data connectivity, where the capacity advantages of Ka-Band spectrum directly translate into superior throughput performance. As satellite operators continue launching high-throughput Ka-Band constellations to meet growing consumer and enterprise broadband demand, this segment is positioned to capture a rapidly expanding share of overall equipment investment.
By Vertical, Government & Defense dominates and Commercial grows fastest
Government & Defense stands out as the key vertical player in the Satellite Communication (SATCOM) Equipment Market owing to persistent military investments in reliable, secure satellite communication network infrastructure for effective command, control, and intelligence functions around the world. The growth prospects for the Government & Defense vertical can be attributed to significant national defense budgets dedicated to investing in proliferated, jam-proof satellite communication architectures to ensure connectivity in hostile electromagnetic environments. The continued investment in advanced tactical protected satellite programs and expeditionary SATCOM equipment infrastructure further cement the dominance of the vertical within the equipment market.
The Commercial vertical is expected to be the fastest growing in terms of revenue generation owing to robust growth in commercial LEO broadband constellations, in-flight and maritime communications services, as well as increasing enterprise adoption of backup satellite communications systems. The Commercial vertical focuses on affordable and mass-manufacturable terminal equipment that can be used for broadband communications applications in consumers and enterprise segments. With ongoing growth in capacity of broadband constellations operated by commercial players, the Commercial vertical is likely to capture a rising share of total equipment spend in the coming years.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.50% |
|
Europe |
United Kingdom |
29.60% |
|
Asia Pacific |
China |
44.80% |
|
Latin America |
Brazil |
43.60% |
|
Middle East & Africa |
Israel |
41.20% |
North America Satellite Communication (SATCOM) Equipment Market Insights
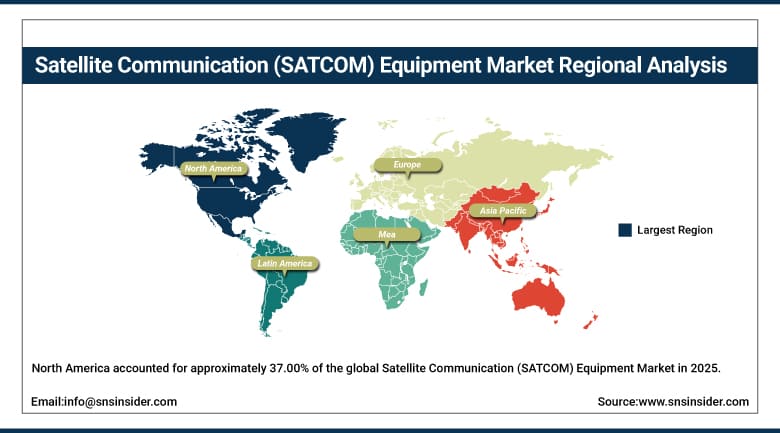
North America accounted for approximately 37.00% of the global Satellite Communication (SATCOM) Equipment Market in 2025, reflecting the region's substantial defense satellite communication spending and its concentration of leading SATCOM equipment manufacturers and system integrators. The United States accounts for the substantial majority of regional demand, driven by sustained Department of Defense investment in resilient satellite architectures and the presence of major commercial satellite operators, equipment manufacturers, and system integrators serving both government and commercial customers across the broader North American market.
Canada contributes additional regional demand through its participation in North American defense satellite communication programs and growing commercial connectivity initiatives serving remote northern communities. Continued U.S. government prioritization of proliferated satellite architectures, sustained commercial low Earth orbit constellation growth, and expanding in-flight and maritime connectivity services further reinforce North America's position as the largest regional market for SATCOM equipment, with defense procurement cycles expected to sustain elevated demand levels throughout the extended forecast period across both government and commercial end markets, as allied nations increasingly rely on North American-developed terminal technology for interoperable coalition communications.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Satellite Communication (SATCOM) Equipment Market Insights
Asia Pacific is set to grow with the highest CAGR of around 11.90% in the Satellite Communication (SATCOM) Equipment Market from 2026-2035, fueled by the increasing demand for satellite broadband services in rural areas and the expansion of domestic defense satellite communication programs. In Asia Pacific, China leads the growth of the market, backed by heavy government spending on indigenous satellite constellation systems and increasing production of SATCOM equipment in the country for both military and civilian applications.
India and Japan provide other contributors to growth in the region, where increasing broadband connectivity in rural areas and indigenous satellite production in India drive the growth in equipment demand, and the established electronics manufacturing sector in Japan drives the development of ground satellite equipment. Further regional government spending on indigenous satellite constellation projects and commercial connectivity needs in maritime and aviation segments reinforce Asia Pacific as the fastest-growing market globally for SATCOM equipment as governments in the region emphasize the need for satellite connectivity infrastructure for both military and civilian applications through increased domestic launch capabilities.
Europe Satellite Communication (SATCOM) Equipment Market Insights
There is a considerable regional market in Europe for SATCOM equipment with the United Kingdom representing the largest demand in the region due to its large defense satellite communications projects and the presence of companies that manufacture the majority of satellite equipment in the region. There is a combination of established defense procurement projects in the UK, along with the existence of major satellite communication equipment manufacturers in the country, which continue to invest in developing independent space capabilities, ensuring that the UK continues to be a regional leader in the design and manufacturing of satellite ground equipment.
There is an existing market in Germany and France due to the presence of aerospace and defense manufacturing industry in both countries, along with investments in developing indigenous satellite constellations in both countries. Continued EU investments in sovereign satellite communications capability, including joint multi-national defense satellite projects, will ensure continuous demand for SATCOM equipment in Europe as there is a push among the governments of the region to lessen dependence on non-EU satellite communication systems, through coordinated procurement of satellite ground equipment.
MEA & Latin America Satellite Communication (SATCOM) Equipment Market Insights
Latin America's Satellite Communication (SATCOM) Equipment Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large geographic territory requiring satellite-based connectivity across remote and underserved areas. Brazil's government and commercial sectors continue investing in satellite communication infrastructure to extend broadband connectivity across the Amazon region and other remote areas, while gradual expansion of regional defense modernization programs supports incremental growth in government and military SATCOM equipment procurement throughout the forecast period.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in markets such as Israel, which maintains a well-established defense satellite communication development ecosystem supporting both domestic military programs and export activity to allied nations worldwide. Gulf Cooperation Council markets contribute additional regional demand through growing defense procurement and expanding commercial satellite connectivity investment, as regional governments continue prioritizing resilient communication infrastructure across both military and civilian applications throughout the broader Middle East and African region, with several nations pursuing dedicated national satellite programs to reduce reliance on foreign-operated constellations.
Market Dynamics:
Growth Drivers: LEO Constellation Expansion and Defense Modernization Spending
The rapid proliferation of low earth orbit satellite constellations acts as the key factor driving growth in the Satellite Communication (SATCOM) Equipment Market as the demand for satellite ground antennas, modems, and terminals that can facilitate high-speed and low latency connections will continue to grow among more commercial and military applications. The same applies to the growing demand from defense organizations around the world for satellite communication solutions, since defense organizations continue to develop satellite constellations resistant to jamming and capable of maintaining the connection in the contested electromagnetic environment.
Rising demand for high bandwidth services in underdeveloped and underserved regions constitutes another major factor driving the demand in the market. Satellite connectivity acts as the only viable option for such regions in terms of extending internet access. Deployment of satellites with a high capacity and connecting satellites with the fifth-generation wireless network expands the number of commercially viable applications available through hybrid satellite-terrestrial architectures. The same applies to regions where there is no economic justification to expand fiber or cellular network due to the low population density.
Restraints: High Equipment Costs and Spectrum Allocation Complexity
The comparatively high cost of advanced SATCOM equipment, particularly electronically steered antenna terminals and multi-orbit capable modems, represents a significant restraint on the Satellite Communication (SATCOM) Equipment Market, as these premium capabilities continue to command substantial price premiums over legacy mechanically steered antenna systems. This dynamic limits broader commercial and consumer adoption in price-sensitive market segments, even as manufacturing scale gradually reduces unit costs for next-generation terminal equipment across both government and commercial applications worldwide, particularly in emerging markets where affordability remains the primary barrier to broader satellite broadband adoption.
Complex international spectrum allocation and coordination requirements restrict the pace of new satellite constellation and ground equipment deployment, as operators must navigate varying regulatory frameworks across different national jurisdictions before launching commercial services. Continued geopolitical tension affecting satellite technology export controls and cross-border equipment sales adds further uncertainty to long-term market planning, particularly for equipment manufacturers seeking to serve both domestic defense customers and international commercial markets simultaneously across an increasingly fragmented regulatory landscape, where diverging national security requirements complicate efforts to standardize equipment designs across multiple markets.
Opportunities: Multi-Orbit Connectivity and Commercial Broadband Expansion
Continued growth of multi-orbit satellite architectures presents a substantial growth opportunity for the Satellite Communication (SATCOM) Equipment Market, as operators and government agencies increasingly prioritize resilient connectivity solutions capable of seamlessly switching between low Earth orbit, medium Earth orbit, and geostationary satellite networks. Manufacturers that can demonstrate validated, cost-competitive multi-orbit terminal technology are well positioned to capture share as both defense and commercial customers pursue architectures that eliminate single points of failure inherent in single-orbit satellite dependency across critical communication applications.
Rapid expansion of commercial broadband satellite constellations presents a longer-term opportunity for equipment manufacturers to extend their technology into consumer and enterprise connectivity markets beyond traditional government and defense applications. As commercial satellite operators continue scaling constellation capacity and reducing service costs, manufacturers with established mass-production capabilities for cost-competitive terminal equipment are positioned to capture a disproportionate share of this emerging demand across residential, enterprise, and mobility connectivity applications worldwide, particularly as satellite broadband increasingly competes directly with terrestrial fixed wireless and fiber offerings in price-sensitive markets.
Recent Developments:
-
In July 2024, L3Harris was awarded a USD 120 million indefinite-delivery, indefinite-quantity contract by the U.S. Army to develop a new 12.2-meter SATCOM terminal, expanding the existing Modernization of Enterprise Terminals network with six additional terminals scheduled for completion by 2032.
-
In September 2025, Gilat DataPath received orders totaling more than USD 7 million from the U.S. Department of Defense and U.S. Army to supply additional Transportable SATCOM Terminals, including multiple units of its DKET 3421 platform supporting rapid-deployment defense communications.
-
In August 2025, Gilat Defense was awarded a multimillion-dollar contract by Israel's Ministry of Defense for the delivery and integration of advanced satellite communication systems tailored to the operational requirements of Israel's defense forces.
Satellite Communication (SATCOM) Equipment Market Key Players:
-
Viasat, Inc.
-
EchoStar Corporation
-
Telesat Corporation
-
L3Harris Technologies, Inc.
-
General Dynamics Corporation
-
Airbus SE
-
Thales Group
-
Iridium Communications Inc.
-
Gilat Satellite Networks Ltd.
-
Cobham Satcom
-
Kratos Defense & Security Solutions, Inc.
-
ST Engineering iDirect
-
Comtech Telecommunications Corp.
-
Honeywell International Inc.
-
Collins Aerospace
-
SES S.A.
-
Intelsat S.A.
-
Inmarsat plc
-
ORBCOMM Inc.
-
ND SatCom GmbH
Satellite Communication (SATCOM) Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 27.83 Billion |
| Market Size by 2035 | USD 69.92 Billion |
| CAGR | CAGR of 9.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Component (Antenna, Modem/Transceiver, Terminal, and Others) • by Type (SATCOM-on-the-Move and SATCOM-on-the-Pause) • by Frequency Band (C-Band, Ku-Band, Ka-Band, X-Band, and L&S-Band) • by Vertical (Government & Defense and Commercial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Viasat, Inc., EchoStar Corporation, Telesat Corporation, L3Harris Technologies, Inc., General Dynamics Corporation, Airbus SE, Thales Group, Iridium Communications Inc., Gilat Satellite Networks Ltd., Cobham Satcom, Kratos Defense & Security Solutions, Inc., ST Engineering iDirect, Comtech Telecommunications Corp., Honeywell International Inc., Collins Aerospace, SES S.A., Intelsat S.A., Inmarsat plc, ORBCOMM Inc., ND SatCom GmbH |

Frequently Asked Questions
Leading companies in the Satellite Communication (SATCOM) Equipment Market include Viasat, EchoStar Corporation, Telesat, L3Harris Technologies, and General Dynamics, among others.
Key opportunities include continued growth of multi-orbit satellite architectures enabling resilient connectivity across LEO, MEO, and GEO networks, and rapid expansion of commercial broadband satellite constellations extending equipment demand into consumer and enterprise markets.
Rapid expansion of low Earth orbit satellite constellations, combined with growing military and defense satellite communication requirements, is the major factor driving market growth.
The Government & Defense segment dominated the Satellite Communication (SATCOM) Equipment Market with approximately 62.50% share in 2025.
North America dominated the Satellite Communication (SATCOM) Equipment Market in 2025 with approximately 37.00% share, reflecting the region's substantial defense satellite communication spending, led by the United States.
