
Satellite Navigation System Market Report Scope & Overview:
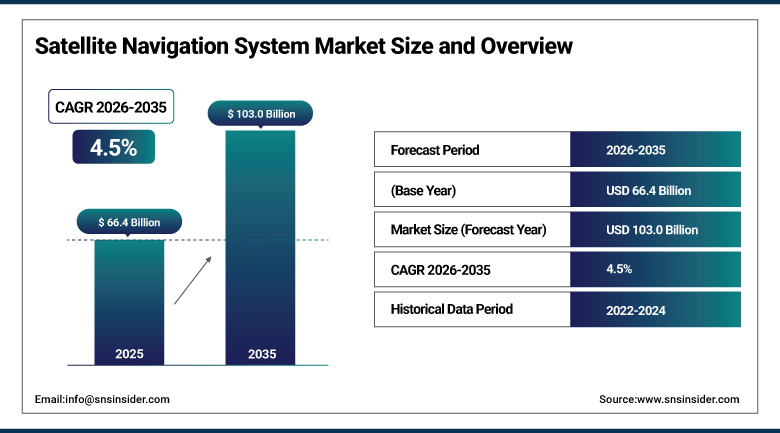
The Satellite Navigation System Market was valued at USD 66.4 Billion in 2025 and is expected to reach USD 103.0 Billion by 2035, growing at a CAGR of 4.5% from 2026–2035.
The factors propelling the Satellite Navigation System Market include the growing implementation of GNSS positioning and navigation technology in different industries such as automobile, aviation, marine, agriculture, surveying, logistics, and defense. The increasing requirements for the use of connected cars and autonomous cars are propelling the adoption of innovative navigation technologies. The development of location-based services, smartphone, and IoT devices is also driving the market. Furthermore, the growing investments in satellite constellation, regional navigation system, and augmentation system based on satellites are adding to the development of the market.
In February 2025, STMicroelectronics introduced its Teseo VI family of GNSS receivers, integrating multi-constellation, quad-band signal processing and a dual-Arm Cortex-M7 safety core onto a single chip for automotive and industrial positioning applications. The launch reflects a broader industry shift: modern receivers increasingly need to track GPS, Galileo, GLONASS, and BeiDou signals simultaneously rather than locking onto a single constellation, since redundancy across systems has become the baseline expectation for anything safety-critical.
To Get more information Satellite Navigation System Market - Request Free Sample Report
Satellite Navigation System Market Trends
-
Multi-constellation, dual-frequency receivers are becoming the industry standard as manufacturers build devices that can draw on GPS, Galileo, GLONASS, and BeiDou signals simultaneously rather than depending on any single system.
-
Autonomous vehicle and advanced driver-assistance system development continues driving demand for centimeter-level positioning accuracy that standard consumer-grade GNSS receivers alone can't reliably provide.
-
Low Earth Orbit satellite constellations are emerging as a genuine complement to traditional Medium Earth Orbit GNSS systems, offering stronger signal strength and better performance in urban canyons and other GPS-challenged environments.
-
Precision agriculture continues expanding GNSS adoption among farmers seeking to cut input costs and improve yield through centimeter-accurate guidance for planting, spraying, and harvesting equipment.
-
GNSS-based timing synchronization is becoming increasingly critical infrastructure for telecom networks, financial trading systems, and power grids, all of which depend on precisely synchronized clocks to function correctly.
U.S. Satellite Navigation System Market Outlook
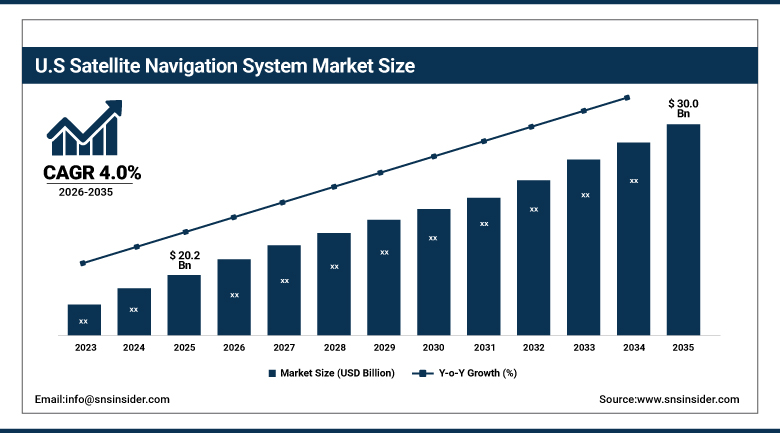
The U.S. Satellite Navigation System Market was valued at approximately USD 20.2 Billion in 2025 and is expected to reach approximately USD 30.0 Billion by 2035, growing at a CAGR of approximately 4.0%.
The United States remains the birthplace and continued anchor of global GNSS technology, home to the GPS constellation itself along with a deep base of receiver manufacturers, chipset designers, and downstream application developers. Transportation, logistics, and fleet management applications account for a substantial share of domestic demand, while precision agriculture continues expanding steadily across the country's farm belt. A concentration of leading GNSS technology providers gives the region continued innovation leadership even as other constellations expand their global reach.
The U.S. Space Force's next-generation GPS ground control system, OCX, was expected to reach operational acceptance in 2025 after years of delay, finally unlocking the full military-grade M-Code signal capability that GPS Block III satellites have carried since launch but couldn't yet fully broadcast. The years-long gap between launching modernized satellites and having the ground infrastructure ready to use them fully illustrates how much of GNSS modernization cost and complexity sits on the ground rather than in orbit.
Satellite Navigation System Market Segment Analysis
-
By Orbit Type, the Medium Earth Orbit segment dominated the Satellite Navigation System Market with approximately 68.0% share in 2025, while the Low Earth Orbit & Other Orbits segment is the fastest growing with a CAGR of approximately 7.89%.
-
By Solution, the Services segment dominated the Satellite Navigation System Market with approximately 58.0% share in 2025, while the System & Devices segment is the fastest growing with a CAGR of approximately 8.23%.
-
By Constellation Type, the Global Constellations segment dominated the Satellite Navigation System Market with approximately 71.0% share in 2025, while the Regional Navigation Satellite Systems segment is the fastest growing with a CAGR of approximately 8.8%.
-
By Application, the Road & Automotive segment dominated the Satellite Navigation System Market with approximately 34.0% share in 2025, while the Timing Synchronization segment is the fastest growing with a CAGR of approximately 7.4%.
-
By Enterprise Size, the Large Enterprises segment dominated the Satellite Navigation System Market with approximately 64.0% share in 2025, while the Small & Medium Enterprises segment is the fastest growing with a CAGR of approximately 8.8%.
By Orbit Type, Medium Earth Orbit dominates, Low Earth Orbit & other orbits grow fastest
Medium Earth Orbit held the overwhelming majority of the orbit-type segment in 2025, since nearly every major global constellation, GPS, Galileo, GLONASS, and BeiDou's core satellites, operates from this altitude band to balance signal coverage against orbital stability. That established architecture, refined over decades, keeps MEO the backbone of global satellite navigation.
Low Earth Orbit and other orbital approaches are growing fastest as new entrants explore LEO-based positioning, navigation, and timing systems that offer stronger ground-level signal strength than distant MEO satellites can provide. That signal strength advantage is particularly valuable in urban canyons and other GPS-challenged environments where traditional GNSS signals struggle to penetrate reliably.
By Solution, services dominates, system & devices grows fastest
Services held the largest share of the solution segment in 2025, spanning positioning, mapping, and location-based service subscriptions that generate recurring revenue well beyond the initial hardware purchase. That recurring revenue model has made the services layer increasingly central to how GNSS technology providers build sustainable, long-term business relationships with customers.
System and device sales are growing fastest as demand for multi-constellation receivers, chipsets, and specialized positioning hardware expands across automotive, industrial, and consumer electronics applications. Rising integration of GNSS receivers into an ever-broader range of connected devices continues pulling hardware demand upward faster than the underlying services layer.
By Constellation Type, global constellations dominates, regional systems grow fastest
Global constellations accounted for the large majority of constellation-type share in 2025, led overwhelmingly by GPS given its decades-long head start and deep integration into consumer devices, vehicles, and industrial systems worldwide. Galileo and BeiDou have both closed much of that historical gap in recent years, but GPS's installed base advantage remains substantial.
Regional navigation satellite systems are growing fastest as countries including Japan, India, and South Korea continue investing in constellations tailored to their own geographic coverage needs rather than relying entirely on global systems. These regional systems often provide superior local accuracy and reduce strategic dependency on foreign-controlled global constellations, both compelling reasons for continued national investment.
By Application, road & automotive dominates, timing synchronization grows fastest
Road and automotive applications accounted for the largest application share in 2025, spanning everything from basic in-vehicle navigation to the centimeter-accurate positioning that advanced driver-assistance and autonomous vehicle systems require. The sheer scale of the global vehicle fleet keeps this the largest single application category by a wide margin.
Timing synchronization is the fastest-growing application as telecom networks, financial trading systems, and power grids increasingly depend on GNSS-derived precise timing to keep distributed systems synchronized. The rollout of 5G networks in particular requires exceptionally precise timing coordination across base stations, giving this application a growth driver largely independent of traditional positioning and navigation use cases.
By Enterprise Size, large enterprises dominates, SMEs grows fastest
Large enterprises accounted for the largest share of the enterprise-size segment in 2025, given their scale of deployment across fleet management, logistics, surveying, and industrial applications that require substantial GNSS infrastructure investment. Their purchasing volume also gives large enterprises meaningfully better negotiating leverage with technology providers than smaller organizations typically secure.
Small and medium enterprises are the fastest-growing enterprise-size segment as declining GNSS chipset and module costs make sophisticated positioning technology accessible to smaller businesses that previously couldn't justify the investment. That falling cost curve is opening precision agriculture, small-scale surveying, and local logistics applications to a much broader population of smaller operators.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
82.0% |
|
Europe |
Germany |
24.0% |
|
Asia Pacific |
China |
42.0% |
|
Latin America |
Brazil |
38.0% |
|
Middle East & Africa |
UAE |
30.0% |
North America Satellite Navigation System Market Insights
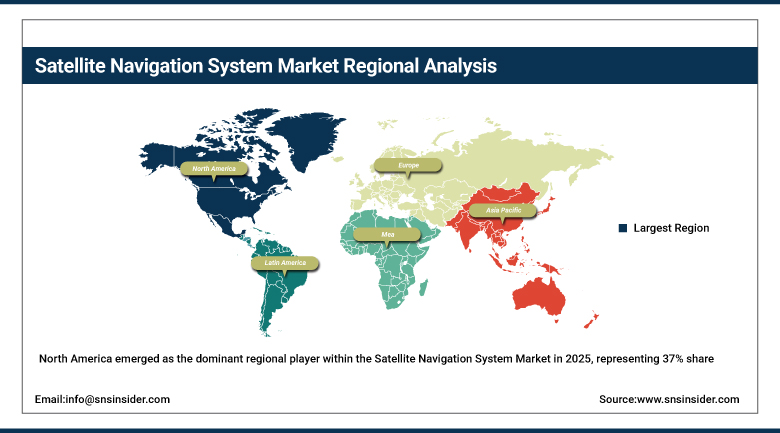
North America emerged as the dominant regional player within the Satellite Navigation System Market in 2025, representing 37% share in the global satellite navigation system market, driven by the country’s status as home to the GPS satellites as well as a range of prominent receivers manufacturers and applications providers. This amalgamation of satellite network, GNSS technology, defense strength, and usage across the automotive, aerospace, logistics, and LBS sectors ensures North America stays ahead in terms of GNSS advancements.
Canada contributes a meaningful share through its own transportation, agriculture, and surveying sectors, while Mexico's market continues expanding alongside growing automotive and logistics applications. Cross-border technology and supply relationships tie much of North American demand together, with major GNSS providers typically serving all three markets through shared product platforms.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Satellite Navigation System Market Insights
Asia Pacific will record the highest rate of growth among all regions till 2035, attributed mainly to China’s BeiDou system that offers global and improved regional coverage. There will be fast growth in the use of GNSS systems in automotive, agriculture, logistics, and industrial applications in China and other parts of Asia. The push from governments to adopt GNSS technology in smart infrastructure, intelligent transport, and precision agriculture is also expected to boost growth in the region.
India's expanding NavIC regional constellation and growing automotive and agriculture sectors are adding substantial demand, while Japan's QZSS system and South Korea's developing KPS program reflect the region's broader push toward positioning independence. Southeast Asian markets are following a similar adoption trajectory as regional transportation and logistics infrastructure continues to develop.
Europe Satellite Navigation System Market Insights
Europe represents a mature, technically sophisticated satellite navigation market, anchored by the EU's Galileo constellation, which has continued expanding its satellite count and improving global coverage precision since achieving initial operational capability. Germany anchors regional demand, home to major automotive and industrial GNSS application developers.
France and the United Kingdom contribute meaningful research and application development activity as well, with France hosting key Galileo ground infrastructure. EU-level investment in Galileo's continued modernization and expansion reflects the region's strategic commitment to positioning independence from GPS and other foreign-controlled systems.
MEA & Latin America Satellite Navigation System Market Insights
The Middle East and Africa host a smaller but strategically developing share of the satellite navigation market, with the UAE driving demand through smart-city infrastructure investment and growing transportation and logistics applications. Growth elsewhere in the region remains tied closely to broader transportation and agricultural infrastructure development.
Latin America is a growing market led by Brazil, where expanding precision agriculture and transportation logistics sectors continue driving GNSS adoption. Argentina and Mexico contribute meaningful secondary demand, tied to their own growing agricultural and automotive sectors.
Market Dynamics
Growth Drivers: Autonomous vehicle development and precision agriculture fueling adoption
Growing development of autonomous vehicles and advanced driver-assistance systems is one of the clearest forces behind rising satellite navigation demand, since these systems require centimeter-level positioning accuracy that standard consumer-grade GNSS receivers alone can't reliably deliver. That precision requirement is pulling substantial investment into augmented and multi-constellation positioning technology.
Expanding precision agriculture adoption adds a second major driver, as farmers increasingly rely on GNSS-guided equipment to cut input costs and improve yield across planting, spraying, and harvesting operations. Falling GNSS module costs continue making this technology accessible to a broader population of farming operations beyond the largest, most capital-intensive agricultural businesses.
Restraints: Signal vulnerability and infrastructure investment costs limiting broader adoption
GNSS signal vulnerability to jamming and spoofing remains a genuine concern, particularly for safety-critical applications like aviation and autonomous vehicles that depend on reliable positioning data to operate safely. That vulnerability is pushing developers toward multi-constellation redundancy and complementary positioning technologies, but addressing it fully requires real engineering investment.
The substantial infrastructure investment required to launch and maintain a satellite constellation adds a further restraint, limiting how many countries can realistically operate their own global or regional navigation system. That capital intensity keeps the global constellation market concentrated among a handful of major economic powers even as smaller nations pursue regional alternatives.
Opportunities: 5G timing synchronization and LEO-augmented positioning opening new growth avenues
Expanding 5G network rollout offers a genuinely significant opportunity for GNSS timing synchronization technology, since precise timing coordination across base stations is essential infrastructure that telecom operators can't build without reliable satellite-derived timing. Providers that build strong telecom industry relationships are positioned to capture substantial growth as 5G, and eventually 6G, networks continue expanding globally.
LEO-augmented positioning technology represents a second significant opportunity, letting developers offer stronger signal strength and better urban-environment performance than traditional MEO-based GNSS alone can provide. Companies that successfully commercialize LEO-based positioning as a genuine complement to existing constellations are positioned to capture premium positioning in applications where standard GNSS accuracy currently falls short.
Recent Developments:
-
December 2025: The European Union's Galileo system completed its 17th launch, continuing to build out its 30-satellite nominal constellation and improve global coverage precision.
-
March 2025: Russia launched the GLONASS-K2 satellite (Kosmos-2584), part of a continued modernization effort ahead of the first GLONASS-V satellite, planned for 2026-2027 to improve high-latitude coverage.
-
2025: The International Civil Aviation Organization's standards supporting dual-frequency, multi-constellation GNSS navigation continued driving aviation industry adoption of receivers compatible with Galileo, GLONASS, and BeiDou alongside GPS.
-
2025: Qualcomm expanded partnerships with automotive OEMs to integrate GNSS-based positioning solutions across a growing base of autonomous and driver-assistance vehicle platforms.
Satellite Navigation System Market Key Players
-
Garmin Ltd.
-
Trimble Inc.
-
Hexagon AB
-
Qualcomm Technologies, Inc.
-
Broadcom Inc.
-
Thales Group
-
RTX Corporation
-
L3Harris Technologies, Inc.
-
Lockheed Martin Corporation
-
Northrop Grumman Corporation
-
Honeywell International Inc.
-
Furuno Electric Co., Ltd.
-
Topcon Corporation
-
u-blox AG
-
STMicroelectronics N.V.
-
Septentrio N.V.
-
NovAtel Inc.
-
Swift Navigation, Inc.
-
TomTom N.V.
-
Quectel Wireless Solutions Co., Ltd.
Satellite Navigation System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 66.4 Billion |
| Market Size by 2035 | USD 103.0 Billion |
| CAGR | CAGR of 4.5% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Orbit Type (Geostationary Earth Orbit, Medium Earth Orbit, Low Earth Orbit, Other Orbits) • By Solution (Services, System & Devices) • By Constellation Type (Global Constellations, Regional Navigation Satellite Systems, Satellite-Based Augmentation Systems) • By Application (Road & Automotive, Location-Based Services, Agriculture, Surveying, Aviation & Maritime, Rail, Timing Synchronization, Others) • By Enterprise Size (Large Enterprises, Small & Medium Enterprises) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Garmin Ltd., Trimble Inc., Hexagon AB, Qualcomm Technologies, Inc., Broadcom Inc., Thales Group, RTX Corporation, L3Harris Technologies, Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, Honeywell International Inc., Furuno Electric Co., Ltd., Topcon Corporation, u-blox AG, STMicroelectronics N.V., Septentrio N.V., NovAtel Inc., Swift Navigation, Inc., TomTom N.V., Quectel Wireless Solutions Co., Ltd. |
Frequently Asked Questions
Key players include Garmin Ltd., Trimble Inc., Hexagon AB, Qualcomm Technologies, and Broadcom Inc., among others.
Key opportunities include autonomous vehicles, precision agriculture, 5G timing synchronization, LEO-augmented positioning, multi-constellation receivers, and high-precision navigation.
Growing development of autonomous vehicles and advanced driver-assistance systems combined with expanding precision agriculture adoption worldwide.
Road & Automotive dominated with approximately 34.0% share in 2025.
North America dominated the Satellite Navigation System Market in 2025, while Asia Pacific is the fastest-growing region.
