
Military Wearables Market Report Scope & Overview:
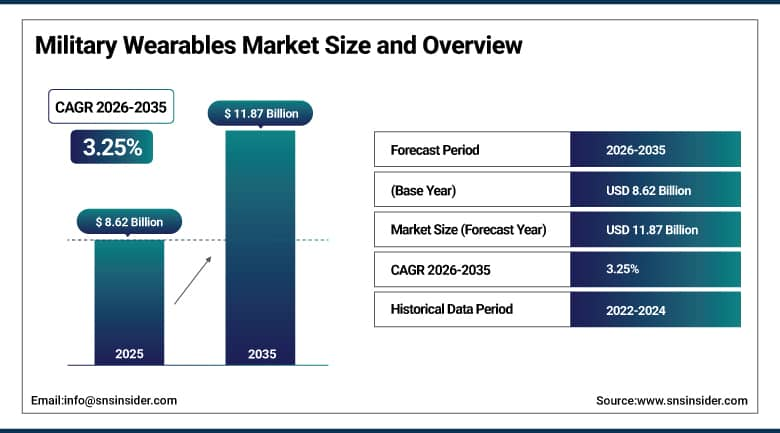
The global Military Wearables Market was valued at USD 8.62 Billion in 2025 and is expected to reach USD 11.87 Billion by 2035, growing at a CAGR of 3.25% from 2026 to 2035.
Military wearables technology is the term used for electronic gadgets that can be worn by soldiers or any other military staff while wearing their uniform or equipment. Military wearables include communication systems, navigation systems, sensor systems, smart watches, smart goggles, heads-up displays, and exoskeletons. The increased requirement of defense modernization, multi-domain operations requirements, and development in the field of sensor and analytics technologies has been playing a key role in further adoption of military wearables.
Anduril officially took over oversight of the US Army's troubled Integrated Visual Augmentation System program in 2025, with the Army pivoting the effort to Soldier Borne Mission Command, after the Government Accountability Office noted in July 2026 that none of the 10,000 developed IVAS units would be fielded, marking a dramatic restructuring of the originally Microsoft-led USD 22 billion, 10-year contract and reflecting the scale of program upheaval reshaping how the US military approaches next-generation soldier wearable technology.
Market Size and Forecast
- Market Size in 2026E: USD 8.90 Billion
- Market Size by 2035: USD 11.87 Billion
- CAGR: 3.25% from 2026 to 2035
- Fastest Growing Region: North America
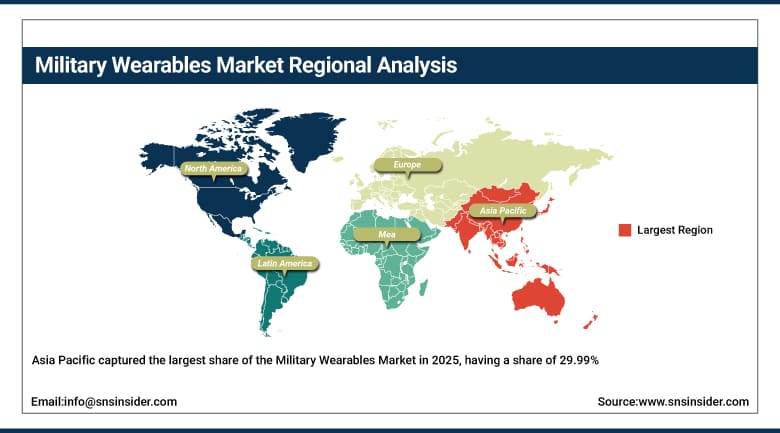
- Largest Region: Asia Pacific
To Get More Information On Military Wearables Market - Request Free Sample Report
Military Wearables Market Trends
- Growing real-time sensor fusion, autonomous decision support, and modular power systems continue turning connected gear into tactical force multipliers.
- Rising battery-energy density breakthroughs and hybrid micro-generators continue extending mission endurance and unlocking real-time data applications.
- Expanding AI integration for detecting fatigue, dehydration, or stress patterns in real-time continues offering significant scope for long-duration missions.
- Increasing exoskeleton adoption for load-bearing assistance and injury prevention continues reducing physical fatigue and improving operational efficiency.
- Growing smart textile integration with nanotechnology continues enabling real-time monitoring of muscle strain, hydration levels, and battlefield performance.
U.S. Military Wearables Market Outlook
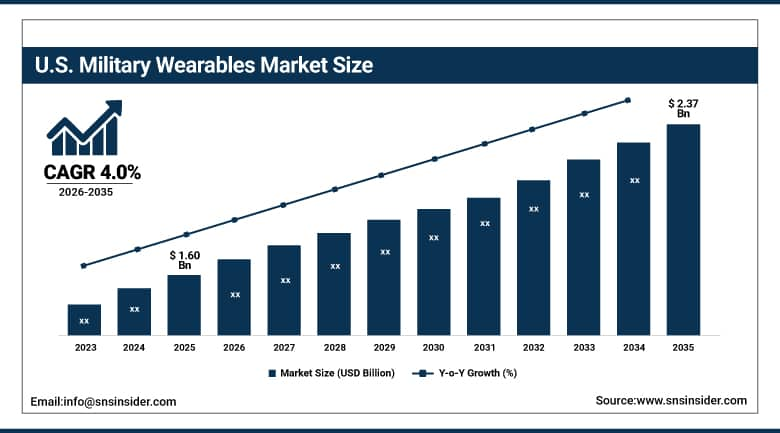
The U.S. Military Wearables Market was valued at USD 1.60 Billion in 2025 and is projected to reach USD 2.37 Billion by 2035, growing at a CAGR of 4.0% during 2026-2035.
Ongoing modernization and investments in the country continue to provide a solid base for continued growth of the market throughout the United States, as evidenced by the Integrated Visual Augmentation System program. Major companies continue to grow their night vision, helmet-mounted display and mission command wearable systems in response to increasing demand for them as part of Army modernization programs. An increased emphasis on soldier health and safety monitoring continues to fuel the sustained development of the domestic market.
The US Army signed an order worth $212 million with Elbit Systems of America in May 2026 for the continuous production of the Enhanced Night Vision Goggle-Binocular system until 2028, after a contract worth $120 million was signed in March 2026 to produce a helmet-mounted mission command system, which is capable of merging inputs from multiple battlefield sensors into one wearable device.
Military Wearables Market Segment Analysis
- By Wearable Type, smart textiles led the military wearables market share in 2025, while exoskeletons is the fastest-growing wearable type segment with a CAGR of 12.40% from 2026-2035.
- By End-User, land forces led the military wearables market with a 42.60% share in 2025, while air forces is the fastest-growing end-user segment with a CAGR of 11.20% from 2026-2035.
- By Application, communication & computing led the military wearables market with a 34.21% share in 2025, while power & energy management is the fastest-growing application segment with a CAGR of 8.66% from 2026-2035.
By Wearable Type, Smart Textiles Dominated the Market While Exoskeletons Is the Fastest-Growing Segment
Smart Textiles emerged as the leading product type segment in terms of the revenue share in 2025 owing to the growing use of sensor-enabled textile that allows the tracking of health, environmental factors, and battlefield performance of soldiers. With regard to the wide-ranging integration capacity that the smart textiles possess for various bodywear applications, the segment continues to dominate the military wearables market on a global scale.
The fastest growth rate of CAGR of 12.4% during 2026-2035 is expected to be recorded by the exoskeletons segment, supported by rising military expenditure on enhancing the mobility of soldiers along with injury prevention systems and technologies. The advanced exoskeletons, which minimize physical fatigue and enhance endurance of soldiers during mission operations, help in the growth of this segment above the average growth rate.
By End-User, Land Forces Dominated the Market While Air Forces Is the Fastest-Growing Segment
The land forces segment led the military wearables market with a revenue share of 42.60% in 2025, reflecting sustained ground force procurement demand for communication, navigation, and protective wearable technology. Land forces continue to represent the largest deployed personnel base across most armed forces globally, sustaining this end-user category's dominant position across the broader military wearables market worldwide.
The air forces segment is expected to register the fastest CAGR of 11.2% during the forecast period 2026-2035, driven by increasing demand for advanced wearable technologies such as helmet-mounted displays, physiological monitoring systems, and enhanced flight communication solutions. Modern combat aircraft programs and defense aviation industry modernization continue to reinforce this segment's above-average growth trajectory relative to the more established land forces category.
By Application, Communication & Computing Dominated the Market While Power & Energy Management Is the Fastest-Growing Segment
The communications and computing application segment occupied the top spot in terms of revenue contribution at 34.21% in 2025 due to continued demand for advanced headsets for communication and wearable computers to monitor enemy troops. The communication and computing remains the key application that enables effective battlefield coordination and hence the continued dominance of this application within the global military wearables market.
The power and energy management application segment is projected to post the highest CAGR of 8.66% during the forecast period 2026-2035, owing to advances in battery energy density and the emergence of hybrid micro-generators for prolonging missions and enabling real-time data applications. Demand for advanced modular power systems to accommodate the ever-increasing energy needs of wearable devices continues to boost growth of this application.
Regional Analysis
|
Region |
Country |
Regional Share (2025) |
|---|---|---|
|
Asia Pacific |
China |
32.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
22.80% |
|
Middle East & Africa |
UAE |
24.60% |
|
Latin America |
Brazil |
24.60% |
Asia Pacific Military Wearables Market Insights
Asia Pacific captured the largest share of the Military Wearables Market in 2025, having a share of 29.99%, due to increasing defense modernization initiatives and military technology spending in the region. With the increasing adoption of pilot projects, such as the project undertaken by Japan to integrate smart textiles into its Ground Self Defense Forces, Asia Pacific will maintain its dominant position in the military wearables market.
China held around 32.60% of the Asia Pacific market in 2025, owing to the rapid expansion of the country's capabilities in domestic defense manufacturing and military modernization spending. Japan, India, and South Korea also contribute significantly to the growth of the market in the region, with Japan working together with defense technology companies in the United States on smart textiles.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Military Wearables Market Insights
North America to grow progressively through major programs like the USD 22 billion Integrated Visual Augmentation System initiative, driving substantial regional investment despite recent program restructuring. The region is projected to register the fastest CAGR during the forecast period, driven by sustained defense modernization spending and evolving soldier wearable technology programs.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its concentration of leading defense wearable manufacturers including Elbit Systems of America, Anduril, and L3Harris. Canada is contributing to regional growth through steady defense procurement and growing interest in modernized soldier equipment.
Europe Military Wearables Market Insights
The share of Europe in the Military Wearables Market was significant in 2025, owing to growing defense budgets as well as geopolitical instability and modernization efforts of NATO countries in the region. The continued research on exoskeletons and smart textiles by European defense firms is further expected to drive demand in the region.
Germany had the highest share in the European Military Wearables Market at 22.80% in 2025 owing to its strong defense manufacturing sector and increasing investments in military modernization. The United Kingdom, France, and Israel's presence in Europe are some other factors contributing significantly to the market growth in the region.
Middle East & Africa and Latin America Military Wearables Market Insights
The Middle East & Africa region is exhibiting steady growth as defense modernization and military infrastructure investment continue expanding across the Gulf states. Latin America is similarly benefiting from expanding military procurement activity and growing consumer interest in modernized soldier wearable technology.
The UAE led the Middle East & Africa market with a 24.60% regional share in 2025, supported by significant defense modernization investment and expanding military infrastructure. Brazil represented 24.60% of the Latin American market in 2025, driven by expanding military procurement activity, with Mexico also contributing to regional growth through rising interest in modernized soldier equipment.
Market Dynamics
Growth Drivers: Defense Modernization Investment and Soldier Safety Technology Driving Market Growth
The Military Wearables Market is being driven primarily by technological advancements and the need for operational efficiency, with heightened defense modernization, rising multi-domain operation needs, and advancements in sensor and analytics technologies catalyzing adoption across global armed forces. Integrating technologies like the Internet of Things, artificial intelligence, and wearable sensors into military gear continues to enhance situational awareness, real-time data collection, and communication capabilities.
Growing real-time sensor fusion, autonomous decision support, and modular power systems continue turning connected gear into tactical force multipliers. Rising battery-energy density breakthroughs continue extending mission endurance. Expanding AI integration for detecting fatigue, dehydration, or stress patterns continues offering significant scope for long-duration missions, reinforcing sustained industry investment.
Restraints: Program Cost Overruns and Physiological Compatibility Issues Limiting Market Expansion
Despite favorable underlying demand, the market faces meaningful restraints related to program cost overruns and technical setbacks, as demonstrated by the IVAS program's troubled development history involving multiple failed increments before transitioning to a new prototyping effort. Early versions of advanced wearable systems reportedly causing users to suffer mission-affecting physical impairments, including headaches, eyestrain, and nausea, continue to require sustained investment in ergonomic redesign.
Growing competitive intensity among an expanding roster of defense wearable manufacturers, particularly amid program restructuring activity creating uncertainty for established vendors, continues to reshape competitive dynamics across the broader military wearables market. High component-level qualification and configuration control requirements also continue to limit market entry for smaller manufacturers.
Opportunities: Exoskeleton Technology Advancement and AI-Powered Health Monitoring Creating New Growth Avenues
Substantial opportunity exists in continued development of powered and passive exoskeleton technology capable of reducing physical fatigue while improving load-bearing capacity and mission endurance. Companies that successfully commercialize lightweight, high-torque exoskeleton systems stand to capture significant share of category growth as field tests demonstrate substantial reductions in metabolic cost among equipped soldiers.
Growing AI-powered predictive health monitoring presents a further significant growth avenue, as defense agencies increasingly seek wearable neural interfaces and biometric sensors capable of improving soldier-machine coordination. Expanding smart textile and nanotechnology integration across allied nations' modernization programs also represents meaningful untapped opportunity for military wearables manufacturers.
Recent Developments:
- 2025: Elbit Systems announced successful field testing of its SmartVest technology for elite infantry units, integrating physiological monitoring, GPS tracking, and bullet-resistant fabric.
- 2025: BAE Systems revealed a new exoskeleton prototype reducing musculoskeletal strain and improving load-carrying efficiency for dismounted soldiers.
- 2025: Lockheed Martin collaborated with Honeywell International to develop wearable computing systems supporting AR-based maintenance and tactical training.
- 2025: Japan's Ministry of Defense launched a pilot program integrating smart textiles embedded with nanotechnology into tactical uniforms for the Ground Self-Defense Forces.
Military Wearables Market key players are:
- Elbit Systems Ltd.
- BAE Systems plc
- L3Harris Technologies, Inc.
- Thales Group
- Rheinmetall AG
- Leonardo S.p.A.
- Honeywell International Inc.
- Safran S.A.
- Lockheed Martin Corporation
- General Dynamics Corporation
- Anduril Industries, Inc.
- Revision Military Ltd.
- Invisio Communications AB
- Gentex Corporation
- Point Blank Enterprises, Inc.
- Sarcos Technology and Robotics Corporation
- Ekso Bionics Holdings, Inc.
- Ultra Electronics Holdings plc
- DuPont de Nemours, Inc.
- W.L. Gore & Associates, Inc.
Military Wearables Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.62 Billion |
| Market Size by 2035 | USD 11.87 Billion |
| CAGR | CAGR of 3.25% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Wearable Type (Smart Textiles, Bodywear, Headwear, Eyewear, Exoskeletons, Hearables) • By Application (Communication & Computing, Vision & Surveillance, Power & Energy Management, Health Monitoring) • By End-User (Land Forces, Air Forces, Naval Forces, Special Operations) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Elbit Systems Ltd.; BAE Systems plc; L3Harris Technologies, Inc.; Thales Group; Rheinmetall AG; Leonardo S.p.A.; Honeywell International Inc.; Safran S.A.; Lockheed Martin Corporation; General Dynamics Corporation; Anduril Industries, Inc.; Revision Military Ltd.; Invisio Communications AB; Gentex Corporation; Point Blank Enterprises, Inc.; Sarcos Technology and Robotics Corporation; Ekso Bionics Holdings, Inc.; Ultra Electronics Holdings plc; DuPont de Nemours, Inc.; W.L. Gore & Associates, Inc. |
Frequently Asked Questions
The Military Wearables Market is expected to grow at a CAGR of 3.25% from 2026 to 2035.
The Military Wearables Market was valued at USD 8.62 Billion in 2025.
The market is driven by technological advancements, the need for operational efficiency, and heightened defense modernization across global armed forces.
The Smart Textiles segment dominated the Military Wearables Market in 2025, accounting for approximately 19.0% market share.
