
Seafood Packaging Market Report Scope & Overview:
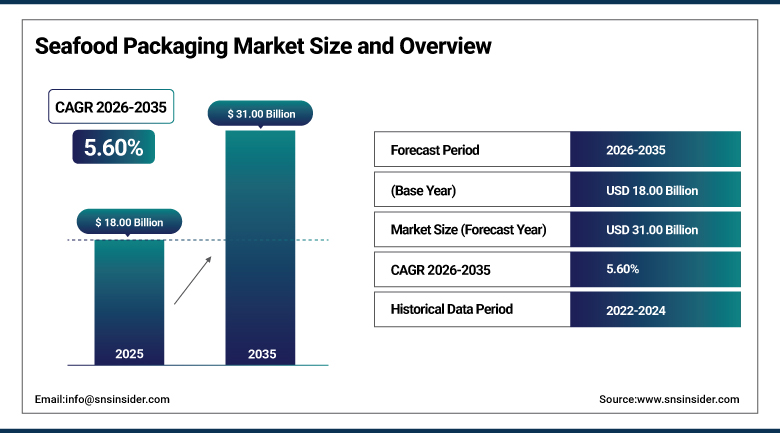
The Seafood Packaging Market was valued at USD 18.00 Billion in 2025 and is expected to reach USD 31.00 Billion by 2035, growing at a CAGR of 5.60% from 2026–2035.
The Seafood Packaging market is expected to experience growth owing to the increased consumption of seafood all over the globe, better cold chain logistics and demand for efficient packaging methods. The growing popularity of fresh, frozen, and processed seafood products is increasing the demand for sturdy packaging which helps in extending the life of the products and avoiding any form of contamination to the products. Modified Atmosphere packaging, Vacuum packing, and advanced packaging barriers have gained importance as companies seek to retain the freshness of the product and avoid any kind of wastage.
DS Smith launched its DryPack seafood box in North America, offering a fully recyclable, water-resistant fiber alternative to expanded polystyrene foam. The box keeps fresh fish below 40°F for over 40 hours with ice and is approved for air freight by IATA, supporting sustainable seafood packaging and reducing reliance on problematic plastics.
To Get more information Seafood Packaging Market - Request Free Sample Report
Seafood Packaging Market Trends
-
Rising demand for packaged seafood driven by expanding cold-chain distribution, processed seafood consumption, and retail availability worldwide
-
Growing adoption of modified atmosphere packaging (MAP) and vacuum packaging to extend seafood shelf life, preserve freshness, and reduce spoilage during storage and transportation
-
Increasing focus on sustainable packaging materials, including recyclable, biodegradable, and fiber-based solutions, in response to environmental concerns and plastic reduction initiatives
-
Expanding use of active and intelligent packaging technologies incorporating oxygen scavengers, freshness indicators, and temperature monitoring to improve seafood quality and supply-chain visibility
-
Continuous advancements in high-barrier films, multilayer materials, and leak-resistant packaging designs enhancing protection against moisture, oxygen, contamination, and physical damage throughout distribution chains
U.S. Seafood Packaging Market Outlook
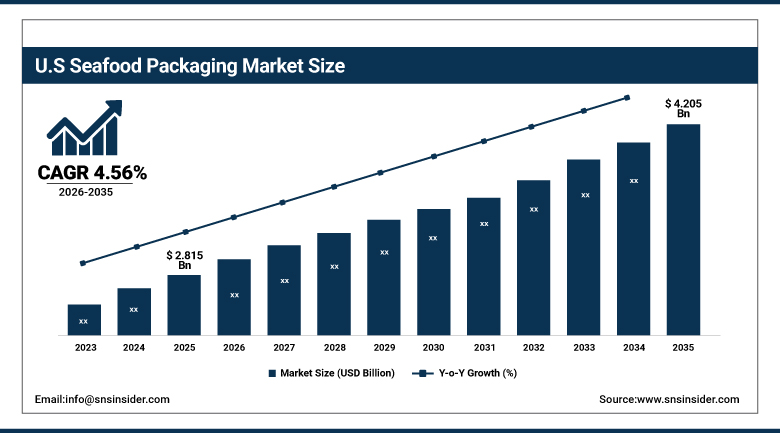
The U.S. Seafood Packaging Market was valued at approximately USD 2.815 Billion in 2025 and is expected to reach approximately USD 4.205 Billion by 2035, growing at a CAGR of approximately 4.56%.
Demand in the United States is driven by strong consumer preference for convenience and fresh, high-quality seafood, with consumers showing growing interest in ready-to-eat and pre-portioned formats that depend heavily on freshness-extending packaging technology. A concentration of major global packaging manufacturers with significant domestic operations continues supplying both flexible and rigid seafood packaging formats to processors and retailers nationwide. Growing retailer and regulatory pressure to phase out non-recyclable expanded polystyrene foam packaging continues reshaping material specification requirements across the domestic seafood supply chain.
Amcor announced a significant expansion of printing, lamination, and converting capabilities at existing North American facilities in November 2025, specifically targeting the protein market, which includes meat, poultry, and seafood packaging as one of the company's six high-growth, high-margin focus categories.
Seafood Packaging Market Segment Analysis
-
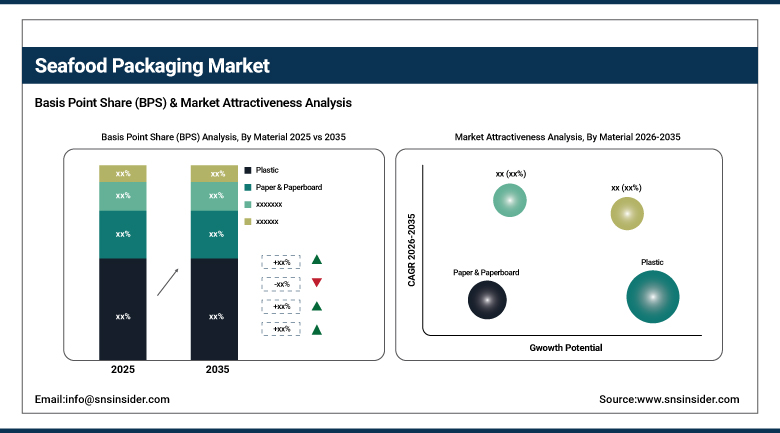
By Material, the Plastic segment dominated the Seafood Packaging Market with approximately 64.00% share in 2025, while the Paper & Paperboard segment is the fastest growing with a CAGR of approximately 6.50%.
-
By Packaging Technology, the Modified Atmosphere Packaging segment dominated the Seafood Packaging Market with approximately 47.00% share in 2025, while the Vacuum Skin Packaging segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Product Type, the Bags & Pouches segment dominated the Seafood Packaging Market with approximately 35.00% share in 2025, while the Trays segment is the fastest growing with a CAGR of approximately 6.60%.
-
By Application, the Fresh & Frozen Seafood segment dominated the Seafood Packaging Market with approximately 58.60% share in 2025, and is also the fastest growing with a CAGR of approximately 6.20%.
-
By Seafood Type, the Fish segment dominated the Seafood Packaging Market with approximately 46.20% share in 2025, while the Molluscs segment is the fastest growing with a CAGR of approximately 6.90%.
By Material, plastic dominates, paper & paperboard grows fastest
Plastic held the large majority of the material segment in 2025, valued for its moisture resistance, flexibility, and compatibility with high-speed vacuum and modified atmosphere packaging lines that dominate modern seafood processing operations. That combination of barrier performance and processing efficiency keeps plastic the default material choice across the overwhelming majority of seafood packaging formats, from fillet pouches to frozen shrimp bags.
Paper and paperboard is growing fastest due to the growing need for recyclable and environmentally friendly packaging options, with adoption accelerating as environmental regulations tighten and consumer preference shifts toward packaging free of plastic. Fiber-based replacements for expanded polystyrene foam boxes in cold-chain shipping applications are reinforcing this above-average growth trajectory relative to the broader, plastic-dominated material mix.
By Packaging Technology, modified atmosphere packaging dominates, vacuum skin packaging grows fastest
Modified atmosphere packaging held the largest share of the packaging-technology segment in 2025, valued for its ability to extend shelf life by regulating oxygen levels around the product, a critical function given how quickly seafood spoils compared to most other protein categories. That shelf-life extension capability keeps modified atmosphere packaging the dominant technology across fresh and processed seafood retail formats worldwide.
Vacuum skin packaging is growing fastest as this technology delivers a tight, form-fitting seal around the product that both extends freshness and provides the clear, appealing visual presentation retailers increasingly demand for premium seafood displays. Growing consumer preference for products where they can directly see the quality and freshness of the seafood before purchase continues reinforcing this above-average growth trajectory.
By Product Type, bags & pouches dominates, trays grows fastest
Bags and pouches held the largest share of the product-type segment in 2025, favored for their lightweight design, sealing efficiency, and compatibility with modified atmosphere and vacuum packaging systems used widely across fish fillets, shellfish, and processed seafood. Innovations such as resealable zippers and antimicrobial coatings continue enhancing this format's portability, reduced material usage, and improved shelf appeal, keeping bags and pouches the dominant product type across the broader market.
Trays are growing fastest as rising demand for portion-controlled and ready-to-cook packaging formats continues expanding, particularly for pre-portioned fillets and shellfish sold through retail channels emphasizing convenience. Growing retail merchandising preference for trays that display product attractively while supporting modified atmosphere sealing continues reinforcing this above-average growth trajectory.
By Application, fresh & frozen seafood dominates and grows fastest
Fresh and frozen seafood held the largest share of the application segment in 2025, increasingly focused on maintaining product quality and meeting sustainability demands across both domestic retail and international export supply chains. Technologies like modified atmosphere packaging and vacuum-sealed pouches remain especially popular in this application for extending shelf life and preventing spoilage, keeping fresh and frozen seafood the anchor application across the broader market.
Fresh and frozen seafood is also the fastest-growing application, driven by rising consumer demand for high-quality, minimally processed seafood products alongside growing global cold-chain infrastructure investment that makes reliable fresh and frozen distribution increasingly practical across longer distances. That combination of consumer preference and infrastructure investment continues reinforcing this application's above-average growth trajectory relative to processed seafood alternatives.
By Seafood Type, fish dominates, molluscs grows fastest
Fish held the largest share of the seafood-type segment in 2025, reflecting the sheer scale of global fish production and consumption relative to shellfish, molluscs, and other seafood categories combined. That production and consumption scale keeps fish the dominant seafood-type category across the broader packaging market by a wide margin over other categories.
Molluscs are growing fastest as the amounts of oysters, clams, mussels, and scallops consumed worldwide continue rising, with packaging needs increasing due to export demand for molluscs' premium positioning in global markets. Specialized packaging solutions ensuring safe long-distance transportation, contamination avoidance, and freshness preservation for this more delicate seafood category continue reinforcing this above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
41.60% |
|
North America |
United States |
79.80% |
|
Europe |
Germany |
25.30% |
|
Latin America |
Brazil |
35.60% |
|
Middle East & Africa |
UAE |
29.40% |
North America Seafood Packaging Market Insights
North America offers an important market for packaging of seafood owing to the high consumer preference in the US for convenient and fresh and good quality seafood. In line with consumers' growing preference for pre-cut or ready-to-eat seafood, there is a continued high demand for packaging technologies which can help in maintaining the freshness of the product for long periods of time including vacuum packing and modified atmosphere packing.
Canada also adds to the demand due to its sizable seafood harvesting and processing industry while Mexico also represents a growing market with increased production of seafood for exports. North American demand is often linked by cross border supply chains with the big seafood packagers usually operating in all three markets through common production facilities.
Europe Seafood Packaging Market Insights
Europe is an example of an advanced and sustainable Seafood Packaging Market, due to tight EU packaging waste legislation and changing consumer preference towards packaging solutions that are recyclable and have a low plastic content. The leading market in Europe is Germany, which is helped by the presence of a large food processing and retail industry, along with robust packaging manufacturing sector. Increasing focus on recyclable and lightweight packaging materials is further aiding growth in the market. Growing consumption of seafood, food safety regulations, and increasing awareness regarding packaging waste are motivating manufacturers towards sustainable practices in the region.
Other significant markets in Europe include France, Italy, and Netherlands, which have sizeable seafood imports, processing, and retail segments in response to EU sustainability legislation. Increasing importance being given to smart labels within the region due to regulatory pressures is influencing product development more in Europe than in any other market around the world.
Asia Pacific Seafood Packaging Market Insights
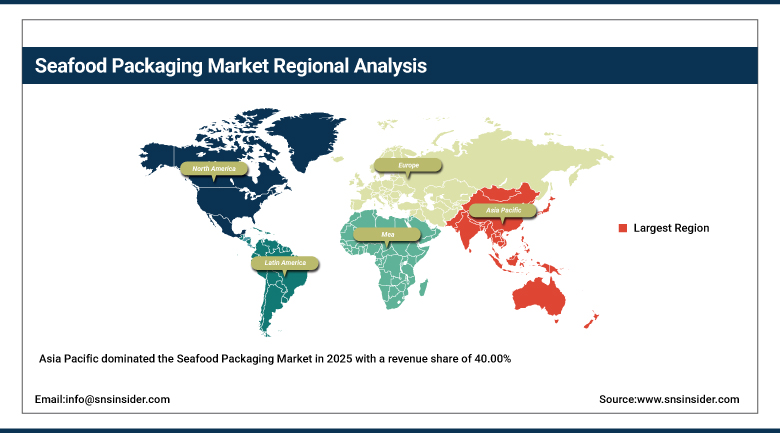
The Asia Pacific dominated the Seafood Packaging Market in 2025 with a revenue share of 40.00%, and is forecasted to exhibit rapid growth among all other regions up to 2035. This dominance is due to robust production of seafood in countries such as China, India, Indonesia, Vietnam, and Japan. Rising consumption, population size, increase in disposable income, and increased seafood export will lead to increased demand for packaging materials to ensure freshness, quality, and safety. Increased processing and development of cold chain will be additional growth drivers.
High seafood production and processing capacity in China gives the region high baseline demand, and China itself is anticipated to exhibit rapid CAGR till 2035 owing to rising seafood demand and technological innovation in packaging. In addition, expansion in organized processing and export of seafood in India is attracting investments, and Japan & South Korea can be considered as matured markets with focus on quality and sustainability of packaging materials.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Seafood Packaging Market Insights
The Middle East and Africa represent a smaller but developing seafood packaging market, with the UAE driving demand through growing hospitality, tourism, and food import sectors tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader seafood processing and organized retail infrastructure development.
Latin America is a growing market led by Brazil, where expanding seafood harvesting and processing continue driving demand for freshness-extending packaging across both domestic consumption and export-oriented supply chains. Mexico and Argentina contribute meaningful secondary demand, tied to their own substantial seafood export industries.
Market Dynamics
Growth Drivers: Rising seafood consumption and expanding aquaculture fueling adoption
Increased demand for seafood worldwide is one of the clearest forces behind rising seafood packaging demand, as growing global protein consumption continues expanding the addressable market for freshness-extending, shelf-life-improving packaging technology across nearly every major seafood-consuming region. That fundamental consumption growth gives the seafood packaging market a demand base that holds up reliably across broader economic cycles.
Expanding aquaculture production adds a second major driver, as fish farming continues supplementing wild-catch seafood supply and requiring the same cold-chain-compatible packaging technology that wild-caught seafood depends on. The rapid growth in global seafood consumption, combined with rising global seafood trade and stringent food safety regulations, continues boosting adoption of high-quality, sustainable packaging solutions across the industry.
Restraints: Raw material price volatility and recycling infrastructure gaps limiting margin stability
Fluctuating plastic resin and paperboard prices add real cost unpredictability for manufacturers, since seafood packaging producers remain exposed to broader petrochemical and pulp commodity market swings that directly affect production costs across every material category. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-packaging demand remains steady.
Uneven recycling infrastructure across different markets adds a further restraint, since multi-layer plastic films combining barrier and structural properties require specialized processing that many regions haven't yet built at meaningful scale. That infrastructure gap limits how quickly genuine circularity can improve even as producers invest heavily in mono-material and fiber-based redesigns as an alternative pathway.
Opportunities: Fiber-based EPS replacement and smart traceability labeling opening new growth avenues
Fiber-based replacement for expanded polystyrene foam packaging offers manufacturers a genuine path to capturing premium business from seafood processors chasing credible sustainability commitments while maintaining the cold-chain performance foam has traditionally delivered. Companies that successfully develop fully recyclable, air-freight-approved fiber alternatives are positioned to capture significant new business as retailer and regulatory pressure on foam packaging continues building.
Smart traceability labeling represents a second significant opportunity, as expanding regulatory and consumer demand for verified origin and cold-chain handling history continues driving adoption of QR codes and other digital traceability features. Manufacturers that build genuine smart labeling capability are positioned to capture premium pricing from retailers and brand owners seeking supply chain transparency beyond basic packaging function.
Recent Developments:
-
November 2025: Amcor announced a significant expansion of printing, lamination, and converting capabilities at North American facilities to support growing protein market demand, including seafood packaging.
-
November 2025: Amcor launched its Lift-Off Winter 2025/26 Challenge, inviting start-ups to develop home-compostable adhesives and high-performance compostable oxygen barrier solutions for flexible and paper-based packaging.
-
2025: DS Smith was acquired by International Paper, further consolidating fiber-based packaging capacity serving the seafood and broader food packaging industry.
-
2025: Amcor reported that approximately 9% of its production revenue came from fiber-based materials, reflecting continued diversification beyond traditional plastic packaging formats.
Seafood Packaging Market Key Players
-
Amcor plc
-
Sealed Air Corporation
-
Berry Global Inc.
-
Mondi plc
-
Winpak Ltd.
-
DS Smith plc
-
Sonoco Products Company
-
ProAmpac
-
Coveris Holdings S.A.
-
Smurfit Kappa Group
-
Crown Holdings, Inc.
-
Silgan Holdings Inc.
-
Huhtamaki Oyj
-
Stora Enso Oyj
-
Printpack, Inc.
-
ULMA Packaging
-
Constantia Flexibles Group GmbH
-
AptarGroup, Inc.
-
Klöckner Pentaplast Group
-
Cascades Inc.
Seafood Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.00 Billion |
| Market Size by 2035 | USD 31.00 Billion |
| CAGR | CAGR of 5.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Plastic, Paper & Paperboard, Metal, Glass, Others) • By Packaging Technology (Modified Atmosphere Packaging, Vacuum/Vacuum Skin Packaging, Active Packaging, Intelligent Packaging) • By Product Type (Bags & Pouches, Cans, Boxes, Trays, Others) • By Application (Fresh & Frozen Seafood, Processed Seafood) • By Seafood Type (Fish, Shellfish/Crustaceans, Molluscs, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Sealed Air Corporation, Berry Global Inc., Mondi plc, Winpak Ltd., DS Smith plc, Sonoco Products Company, ProAmpac, Coveris Holdings S.A., Smurfit Kappa Group, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Stora Enso Oyj, Printpack, Inc., ULMA Packaging, Constantia Flexibles Group GmbH, AptarGroup, Inc., Klöckner Pentaplast Group, Cascades Inc. |
Frequently Asked Questions
Key players in the Seafood Packaging Market include Amcor plc, DS Smith plc, Constantia Flexibles Group GmbH, Berry Global Inc., and Mondi Group, among others.
Key opportunities in the Seafood Packaging Market include fiber-based replacement for expanded polystyrene foam packaging and smart traceability labeling for verified origin and cold-chain handling history.
The market is driven by increased demand for seafood worldwide, combined with expanding aquaculture production requiring cold-chain-compatible packaging technology.
The Plastic segment dominated the Seafood Packaging Market, accounting for approximately 64.00% market share.
The Asia Pacific region dominated the Seafood Packaging Market in 2025 with more than 40.00% share, driven by the region's leadership in global seafood production.
