
Smart Packaging Market Report Scope & Overview:
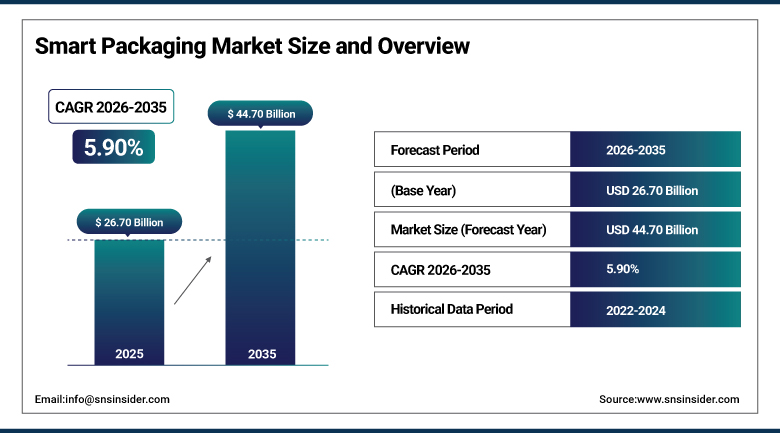
The Smart Packaging Market was valued at USD 26.70 Billion in 2025 and is expected to reach USD 44.70 Billion by 2035, growing at a CAGR of 5.90% from 2026 to 2035.
The smart packaging a label that can tell a retailer exactly when a shipment left the warehouse, a film that changes color as a product approaches spoilage, a sensor that alerts a pharmacy the moment a cold-chain vaccine strayed outside its temperature range, these are not hypothetical features anymore, they are increasingly standard specifications that brand owners and regulators expect. Roughly 40% of global plastic packaging waste has become one of the largest single contributors to pollution, and that pressure is pushing smart packaging investment toward solutions that improve both traceability and material efficiency at once.
In April 2025, Avery Dennison Corporation opened its first RFID inlay and label manufacturing plant in Pune, India, supporting the country's 'Make in India' initiative and expanding regional smart labeling capacity.
To Get more information Smart Packaging Market - Request Free Sample Report
Smart Packaging Market Trends
- Active packaging technologies, oxygen scavengers, moisture absorbers, freshness indicators, continue holding the largest share of smart packaging adoption.
- NFC-enabled packaging is expanding fastest as smartphones make consumer engagement features accessible without dedicated scanning hardware.
- E-commerce and logistics applications are driving demand for tamper-evident, real-time tracking packaging solutions.
- Energy-harvesting inks and printed electronics are emerging as alternatives to thin-film batteries in smart labels.
- Software ecosystems and data subscription models are becoming as important to competitive positioning as physical label innovation.
The U.S. Smart Packaging Market Outlook
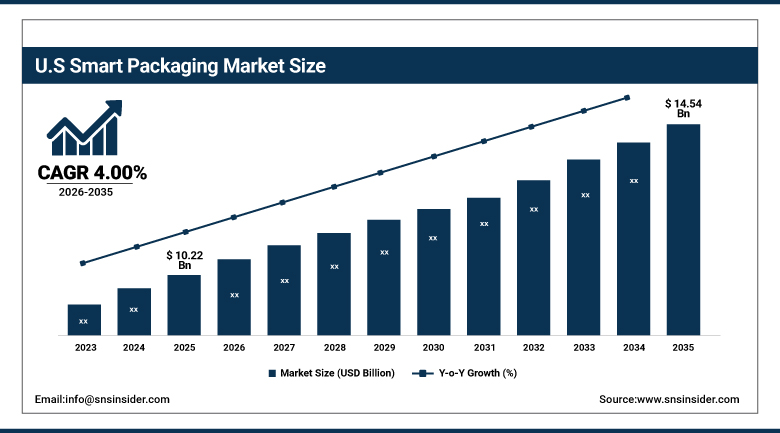
The U.S. Smart Packaging Market was valued at USD 10.22 Billion in 2025 and is projected to reach USD 14.54 Billion by 2035, growing at a CAGR of 4.00% during 2026-2035.
The U.S. market for smart packaging is being propelled by increasing adoption of connected packaging solutions among the segments of pharmaceuticals, food & beverages, and e-commerce. In the pharmaceutical segment, U.S. companies are utilizing serialization, RFID, and other digital identification solutions to improve package level tracking and security of the supply chain under the Drug Supply Chain Security Act (DSCSA). For food packaging, increasing demands of traceability are leading manufacturers and retailers to develop digitally-enabled packaging solutions to help in better identification and traceability of the product in the supply chain. Further, FDA's traceability initiatives for 2026 underscore the need for digital records and fast-tracking of products in the U.S. food supply chain.
In November 2024, VarieT Technology unveiled its Smart Heat Battery, a self-heating insert designed for on-demand warming of canned food and beverage products.
Smart Packaging Market Segment Analysis
- By Product Type, active packaging segment dominated the smart packaging market in 2025 with 58.50% share; intelligent packaging segment is the fastest-growing segment, registering a CAGR of 8.60% from 2026 to 2035.
- By Technology Type, RFID segment dominated the market in 2025 with 38% share; NFC segment is the fastest-growing segment, registering a CAGR of 9.20% from 2026 to 2035.
- By End-Use Industry, food & beverage segment dominated the market in 2025 with 44% share; e-commerce & logistics segment is the fastest-growing segment, registering a CAGR of 9.60% from 2026 to 2035.
- By Level of Packaging, primary packaging segment dominated the market in 2025 with 52% share; secondary packaging segment is the fastest-growing segment, registering a CAGR of 8.80% from 2026 to 2035.
By Product Type, active packaging dominates the smart packaging market while intelligent packaging grows fastest
The biggest smart packaging segment is active packaging, which has 58.50% share of the overall market. Active packaging is the most prominent product category in terms of the decades-long experience with oxygen scavengers, moisture absorbers, and freshness indicators, increasing the shelf life of the packaged goods. The significance of active packaging is driven by its value proposition – it actively changes the environment inside the packaging to keep the quality of the product, which gives a tangible return on investment that can be justified better than some other features.
Intelligent packaging is growing at an 8.60% CAGR, the fastest pace among product types, as brands increasingly adopt packaging that can store, capture, and transmit data, rather than simply altering internal package conditions, to support traceability and consumer engagement objectives. Integration with IoT and Industry 4.0 supply chain initiatives is reinforcing this growth, as manufacturers increasingly view intelligent packaging as a genuine data collection point rather than a standalone feature.
By Technology Type, RFID dominates the smart packaging market while NFC grows fastest
RFID is at the top end of the market by technology, having 38%, being the most mature technology in smart packaging due to the reliability of the technology in the management of inventories, anti-theft measures, and supply chain visibility within retail, pharmaceutical, and logistics sectors. The investment in building more RFID manufacturing capabilities through the creation of RFID inlays and labels facilities is indicative of this fact.
NFC technology is expanding fastest in terms of technology type, with a 9.20% CAGR, because it relies on scanning through smartphones, thus ensuring that consumer-related functionalities can be accessed without necessitating investments in scanning equipment by brands. This convenience has been a driving force behind the popularity of NFC for consumer-related functions such as product verification, marketing material that is personalized, and information regarding the ingredients or origin of products.
By End-Use Industry, food & beverage dominates the smart packaging market while e-commerce & logistics grows fastest
Food & Beverage accounts for 44% of end-use demand, the largest single category, reflecting how central shelf-life extension and freshness verification have become to modern food retail, where spoilage losses carry direct financial consequences for both producers and retailers. Rising food safety regulation and growing consumer expectation for verifiable freshness information continue reinforcing this category's lead across both packaged food and fresh produce applications.
E-commerce & logistics is the fastest-growing end-use industry, expanding at a 9.60% CAGR, as direct-to-consumer shipping volumes continue climbing and brands increasingly need tamper-evident, trackable packaging to protect delivery reliability through complex, multi-stage shipping journeys. Real-time tracking and condition monitoring capabilities, once a logistics-industry-only feature, are increasingly built directly into consumer packaging as e-commerce brands compete on delivery transparency.
By Level of Packaging, primary packaging dominates the smart packaging market while secondary packaging grows fastest
Primary Packaging holds 52% of the market by level of packaging, the largest single category, reflecting that smart features deliver the most value when integrated directly into the packaging that actually touches the product, whether that is an active freshness indicator or an intelligent label carrying product-specific data. Direct product contact gives primary packaging a natural advantage for both active technologies that need to interact with the product environment and intelligent technologies that need to carry item-specific information.
Secondary Packaging is growing fastest, at an 8.80% CAGR, as logistics and supply chain visibility applications increasingly favor smart features built into cartons and shipping containers rather than individual product packaging, particularly for bulk and business-to-business shipments. Growing warehouse automation and Industry 4.0 supply chain initiatives are reinforcing this trend, since secondary packaging level tracking supports pallet and case-level visibility that individual primary package tracking cannot efficiently provide.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.00% |
|
Asia Pacific |
China |
45.00% |
|
Europe |
Germany |
25.60% |
|
Middle East & Africa |
UAE |
17.40% |
|
Latin America |
Brazil |
26.80% |
North America Smart Packaging Market Insights
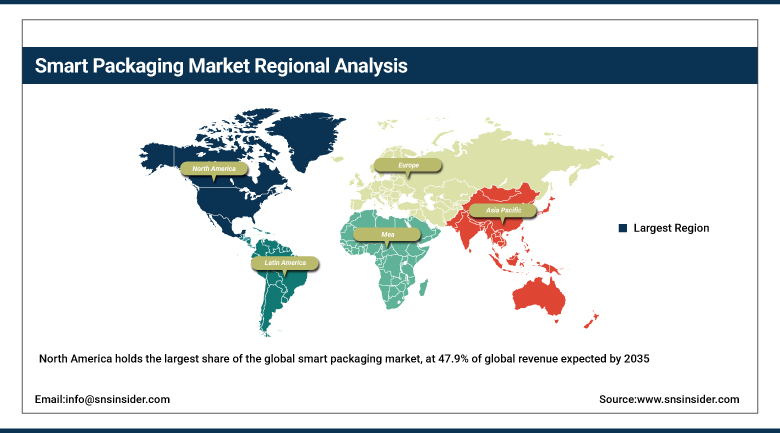
North America holds the largest share of the global smart packaging market, at 47.9% of global revenue expected by 2035, supported by a strong domestic focus on innovation and technology alongside well-established pharmaceutical cold-chain monitoring and e-commerce infrastructure. Rising consumer expectation for interactive packaging experiences continues reinforcing demand across the region's mature, technology-forward retail environment.
The United States accounts for approximately 85.00% of the North American market, reflecting its deep concentration of smart packaging technology developers and manufacturers. Canada contributes a smaller but steady share, tied to its own pharmaceutical and food safety regulatory standards and comparable retail technology adoption.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Smart Packaging Market Insights
Europe's smart packaging market is mature and shaped heavily by packaging waste regulation and strong consumer sustainability expectations, roughly 67% of consumers say they are willing to pay more for sustainable brands, which is pushing manufacturers toward smart packaging solutions that improve both traceability and material efficiency simultaneously. Strong pharmaceutical serialization requirements across the region continue reinforcing steady demand for intelligent packaging technologies.
Germany leads the European market with a 25.60% share, supported by its large pharmaceutical and food manufacturing base and advanced packaging technology industry. France and the United Kingdom follow, with demand in both countries tied to comprehensive product traceability regulation and growing e-commerce packaging requirements.
Asia Pacific Smart Packaging Market Insights
In terms of growth, Asia Pacific has been outperforming all other regions in the market on account of China being the leading smart packaging component manufacturing country and fast-growing e-commerce and pharmaceutical industry in the region. Increased manufacturing capacity for RFID inlays and labels in the region is adding strength to both the internal consumption and export potential.
China dominates 45.00% of the regional market on account of its huge manufacturing capacity for electronics and packaging component industry along with rapidly developing e-commerce logistics industry. India is fast growing due to its growing manufacturing capacity for RFID and smart labeling and Japan/South Korea are contributing because of their well-established electronics and packaging industries.
Middle East & Africa and Latin America Smart Packaging Market Insights
The Middle East & Africa region is growing steadily as pharmaceutical and food import volumes both expand across the Gulf states, supported by rising regulatory attention to product traceability and counterfeiting prevention. Latin America's growth follows a similar arc, driven by Brazil's expanding food and pharmaceutical manufacturing sectors and growing e-commerce adoption across the region.
The UAE leads the Middle East & Africa market with a 17.40% share, supported by its role as a regional pharmaceutical and consumer goods distribution hub. Brazil represents 26.80% of the Latin American market, reflecting its large food and pharmaceutical manufacturing base, with Mexico also contributing through its growing e-commerce and packaged goods sectors.
Market Dynamics
Growth Drivers: Product Safety Demand and Supply Chain Transparency Fueling Market Growth
The rising need for improved product safety and supply chain transparency is undoubtedly the most evident factor driving this industry, since an increasing number of brands, from food to pharmaceuticals and e-commerce industries, are in need of such packaging which will provide evidence rather than guaranteeing the quality of their products during transport. The growing packaging waste regulations and food safety regulations are also contributing to this trend.
Rising consumer expectation for interactive, personalized packaging experiences is adding a meaningful additional demand line, as smartphone-based scanning makes engagement features increasingly accessible and brands compete for shelf differentiation through packaging technology rather than price alone.
Restraints: Implementation Cost and Data Privacy Concerns Limiting Market Expansion
Smart packaging technology carries a genuine cost premium over standard packaging, and that added expense can be difficult for smaller brands and cost-sensitive product categories to absorb, particularly for features that deliver more marketing value than functional protection benefit. Data privacy and cybersecurity concerns around connected packaging, especially technologies that collect and transmit consumer interaction data, remain a persistent adoption barrier that brands and regulators are still working through.
Interoperability challenges across different smart packaging technology standards and platforms can also complicate adoption for brands operating across multiple markets with differing regulatory and infrastructure requirements.
Opportunities: Energy-Harvesting Technology and Software Ecosystem Integration Creating New Growth Avenues
Energy-harvesting inks and printed electronics represent a genuine growth opportunity, potentially eliminating the thin-film batteries that currently limit some smart packaging applications and opening up new form factors for intelligent labeling. Manufacturers who can commercialize this technology at scale stand to capture meaningful share as the category matures beyond battery-dependent designs.
Software ecosystem integration offers a second clear opportunity, as competitive pressure increasingly hinges on data platforms as much as physical material innovation, with some suppliers beginning to sell freshness data subscriptions alongside, or instead of, physical smart labels alone.
Recent Developments:
- 2025: AIPIA launched the Interactive Brand Packaging Network, positioning smart packaging as a strategic media channel for brand engagement.
- 2025: FreshInset reported that its Vidre+ active packaging complex extends cherry freshness by minimizing weight loss and preserving stem color in clamshell containers.
- 2025: Avery Dennison Corporation reported full-year 2024 sales of USD 8.8 billion across its labeling, RFID, and digital identification solutions business serving pharmaceuticals, logistics, and retail industries.
- 2025: Multisorb Technologies continued expanding its active packaging desiccant and oxygen-scavenger product lines to support pharmaceutical and food shelf-life extension applications.
Smart Packaging Market key players are:
- Amcor plc
- Sealed Air Corporation
- Avery Dennison Corporation
- 3M Company
- Ball Corporation
- Crown Holdings, Inc.
- BASF SE
- Multisorb Technologies
- Timestrip PLC
- Eastman Chemical Company
- Thin Film Electronics ASA
- Stora Enso Oyj
- Huhtamaki Oyj
- Tetra Pak International S.A.
- Smurfit Westrock plc
- CCL Industries Inc.
- Zebra Technologies Corporation
- Honeywell International Inc.
- NXP Semiconductors N.V.
- Impinj, Inc.
Smart Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 26.70 Billion |
| Market Size by 2035 | USD 44.70 Billion |
| CAGR | CAGR of 5.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Active Packaging, Intelligent Packaging, and Modified Atmosphere Packaging) • By Technology Type (RFID, QR Codes & Barcodes, NFC, and Sensors) • By End-Use Industry (Food & Beverage, Pharmaceuticals, E-commerce & Logistics, and Cosmetics) • By Level of Packaging (Primary Packaging, Secondary Packaging, and Tertiary Packaging) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Sealed Air Corporation, Avery Dennison Corporation, 3M Company, Ball Corporation, Crown Holdings, Inc., BASF SE, Multisorb Technologies, Timestrip PLC, Eastman Chemical Company, Thin Film Electronics ASA, Stora Enso Oyj, Huhtamaki Oyj, Tetra Pak International S.A., Smurfit Westrock plc, CCL Industries Inc., Zebra Technologies Corporation, Honeywell International Inc., NXP Semiconductors N.V., Impinj, Inc. |
Frequently Asked Questions
Key players include Amcor plc, Sealed Air Corporation, Avery Dennison Corporation, 3M Company, and Multisorb Technologies, alongside other established smart packaging technology manufacturers.
Key opportunities include energy-harvesting inks and printed electronics eliminating battery dependence, software ecosystem and data subscription integration, and expanding NFC-enabled consumer engagement applications.
The market is driven by escalating demand for product safety and supply chain transparency, tightening packaging waste and food safety regulation, and rising consumer expectation for interactive packaging experiences.
The Active Packaging segment dominated the Smart Packaging Market in 2025.
The North America region dominated the Smart Packaging Market in 2025, supported by a strong domestic focus on innovation and technology.
