
Solid State Battery Market Report Scope & Overview:
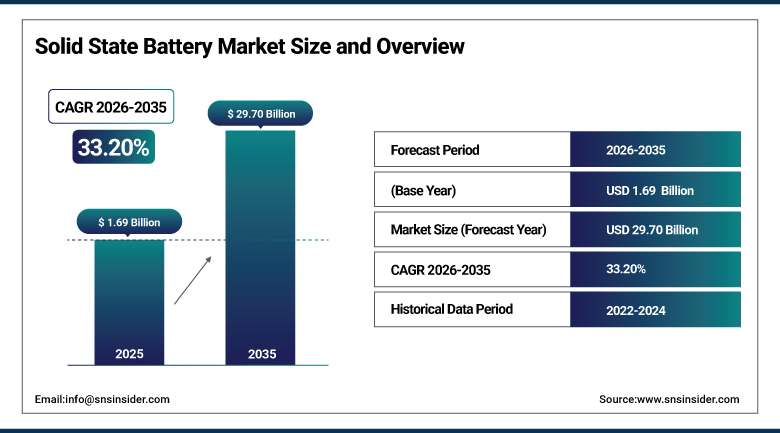
The Solid State Battery Market size was valued at USD 1.69 Billion in 2025 and is expected to reach USD 29.70 Billion by 2035, growing at a CAGR of 33.20% from 2026–2035.
The Solid State Battery Market is expected to register substantial growth as battery manufacturers transition from laboratory cell validation toward application-specific commercialization. Demand is supported by the need for higher energy density, improved thermal stability, and battery architectures with reduced reliance on flammable liquid electrolytes. Compact solid-state cells already serve sensors, industrial devices, and specialized mobility applications. Larger automotive cells remain at different stages of pilot production, qualification, and process scale-up. The competitive focus is shifting toward repeatable manufacturing yields, electrode-electrolyte interface stability, and cost-effective cell assembly. Investments in production equipment, intellectual property licensing, and strategic automotive partnerships are expected to create additional opportunities throughout the forecast period.
⮞In September 2026, ITEN announced that it had manufactured its one-millionth solid-state battery and expanded its Powency product family with a 1,500 µAh surface-mount device. The milestone highlights the commercial maturity of miniature solid-state cells relative to higher-capacity automotive programs.
To Get more information Solid State Battery Market - Request Free Sample Report
Solid State Battery Market Trends
-
Commercial activity is expanding from microbatteries toward qualified higher-capacity cells.
-
Automotive partners are increasing emphasis on pilot-line yields and vehicle-level validation.
-
Ceramic, polymer and sulfide electrolyte architectures are evolving for different performance targets.
-
Aerospace, medical technology, robotics and data-center applications are diversifying demand.
-
Cell developers are pursuing manufacturing partnerships and licensing to reduce scale-up risks.
US Solid State Battery Market Size Outlook
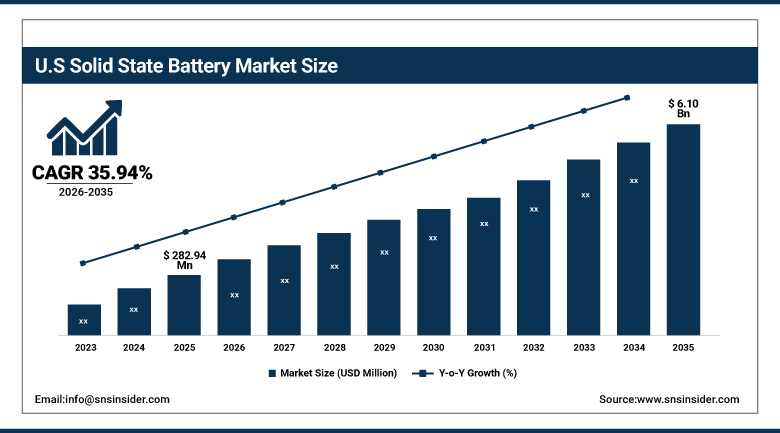
The US Solid State Battery Market was valued at USD 282.94 Million in 2025 and is projected to reach USD 6.10 Billion by 2035, expanding at a CAGR of 35.94% over 2026–2035. The estimated 2026 market size is USD 384.65 Million.
The U.S. Solid State Battery Market is gaining momentum from domestic development programs, specialist battery-cell companies, automotive validation initiatives, and emerging demand from aerospace and high-performance electronics. Commercial adoption remains uneven across applications, with microbatteries and specialized cells closer to sustained shipments than high-volume electric vehicle packs. Public and private investment is supporting pilot production, automated cell assembly, ceramic separator development, and manufacturing partnerships. Companies are also evaluating solid-state energy storage for data-center infrastructure and defense applications. However, manufacturing consistency, cost control, customer qualification, and reliable materials supply remain central to the commercialization outlook. Sustained growth will depend on translating laboratory performance into scalable and repeatable production.
⮞In October 2026, QuantumScape announced plans for a 100 MWh cell production line targeting data centers, aerospace, and defense, while continuing scale-up work at its San Jose pilot facility. The proposed capacity illustrates expanding U.S. commercialization pathways beyond passenger vehicles.
Solid State Battery Market Segment Analysis
-
By Battery Type, Thin Film Battery led the market with approximately 83.60% share in 2025, while Portable Battery is projected to grow at approximately 39.70% CAGR through 2035.
-
By Capacity, 20mAh-500mAh led the market with approximately 47.80% share in 2025, while Below 20mAh is projected to grow at approximately 37.90% CAGR through 2035.
-
By Application, Consumer & Portable Electronics led the market with approximately 39.40% share in 2025, while Electric Vehicles is projected to grow at approximately 43.90% CAGR through 2035.
-
By Rechargeability, Secondary Battery led the market with approximately 78.60% share in 2025, while Primary Battery is projected to grow at approximately 29.10% CAGR through 2035.
By Battery Type, Thin Film Battery Dominates the Market and Portable Battery Grows Fastest
Thin Film Battery accounted for the largest share of the Solid State Battery Market in 2025, reflecting relatively established opportunities in low-capacity electronics, distributed sensors, medical devices, and energy-harvesting applications. Thin-film configurations combine compact dimensions with stable cycling characteristics and design flexibility for products in which space is limited. Their commercial relevance also reflects the comparatively manageable qualification requirements of small-format battery systems. Device manufacturers prioritize thin profiles, dependable energy delivery, and product safety rather than maximum cell-level capacity. These attributes support adoption across embedded electronics and other markets where traditional cylindrical or pouch cells may be difficult to integrate.
Portable Battery is projected to record the fastest growth as cell developers target electric mobility, robotics, aerospace, and higher-energy stationary applications. Commercialization at these capacities requires considerably more demanding control over electrolyte interfaces, manufacturing pressure, cell stacking, and electrode uniformity. Automotive programs have therefore concentrated on prototype qualification and pilot-line optimization before committing to large-scale output. The commercial opportunity is significant because portable designs can address applications that require higher power and energy density than thin-film devices. Nevertheless, producers must demonstrate product durability and predictable yield at larger formats before the segment can reach broader deployment.
By Capacity, 20mAh-500mAh Dominates the Market and Below 20mAh Grows Fastest
The 20mAh-500mAh segment dominated the market in 2025 as this capacity range serves a wide installed base of compact industrial devices, healthcare electronics, sensors, and connected products. Manufacturers of these systems increasingly seek power sources that enable smaller enclosures without compromising operational reliability. Solid-state technology is particularly relevant where thermal stability, rechargeability, and long operating life influence device design. The segment benefits from repeatable manufacturing approaches developed for microelectronic components and small-format battery packaging. Suppliers compete through integration convenience, cycling characteristics, pulse-power capability, and product qualification for demanding end-use environments.
Below 20mAh is anticipated to expand at the highest rate because the proliferation of connected microdevices is encouraging further miniaturization. Smart labels, medical implants, authentication modules, and industrial monitoring nodes can require very small batteries with dependable storage performance. Improvements in surface-mount designs and solid-electrolyte processing support thinner and more compact configurations. The segment also benefits from manufacturing technologies that enable battery components to be integrated directly into electronic assemblies. Customer adoption will remain dependent on achievable power output, charging behavior, and device-specific validation, especially in medical electronics where qualification cycles can be lengthy.
By Application, Consumer & Portable Electronics Dominates the Market and Electric Vehicles Grows Fastest
Consumer & portable electronics held the largest share of applications in 2025, driven by the relatively mature demand for embedded sensors, wearable devices, tracking equipment and other space-constrained products. Solid-state cells can be tailored to specific size, safety, and operating profiles, creating opportunities for differentiated power solutions. The small electronics need less total energy than the electric cars, which makes them easier to commercialize, even with the current cost premium. Solid-state cells are also seen by device makers as a replacement where liquid-electrolyte leakage and thermal risks make packaging difficult. The demand for connected industrial and healthcare devices with long service life and minimal maintenance also supports the outlook.
Electric Vehicles is expected to post the fastest application growth as automakers pursue higher energy density, stronger safety performance, and potential reductions in charging time. Battery suppliers are testing cell chemistries and assembly methods intended for future vehicle platforms. However, automotive qualification demands consistent output across large production lots and dependable performance under varied temperatures, duty cycles, and crash conditions. Manufacturers that demonstrate stable interfaces and reliable mass-production processes will be positioned to benefit from commercial vehicle and passenger car programs. The segment also provides longer-term opportunities for dedicated cell manufacturing equipment and localized battery supply chains.
By Rechargeability, Secondary Battery Dominates the Market and Primary Battery Grows Fastest
The Secondary Battery segment is expected to dominate the market in terms of revenue share by 2025 owing to the rising demand for rechargeable energy storage from portable electronics, medical devices, industrial systems, and emerging electric mobility applications. Rechargeable formats are preferred where devices undergo repeated duty cycles and battery replacement is difficult or expensive. Solid state architectures can provide improved leakage resistance and greater design flexibility. The practical lifetime is a function of electrolyte chemistry and cell engineering. Technology developers are working on improving cycle life, reducing interfacial resistance, and stable repeated charging. These are especially important for high-utilization devices that need to deliver consistent power with minimal maintenance.
Primary Battery still has an important role in devices designed for single use operation or low energy long term service. Specialized sensing and monitoring applications where recharging infrastructure is not available or not required benefit the segment. There are advantages to solid-state formulations in some constrained environments, both in packaging and in operation. However, the lack of rechargeability limits their suitability for high-demand mobility and regularly used electronic platforms. Suppliers are likely to focus on applications where shelf life, miniaturization, storage stability and secure containment are more important than repeated cycling. So primary configurations will be part of the application specific segment of the market rather than the primary driver of the forecast growth.
Regional Analysis
|
Region |
2025 Global Share |
2025 Regional Revenue (USD Million) |
Regional CAGR (2026–2035) |
|---|---|---|---|
|
Asia Pacific |
53.70% |
907.24 |
32.70% |
|
North America |
20.30% |
342.96 |
35.70% |
|
Europe |
18.10% |
305.79 |
33.30% |
|
Latin America |
4.60% |
77.72 |
34.80% |
|
Middle East & Africa |
3.30% |
55.75 |
34.20% |
Asia Pacific Solid State Battery Market Insights
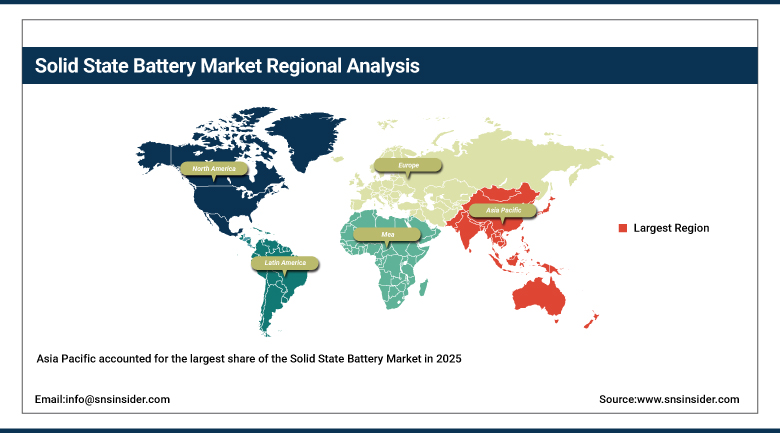
Asia Pacific accounted for the largest share of the Solid State Battery Market in 2025, supported by its concentration of advanced battery manufacturing capacity, electronics supply chains, and automotive development programs. Japan, South Korea, China, and Taiwan remain important centers for research, pilot manufacturing, and specialist cell commercialization. Regional strengths are mature equipment suppliers, precise materials processing and close cooperation between battery developers and downstream electronics manufacturers. Experience with high-volume manufacturing of conventional batteries can help in scaling up solid-state processes in the future but it will not automatically translate. The area also benefits from domestic industrial strategies that target advanced energy storage technologies.
The competition in Asia Pacific is increasingly focused on proprietary solid electrolytes, dry processing, production yields and cell formats suitable for automotive or microelectronic applications. Big manufacturers are building development capabilities, smaller specialists are focusing on product differentiation.
⮞In September 2026, ProLogium announced it will start mass production of its Gen 3.5 lithium ceramic battery technology from its Taiwan manufacturing site, backed by independent energy-density testing. The development illustrates how scaled product output is emerging alongside continuing work on next-generation electrolyte systems. Long-term regional growth will depend on qualification timelines and commercially competitive battery economics.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Solid State Battery Market Insights
North America represented approximately 20.30% of global revenue in 2025 and is forecast to record the fastest regional CAGR of approximately 35.70% through 2035. The U.S. remains the region’s principal innovation and commercialization market. Solid-state battery developers are advancing ceramic separators, anode-free cell formats, sulfide electrolytes, and scalable battery assembly processes. Aerospace, defense, electric vehicles, and electronics provide diverse routes to customer qualification. The regional opportunity is strengthened by technical partnerships with established manufacturers and by efforts to expand domestic advanced-battery production capacity.
Pilot facilities and commercialization agreements are becoming increasingly important differentiators in North America. Developers must demonstrate not only strong electrochemical performance but also predictable throughput, component availability, and production cost.
⮞In June 2026, Factorial and Stellantis announced the start of road testing and integration of solid-state cells into a North American development vehicle. This kind of validation at the platform level underpins the future demand, dealing with system integration and real world operating requirements. Nevertheless, regional growth projections remain sensitive to automotive adoption schedules, factory execution, and access to specialized equipment.
Europe Solid State Battery Market Insights
Europe held a significant share in the Solid State Battery Market in 2025, owing to sophisticated battery engineering, electrification strategies, and existing demand for specialty energy storage. France, Germany and the United Kingdom are important centers for cell development, manufacturing partnerships and research programs. European suppliers have been particularly active in lithium-metal polymer batteries, thin-film devices and battery solutions for industrial or medical electronics. Car-makers are looking into solid-state designs as a means to make future cars safer and more efficient. Policy attention to battery supply resilience is supporting investment in localized facilities, but financing and customer qualification remain material constraints.
The regional competitive landscape includes both commercially experienced battery producers and emerging technology developers. Companies are working to improve electrolyte processing, electrode performance, and integration with existing manufacturing systems.
⮞In May 2026, Blue Solutions and AVL reported completion of a battery-safety evaluation program covering next-generation solid-state cells and industrial scale-up considerations. Such collaborations are important because cell chemistry must ultimately be validated at the pack and vehicle level. Europe is projected to register continued expansion as pilot-line development and specialty demand progress toward broader industrial deployment.
Latin America Solid State Battery Market Insights
Latin America accounted for a smaller share of 2025 market revenue, reflecting more limited domestic solid-state cell manufacturing compared with Asia Pacific, North America, and Europe. Market opportunities are concentrated in imported electronic devices, industrial monitoring systems, specialized mobility applications, and selected renewable-energy projects. Brazil and Mexico are potential early demand centers because of their electronics, automotive, and industrial manufacturing bases. The region’s growth will rely heavily on the availability of qualified products and the ability of suppliers to serve customers through regional distribution and integration networks.
Solid-state battery adoption in Latin America will likely increase as manufacturers become more confident in cell reliability and lifetime economics. If global vehicle programs start to include high-capacity solid-state cells on a commercial scale, the demand from automotive production chains could become more significant. Until then, portable electronics and industrial sensing are likely to provide more accessible opportunities. Product pricing, service support, imported component availability, and battery certification requirements will influence the pace of expansion. Regional growth is therefore expected to develop from a small base and may fluctuate with the timing of major commercial programs.
Middle East & Africa Solid State Battery Market Insights
Middle East & Africa represented a relatively small portion of the Solid State Battery Market in 2025. Demand is associated with industrial monitoring, defense electronics, specialized transportation, remote sensing, and emerging energy storage applications. The Gulf countries are investing in advanced industrial and technology infrastructure, while South Africa and other markets present selective demand from transport and distributed energy systems. Adoption remains at an early stage, and widespread manufacturing of solid-state battery cells is not yet established across the region. Imported specialty batteries are therefore likely to account for a substantial proportion of near-term sales.
Opportunities may broaden as cell suppliers target operating environments where safety and durability are especially important. Potential use cases include high-temperature industrial environments, remote equipment, and high-reliability electronics, but performance requirements vary materially by application. Procurement decisions will be based on proven field reliability and total cost, not just claimed laboratory energy density. Industrial customers are likely to favor suppliers who can offer application engineering and robust qualification support. Long-term regional growth will continue to be driven by the pace of infrastructure electrification, better product availability and lower costs.
Market Dynamics
Growth Drivers: Increasing Demand for Safer, Higher-Energy-Density Batteries
Electric mobility, connected electronics and sophisticated industrial systems are placing increasing strain on the usable energy available in restricted space and weight. Solid-state cell architectures can reduce the exposure to volatile liquid electrolyte components and offer additional options for battery packaging. The potential for improving safety and energy density has led automakers and electronics manufacturers to invest in qualification programs. However, the observed benefits are dependent on the electrolyte chemistry, cell design and operating conditions. Product developers are increasingly focused on demonstrating improvements at cell and system level rather than relying on isolated material-level performance claims.
The expanding number of battery-powered connected devices creates near-term demand for microbatteries and thin-film cells. These applications may commercialize sooner because their capacity requirements and mechanical constraints are more manageable than those of passenger vehicles. At the same time, automotive suppliers are developing high-capacity cell formats for future platforms.
⮞In March 2026, Samsung SDI publicly introduced a pouch-type all-solid-state battery sample for robotics while continuing development of prismatic technology for electric vehicles. The company’s activities illustrate growing application diversification and the importance of tailoring cell design to specific power requirements.
Restraints: Manufacturing Complexity and High Commercialization Costs
The biggest challenge in the Solid State Battery Market is to translate promising electrochemical performance into a stable, scalable production process. Solid electrolytes can have difficult interfacial contacts, mechanical stresses, moisture sensitivity and/or special temperature or pressure requirements. High-capacity cells must be reliable over many layers and demanding automotive operating cycles. These increase the cost of qualification and can restrict yield during pilot manufacturing. Some solid-state architectures are likely compatible with existing lithium-ion battery manufacturing plants, but large-scale commercialization will often require new equipment, process control, and materials handling capabilities.
The cost penalty of early solid-state products is still substantial, particularly where manufacturers are not yet in a position to spread engineering and capital expenditure over high production volumes. Battery developers need to invest in test equipment, safety characterization, automation and customer validation before demand can be predicted.
⮞Solid Power, February 2026, announced continued work on a continuous sulfide-electrolyte pilot line installation and progress on a partner pilot-cell line. These efforts show that industrial readiness is as much about production processes as it is about lab chemistry. End user interest is increasing, but market adoption may be slow due to delays in customer qualification or material scale-up.
Opportunities: Automotive Programs and Specialized High-Reliability Applications
The market offers opportunities across automotive electrification, aerospace, robotics, medical devices, and industrial IoT, although commercialization requirements differ considerably. Specialty applications value compact dimensions, thermal stability, and predictable operating performance and can support relatively small production volumes. Electric vehicles provide a much larger long-term addressable application if manufacturers meet targets for safety, cell lifetime, cost, and manufacturing yield. Partnerships among cell developers, automobile companies and equipment suppliers are essential as system level validation is done at different development stages. Successful programs may generate requirements for licensing, cell manufacturing, and integrated battery systems.
Application-specific engineering will likely be a big competitive advantage. Some developers work on ceramic electrolyte structures, others develop polymer or sulfide systems, and there is no one configuration that is best for every end use.
⮞In May 2026, Panasonic Energy announced a phased commercialization strategy for all-solid-state batteries, with plans for sample shipments in fiscal 2026. The approach emphasizes the merit of working up through manageable cell formats before attempting large scale deployment. New demand from data-center infrastructure and autonomous systems may further diversify revenue opportunities beyond conventional passenger-vehicle programs.
Competitive Landscape
The Solid State Battery Market includes companies shipping specialized solid-state cells and manufacturers developing higher-capacity products at pilot or qualification stage. Commercial positions vary substantially across applications. Thin-film and polymer-based systems have established use cases, while several automotive battery technologies remain under validation. Competitive differentiation is shaped by electrolyte chemistry, manufacturing yield, product safety, customer qualification, and the ability to move from prototype output to repeatable commercial production. Direct participants include dedicated cell developers, established battery manufacturers, and vehicle producers operating in-house solid-state battery programs. The companies listed below have identifiable solid-state battery cell or product development activity.
Key Solid State Battery Companies:
-
Solid Power, Inc.
-
Factorial Energy Inc.
-
ProLogium Technology Co., Ltd.
-
Blue Solutions
-
Ilika plc
-
ITEN
-
Samsung SDI Co., Ltd.
-
Panasonic Energy Co., Ltd.
-
LG Energy Solution, Ltd.
-
Toyota Motor Corporation
-
Honda Motor Co., Ltd.
-
Nissan Motor Co., Ltd.
-
Suzuki Motor Corporation
Recent Developments:
-
In October 2026, QuantumScape outlined a proposed 100 MWh solid-state battery cell line with an automation partner to support potential demand from AI data centers, aerospace and defense. This is a scheduled industrial scale-up and should not be confused with commissioned commercial capacity.
-
In September 2026, ITEN unveiled the manufacture of one million solid-state batteries, and launched a higher-capacity surface-mount device for compact electronics. "The announcement is a positive for specialized battery products with proven manufacturing experience.
-
In July 2026, Suzuki Motor Corporation acquired Kanadevia's all-solid-state lithium-ion battery business, including its technology development, design and sales capabilities, completing the planned acquisition period. The business transfer brings a proven specialist product portfolio into new hands.
-
In June 2026, Factorial announced that its battery cells had been integrated into a Stellantis development car for road trials. The effort advances assessment of cell performance and reliability at the system level under actual operating conditions.
Solid State Battery Market Report Scope
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.69 Billion |
| Market Size by 2035 | USD 29.70 Billion |
| CAGR | CAGR of 33.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Battery Type (Thin Film Battery and Portable Battery) • By Capacity (Below 20mAh, 20mAh-500mAh and Above 500mAh) • By Application (Consumer & Portable Electronics, Electric Vehicles, Energy Harvesting, Wearable & Medical Devices and Others) • By Rechargeability (Primary Battery and Secondary Battery) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | QuantumScape Corporation, Solid Power, Inc., Factorial Energy Inc., ProLogium Technology Co., Ltd., Blue Solutions, Ilika plc, ION Storage Systems, Inc., ITEN, Samsung SDI Co., Ltd., Panasonic Energy Co., Ltd., LG Energy Solution, Ltd., Toyota Motor Corporation, Honda Motor Co., Ltd., Nissan Motor Co., Ltd., Suzuki Motor Corporation. |

Frequently Asked Questions
Direct market participants include QuantumScape, Solid Power, Factorial, ProLogium, Blue Solutions, Ilika, ION Storage Systems, ITEN, Samsung SDI, and other battery developers with active solid-state cell programs.
Asia Pacific accounted for approximately 53.70% of global revenue in 2025.
Thin Film Battery led the Battery Type segment with approximately 83.60% of 2025 revenue.
The market is projected to expand at a CAGR of 33.20% from 2026–2035.
The global market was valued at USD 1.69 Billion in 2025 and is projected to reach USD 29.70 Billion by 2035.
