
Teledentistry Market Report Scope & Overview:
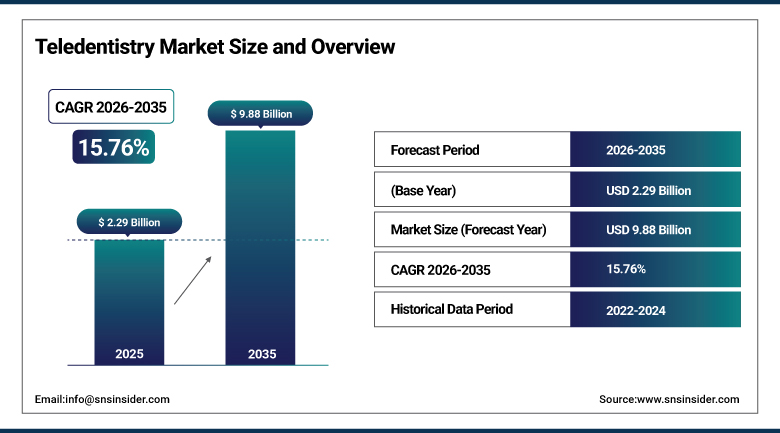
The Teledentistry Market size was valued at USD 2.29 Billion in 2025 and is expected to reach USD 2.65 Billion in 2026, increasing to USD 9.88 Billion by 2035. The market is projected to expand at a CAGR of 15.76% during 2026–2035. Teledentistry connects patients and dental professionals through video consultations, photo and radiograph sharing, and remote monitoring software. Adoption is rising as dental practices, employers, insurers and public health programs look for ways to reach patients who live far from a dentist, shorten waiting times and lower the cost of routine follow-up care.
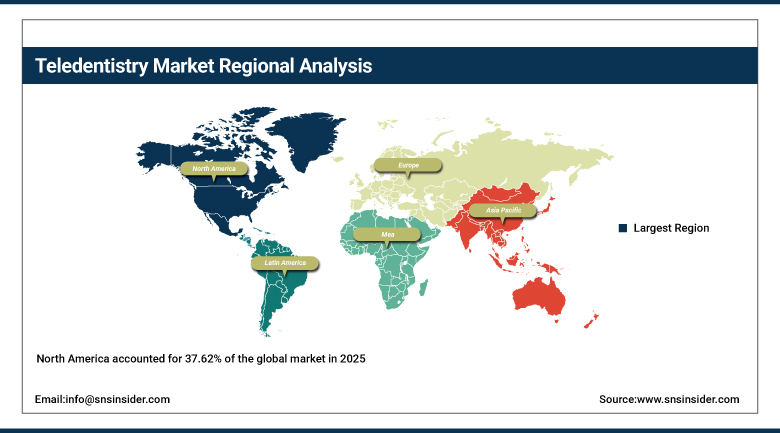
North America accounted for the largest share of the market, at 37.62% in 2025, supported by broad broadband access, a large base of dental practices that already use digital imaging, and growing coverage of virtual visits by employers and health plans. Asia Pacific is the second largest region and the fastest growing one, helped by rising smartphone use and public programs that extend oral health services to rural communities. Europe holds the third position, while Latin America and Middle East and Africa are building from smaller bases. These patterns are expected to hold through the forecast period.
To Get more information Teledentistry Market - Request Free Sample Report
Key Report Takeaways
-
By component, software held a 46.38% share in 2025, while hardware is the fastest growing.
-
By delivery mode, web-based solutions held a 54.12% share in 2025, while cloud-based solutions are the fastest growing.
-
By application, teleconsultation held a 49.67% share in 2025, while remote patient monitoring is the fastest growing.
-
By end use, dental clinics held a 58.43% share in 2025, while homecare settings are the fastest growing.
-
By region, North America held a 37.62% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Hybrid care models are becoming the standard way to deliver teledentistry. Dental practices use virtual triage to screen symptoms, review patient photos and decide whether a visit is needed, which frees chair time for procedures. Patients who need only a follow-up, a prescription review or a second opinion can be handled remotely, and group practices use this approach to manage demand without adding clinical space.
Artificial intelligence is changing how remote images are read. Software now flags early signs of decay, gum disease and tooth movement from smartphone photos and intraoral scans, which supports faster decisions by the reviewing dentist. Integration with practice management and health record systems is also improving, so remote findings flow directly into the patient file and virtual visits become easier to bill and track.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising oral disease burden and dentist shortages in underserved areas |
+4.52% |
Global, strongest in Asia Pacific and Latin America |
Long term (4 years or more) |
|
Wider broadband, smartphone and intraoral camera use |
+4.08% |
Global, led by North America and Asia Pacific |
Medium term (2 to 4 years) |
|
Artificial intelligence in diagnostics and remote monitoring |
+3.57% |
North America, Europe and Asia Pacific |
Medium term (2 to 4 years) |
|
Policy support, insurance coverage and employer benefits |
+2.91% |
North America and Europe |
Short term (2 years or less) |
|
Patient demand for convenient and lower-cost care |
+2.26% |
Global |
Short term (2 years or less) |
Rising Burden of Oral Disease and Shortage of Dentists in Underserved Areas
Oral disease affects a large share of the global population, and most cases go untreated because patients cannot reach a dentist. WHO reported in November 2022 that oral diseases affect close to 3.50 billion people worldwide. Rural communities, nursing homes and low-income neighborhoods often lack a nearby provider, so a short virtual visit can be the first point of contact. Teledentistry lets one dentist screen many patients across a wide area, direct urgent cases to treatment and keep minor problems from becoming emergencies. Community health workers and school programs also use remote screening to identify children who need treatment sooner.
Wider Broadband, Smartphone and Intraoral Camera Use
Faster internet and low-cost devices have removed the main technical barriers to remote dental care. Most patients now carry a smartphone that can capture usable photos, and compact intraoral cameras let clinics or community workers record clear images of the mouth. Video platforms built for health care meet privacy requirements and run on ordinary browsers, which keeps setup simple for small practices. Better connectivity in schools, workplaces and care homes also makes it easier to hold consultations where patients already are. As network coverage keeps improving, even small practices can offer reliable video visits at a low cost.
Artificial Intelligence in Diagnostics and Remote Monitoring
Image analysis software can detect early decay, bone loss and aligner tracking problems from patient submitted photos, which makes remote review faster and more consistent. Orthodontic practices use scan-based monitoring to follow treatment between visits, cutting the number of in-person checks. Dentists can review a larger caseload in less time, and patients receive quicker answers. As regulatory clearances expand for these tools, practices gain confidence to build them into daily workflows and to bill for the time saved. Vendors are also training algorithms on larger image sets, which steadily raises accuracy.
Policy Support, Insurance Coverage and Employer Benefits
Governments and payers are widening the list of services that can be delivered remotely. The Global Oral Health Action Plan 2023–2030, endorsed by the World Health Assembly, asks member countries to integrate oral health into primary care and to use digital tools to improve access. Insurers and employers are also adding virtual dental visits to benefit plans because they lower emergency room use and reduce claim costs. Clearer billing codes give practices a reason to invest in the technology. Public programs in several countries now fund virtual screening for children and older adults.
Patient Demand for Convenient and Lower-Cost Care
Patients value the ability to book an evening consultation, avoid travel and obtain advice without taking time off work. Dental anxiety also keeps many people away from the clinic, and a first conversation by video can be less stressful. Subscription and flat-fee virtual visit models give uninsured patients a predictable price for urgent questions. Families, older adults and caregivers who find travel difficult are among the groups using remote follow-up most often, which supports steady growth in visit volumes. Short wait times and flexible hours add to the appeal of this care model.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Licensure and regulatory differences across jurisdictions |
-0.71% |
North America and Europe |
Medium term (2 to 4 years) |
|
Limited and uneven reimbursement |
-0.46% |
Global, strongest in Latin America and Middle East and Africa |
Short term (2 years or less) |
|
Digital divide and limits of remote examination |
-0.24% |
Asia Pacific, Latin America and Middle East and Africa |
Long term (4 years or more) |
|
Data privacy and cybersecurity risks |
-0.17% |
North America and Europe |
Medium term (2 to 4 years) |
Licensure and Regulatory Differences Across Jurisdictions
Rules on who may deliver teledentistry, what must be documented and whether a prior in-person exam is required differ from one state or country to another. Providers that operate across several jurisdictions must track each rule set and adjust consent, prescribing and supervision practices accordingly. Rules on artificial intelligence are also emerging, as seen in October 2026 when the Idaho Board of Dentistry adopted a policy on its use in clinical practice. These differences raise compliance costs and slow national rollouts.
Limited and Uneven Reimbursement
Coverage for virtual dental services remains inconsistent. Some payers cover only specific visit types, pay at lower rates than office visits or require the patient to be in a particular setting. Many dental plans have annual maximums that discourage extra consultations. Practices that cannot recover the cost of software, training and clinician time may postpone adoption. Until coverage rules become consistent and payment levels are predictable, a share of dentists will keep virtual care as a small side service instead of a core offering.
Digital Divide and Limits of Remote Examination
The patients who gain the most from remote care are often those with weak internet access, older devices or limited digital skills. Image quality from low-end phones can also reduce diagnostic confidence. In addition, dentistry depends on hands-on procedures such as fillings, extractions and scaling, which cannot be delivered virtually, so remote visits mainly support triage, review and follow-up. These limits narrow the range of cases that teledentistry can resolve without a clinic visit. Rural and low-income patients are the most affected by these gaps.
Data Privacy and Cybersecurity Risks
Teledentistry platforms store images, clinical notes and payment details, which makes them targets for cyber attacks. Practices must comply with health privacy laws such as HIPAA in the United States and GDPR in Europe, and breaches can lead to penalties and loss of patient trust. Smaller clinics often lack in-house security staff, so they depend on vendors for encryption and access controls. Concern over data handling can slow adoption, especially for cloud-based tools that share images across organizations. Vendor audits and staff training add further cost for smaller practices.
Teledentistry Segment Analysis
By Component, Software Dominates Teledentistry Market; Hardware to Register Fastest Growth.
Software dominates the component axis, with a 46.38% share in 2025. Platforms for video visits, secure image exchange, scheduling, consent capture and charting form the core of any virtual care program, and practices can adopt them with a modest subscription and little capital spending. Software also connects directly to practice management systems, which keeps records in one place. Frequent feature updates, including automated reminders and billing tools, give practices a steady reason to stay on one platform for years.
Hardware is expected to register the fastest growth, at a CAGR of 16.38% during 2026–2035. Intraoral cameras, smartphone-linked scanners, wireless imaging sensors and at-home scan kits are becoming cheaper and easier to use, so patients and community health workers can capture clinical quality images without a dentist present. Orthodontic monitoring programs and school screening projects are driving device purchases. Better image quality also raises diagnostic confidence. Hardware sales also benefit from public programs that supply devices to community clinics.
By Delivery Mode, Web-Based Dominates Teledentistry Market; Cloud-Based to Register Fastest Growth.
Web-based delivery leads the delivery mode axis, holding 54.12% of the market in 2025. Patients and dentists can join a consultation through a standard browser without installing special programs, which suits first-time users and older adults. Practices avoid hardware maintenance and can launch a service within days. Browser access also works across phones, tablets and clinic computers, so a single link supports many settings. Simple onboarding and low support needs explain why most providers start with this format.
Cloud-based delivery is projected to grow fastest, at a CAGR of 16.12% over 2026–2035. Cloud platforms scale easily, store large imaging files securely and allow artificial intelligence tools to be added without changes at the clinic. Multi-location groups and dental service organizations favor them because administrators can manage users, templates and reports centrally. Built-in encryption, automatic backups and software updates reduce the burden on small teams, and subscription pricing makes costs easier to plan. This model suits growing groups.
By Application, Teleconsultation Dominates Teledentistry Market; Remote Patient Monitoring to Register Fastest Growth.
Teleconsultation is the leading application, with a 49.67% share in 2025. Live video and photo-based consultations cover the most common reasons for contacting a dentist, including tooth pain, swelling, broken restorations and questions about treatment plans. They also provide second opinions and pre-visit screening. Dentists can decide quickly whether a patient needs urgent care, a routine visit or reassurance, which saves time for both sides. Demand is steady because these visits are short, low-cost and simple to schedule.
Remote patient monitoring is set to grow fastest, at a CAGR of 17.04% from 2026 to 2035. Orthodontic treatment is the main use, as patients scan their teeth at home and software tracks tooth movement between appointments. Monitoring is spreading to implant healing, periodontal maintenance and post-surgical checks. Fewer in-person visits lower costs for practices and reduce travel for patients, while early alerts help dentists correct problems sooner. Wider approval of artificial intelligence image tools supports this expansion.
By End Use, Dental Clinics Dominate Teledentistry Market; Homecare Settings to Register Fastest Growth.
Dental clinics are the dominant end users, representing 58.43% of the market in 2025. Clinics already hold the patient relationships, imaging equipment and clinical staff needed to run virtual follow-up, screening and triage. Offering remote options helps them keep existing patients engaged between visits and attract new ones from nearby areas. Integration with in-house records and billing systems lowers the effort of adoption. Many clinics also use virtual visits to manage cancellations and to review cases before booking longer appointments.
Homecare settings are expected to register the fastest growth, at a CAGR of 16.71% during 2026–2035. Patients increasingly use at-home scan kits, mobile apps and direct-to-consumer virtual visit services without going to a clinic. Older adults, people with limited mobility and families in remote areas benefit most. Employers and insurers also encourage at-home use because it lowers the cost per interaction. Simpler devices and clear guided instructions make home use reliable enough to support a wider range of care.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.47% |
|
Europe |
Germany |
24.18% |
|
Asia Pacific |
China |
41.36% |
|
Middle East and Africa |
Saudi Arabia |
33.95% |
|
Latin America |
Brazil |
46.52% |
North America Teledentistry Market
North America accounted for 37.62% of the global market in 2025, the largest share among all regions. Wide broadband coverage, a large base of digitally equipped dental practices and employer-sponsored benefit plans support steady use. Access gaps also matter, since HRSA data for 2025 show more than 7,000 designated dental health professional shortage areas across the United States, where virtual visits help bridge the distance to a dentist. Telehealth-friendly payment policies in several states add further momentum for dental practices.
The United States market was valued at USD 709.67 Million in 2025 and is expected to register a CAGR of 15.43% during 2026–2035. State laws continue to widen the settings in which virtual dental services can be delivered, and public health programs use them in schools and long-term care facilities. Canada is also seeing steady uptake, mostly through private virtual care providers and employer plans that include remote consultation. Large dental service organizations are rolling out virtual triage across entire networks.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Teledentistry Market
Asia Pacific is the fastest growing region, with a projected CAGR of 16.19% over 2026–2035, and it held 27.84% of the market in 2025. Large rural populations, rising smartphone use and a shortage of dentists outside major cities create strong demand for remote consultation. China leads the region, where internet hospital platforms allow patients to book dental advice online and large private clinic groups are adding virtual triage. Online booking and payment tools make it easy for patients to consult a dentist from home.
Japan is advancing remote care to serve its aging population, which raises the need for home-based and nursing facility oral care. India, Australia and South Korea are adding teledentistry through mobile apps and public programs. Government investment in digital health infrastructure and the spread of private clinic chains are expected to keep regional growth above the global rate. Growing awareness of preventive oral care among younger urban consumers also supports demand for subscription-based consultation and monitoring services. Local device makers are lowering prices.
Europe Teledentistry Market
Europe held 21.37% of the market in 2025. Public health systems and statutory insurers are gradually recognizing remote consultation, and national digital health strategies encourage secure data exchange. Germany leads the region, supported by an advanced framework for digital health applications and a large network of private dental practices that are comfortable with new technology. Cross-border initiatives on electronic health records are helping practices share images and notes securely, and rising interest in preventive care is encouraging patients to use virtual check-ins between visits.
The United Kingdom, France and the Nordic countries are using virtual triage to shorten waiting lists, and teledentistry is used to reach care homes and remote island communities. Strict privacy rules under GDPR shape platform design and favor vendors with strong compliance records. Growth is steady rather than rapid, since reimbursement rules remain different in each country. Dental groups in Spain and Italy are also adopting remote monitoring for orthodontic patients, which lowers the number of visits needed during treatment.
Latin America Teledentistry Market
Latin America accounted for 7.46% of the market in 2025. Large distances between cities and rural areas, together with an uneven supply of dentists, make remote consultation attractive. Brazil leads the region, where the Federal Council of Dentistry has allowed teleconsultation since 2020, and large private clinic networks and insurers are adding virtual triage to their services. Public health systems in the region are also exploring digital tools to extend preventive oral care to remote communities, which supports a gradual rise in demand over the forecast period.
Mexico is expanding private virtual care services and mobile dental programs, while Argentina, Chile and Colombia are testing remote screening in public clinics. Smartphone use is high across the region, which supports photo-based consultations. Limited insurance coverage and income gaps restrict growth, so most demand comes from urban middle-income patients who prefer lower-cost options. Partnerships between telecom operators, insurers and clinics are expected to lower access costs and expand the patient base over time. Digital payment options are also helping.
Middle East and Africa Teledentistry Market
Middle East and Africa held 5.71% of the market in 2025. Saudi Arabia leads the region, where the Seha Virtual Hospital model and Vision 2030 digital health goals support remote specialist access, including oral care. Gulf countries invest in connected health infrastructure and have a young, mobile-first population that readily uses consultation apps. Private hospital groups in the United Arab Emirates and Qatar are also introducing virtual dental consultations as part of wider digital patient services, which broadens access for residents and visitors.
In Africa, mobile networks are the main route to care, and community health programs are testing photo-based screening to reach villages without a dentist. South Africa and Kenya are among the more active markets. Funding limits, uneven connectivity and a shortage of trained staff slow progress, but donor and public programs are expected to widen access gradually through 2035. Telecom partnerships and low-cost devices are expected to improve reach, particularly in urban centers where demand is concentrating. Training programs for local dentists support this effort.
Competitive Landscape
The Teledentistry Market is fragmented, with a mix of orthodontic monitoring specialists, virtual care providers, software vendors and clear aligner companies. Competition centers on platform reliability, integration with practice management systems, image analysis accuracy and pricing. Few companies hold a large share, so partnerships with insurers, employers and dental service organizations are an important route to growth.
Companies are investing in artificial intelligence, expanding into new countries and bundling hardware, software and clinical services into single subscriptions. Smaller vendors compete by serving specific needs, such as school screening, mobile dentistry or emergency consultations. Over the forecast period, scale in data, regulatory approvals and partnerships is expected to separate leading platforms from the rest.
Teledentistry Industry Leaders
3. MouthWatch, LLC
4. Teledentistry.com
5. Candid Care Co.
Companies Covered in this Report
-
Align Technology, Inc.
-
Candid Care Co.
-
DentalMonitoring
-
MouthWatch, LLC
-
Teledentistry.com
-
The TeleDentists
-
Virtudent, Inc.
Recent Industry Developments
-
August 2025: MouthWatch opened nominations for the eighth annual Teledentistry Innovation Awards.
-
January 2026: OrisDX added its saliva-based oral cancer test to the virtual care platform of Teledentistry.com.
-
February 2026: DentalMonitoring secured growth funding to expand its AI remote orthodontic monitoring platform across Europe, the United States, Australia and Japan.
-
March 2026: The TeleDentists became a virtual dental care provider on the Zocdoc marketplace.
-
October 2026: QC Healthcare partnered with Teledentistry.com to offer integrated medical and dental telehealth in the United States, Puerto Rico and Guam.
-
October 2026: Videa expanded its dental AI imaging platform into Canada through a partnership with ClearDent.
Scope and Research Methodology
This study estimates the Teledentistry Market for 2025 as the base year and forecasts it through 2035. The scope covers software, hardware and services used to deliver dental consultation, diagnosis, monitoring and education at a distance, measured as revenue in USD at the point of sale to dental practices, health systems, employers and consumers. Services that only schedule in-person appointments, and conventional dental equipment with no remote function, fall outside the scope. Both public and private care settings are included, and both direct-to-consumer and clinician-led services are counted. Revenues are reported on a calendar year basis and exclude one-time implementation fees.
Research began with desk analysis of regulatory filings, health ministry and professional association publications, company reports, product documentation and trade literature. Market size was built from the bottom up using the number of connected dental practices, visit volumes, platform subscription levels and device shipments, and was cross-checked from the top down using dental care spending and digital health adoption. Segment and regional shares were assigned from adoption patterns, pricing and product mix in each region. Pricing for each product class was examined across regions to convert unit and subscription counts into revenue.
Findings were tested through discussions with dental practitioners, platform vendors, device makers and healthcare administrators, and the forecast model was run under base, optimistic and conservative adoption cases. Growth rates reflect expected changes in reimbursement, regulation, technology cost and patient behavior. Segment growth rates were set in relation to the overall market trajectory so that the parts remain consistent with the whole. All values are expressed in USD, rounded to two decimals, and the forecast is reviewed periodically as new information becomes available. Regional models consider income levels, broadband coverage and the density of dentists to adjust expected adoption. Assumptions were revisited whenever regulatory or technology developments changed the outlook.
Teledentistry Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.29 Billion |
| Market Size by 2035 | USD 9.88 Billion |
| CAGR | CAGR of 15.76% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Hardware, and Services) • By Delivery Mode (Web-Based, Cloud-Based, and On-Premise) • By Application (Teleconsultation, Remote Patient Monitoring, Tele-Education and Training, and Others) • By End Use (Dental Clinics, Hospitals, Dental Service Organizations, and Homecare Settings) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Align Technology, Inc., Candid Care Co., DentalMonitoring, MouthWatch, LLC, Teledentistry.com, The TeleDentists, Virtudent, Inc. |

Frequently Asked Questions
The market was valued at USD 2.29 Billion in 2025 and is expected to reach USD 2.65 Billion in 2026 and USD 9.88 Billion by 2035.
The market is projected to grow at a CAGR of 15.76% during 2026–2035.
North America leads, with a 37.62% share in 2025, supported by broadband access, digitally equipped practices and employer benefits.
Asia Pacific is expected to grow fastest, at a CAGR of 16.19% during 2026–2035, led by China.
Software, web-based delivery, teleconsultation and dental clinics lead, while hardware, cloud-based delivery, remote patient monitoring and homecare settings are the fastest growing.
Oral disease burden, dentist shortages in underserved areas, wider device and broadband use, artificial intelligence tools and employer and insurer coverage.
Differences in licensure rules, uneven reimbursement, the digital divide and data privacy risks limit faster adoption.
