
Thermal Transfer Tapes Market Report Scope & Overview:
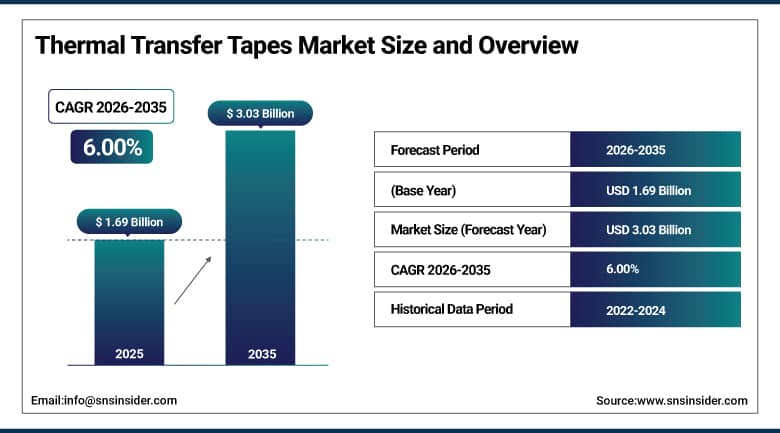
The Thermal Transfer Tapes Market was valued at USD 1.69 Billion in 2025 and is expected to reach USD 3.03 Billion by 2035, growing at a CAGR of 6.00% from 2026 to 2035.
The thermal transfer tapes market covers a genuinely unglamorous but consequential category, adhesive tapes engineered to bond, mask, or transfer material under heat with a reliability that ordinary pressure-sensitive tapes simply cannot match. These tapes now represent over 28% of industrial adhesive usage, spanning applications from splicing and electronics assembly to the label printing that keeps warehouse and retail barcode systems running. What is reshaping the category right now is the sheer diversity of end markets pulling on it simultaneously, electric vehicle battery thermal management, high-voltage electronics assembly, and medical device manufacturing all now depend on thermal transfer tape performance that traditional automotive and industrial applications never required.
In March 2024, 3M Company launched a new series of thermal management tapes specifically designed for high-voltage electric vehicle batteries, aiming to improve energy efficiency and battery lifespan.
To Get More Information On Thermal Transfer Tapes Market - Request Free Sample Report
Thermal Transfer Tapes Market Trends
-
Polyimide substrates are gaining share for aerospace and electronics applications requiring exceptional thermal stability and chemical resistance.
-
Electric vehicle battery thermal management is emerging as a significant new demand category beyond traditional label printing applications.
-
Silicone adhesive formulations are expanding as high-temperature-resistant bonding requirements grow across automotive and electronics manufacturing.
-
Sustainable and eco-friendly tape formulations are becoming a standard specification rather than a premium differentiator.
-
Regional manufacturing capacity expansion is accelerating as suppliers seek to serve EV and electronics customers closer to production hubs.
The U.S. Thermal Transfer Tapes Market Outlook
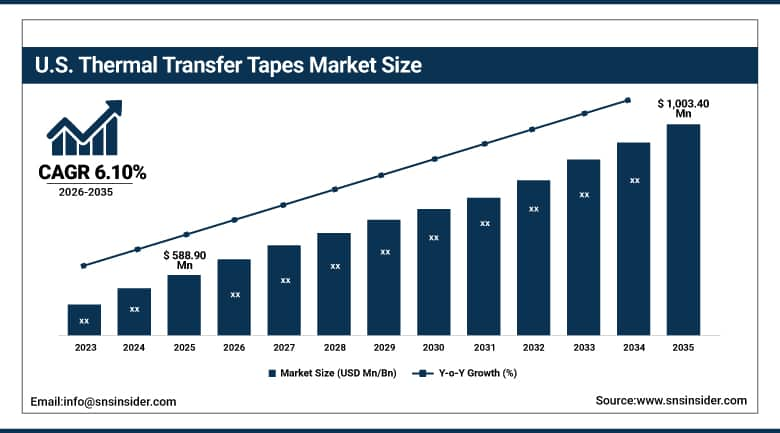
The U.S. Thermal Transfer Tapes Market was valued at USD 588.90 Million in 2025 and is projected to reach USD 1,003.40 Million by 2035, growing at a CAGR of 6.10% during 2026-2035.
The United States leads the thermal transfer tapes market for several reasons, strong domestic awareness of thermal transfer tape benefits drives higher adoption rates than in most other regions, and substantial investment in research and development continues producing advanced adhesive solutions that meet increasingly stringent industry standards. Aerospace, automotive, and electronics industries together account for a substantial share of domestic demand, requiring high-quality thermal transfer tapes capable of withstanding the harsh operating environments these sectors present. Rapid industrial automation and growing adoption in the medical industry are reinforcing demand beyond the category's traditional industrial base. Growing electric vehicle production domestically is also creating meaningful new demand for thermal management tape applications that barely existed in the category a decade ago.
In April 2025, Avery Dennison Performance Tapes introduced a new portfolio of pressure-sensitive adhesive tapes for building-envelope flashing and seaming applications.
Thermal Transfer Tapes Market Segment Analysis
-
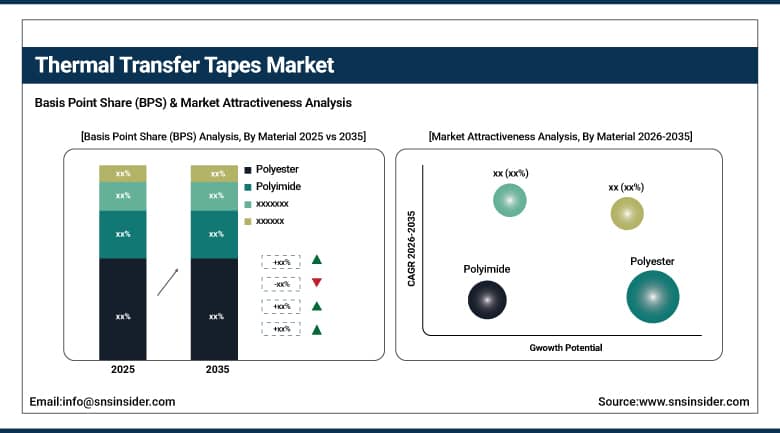
By Material, polyester dominates the thermal transfer tapes market with polyester holding 38% share in 2025 while polyimide grows fastest registering a CAGR of 7.60% from 2026 to 2035.
-
By Adhesive Type, acrylic dominates the thermal transfer tapes market with acrylic holding 44% share in 2025 while silicone grows fastest registering a CAGR of 7.20% from 2026 to 2035.
-
By Application, labeling / printing dominates the thermal transfer tapes market with label printing holding 36% share in 2025 while electronics assembly grows fastest registering a CAGR of 7.80% from 2026 to 2035.
-
By End-User Industry, retail & logistics dominates the Thermal transfer tapes market with retail & logistics holding 34% share in 2025 while medical grows fastest registering a CAGR of 8.20% from 2026 to 2035.
By Material, polyester dominates the thermal transfer tapes market while polyimide grows fastest
Polyester takes up 38% of the thermal transfer tapes market share, which is the largest category in the market. It continues to remain the largest category within the substrates category due to its combination of cost efficiency, dimensional stability, and suitability in multiple adhesives. The existing production facilities that rely on polyester continue to make it the preferred substrate in the standard label printing process.
Polyimide is growing at a CAGR of 7.60%, the highest CAGR among the substrates. This is due to its potential in rapid growth because of the thermal stability, chemical resistance, and electrical insulating characteristics with good potential for applications in the aerospace, automotive, and electronics industry. Miniaturization in electronics and high power densities in EVs have increased the demand for polyimide over the standard polyester substrate.
By Adhesive Type, acrylic dominates the thermal transfer tapes market while silicone grows fastest
Acrylic holds 44% of the market by adhesive type, the largest single category, valued for its versatile bonding performance across a wide temperature range and its cost efficiency relative to more specialized adhesive chemistries. Established formulation expertise across the tape manufacturing industry keeps acrylic the default adhesive choice for general-purpose thermal transfer tape applications.
Silicone is growing fastest, at a 7.20% CAGR, as high-temperature-resistant bonding requirements expand across automotive and electronics manufacturing, applications where acrylic adhesives cannot reliably maintain bond strength under sustained thermal stress. Nitto Denko's development of high-temperature-resistant bonding tapes for automotive applications illustrates how silicone adhesive technology is increasingly targeted at the industry's most demanding thermal environments.
By Application, label printing dominates the thermal transfer tapes market while electronics assembly grows fastest
Labeling / Printing represents 36% of application demands and is the largest single segment, owing to the well-established nature of the category, which involves the generation of high-resolution graphics on labels and tags. Increasing demand for durable labeling solutions across a range of industries continues to reinforce the lead of this application segment.
Electronics assembly is the fastest-growing application, expanding at a 7.80% CAGR, as the need for improved thermal transfer tape applications extends beyond conventional label printing into cutting-edge automotive and medical device manufacturing that requires precise, heat-resistant bonding during assembly. Rising power densities in AI chips and EV power modules are reinforcing demand for tapes capable of managing thermal loads that earlier electronics generations never generated.
By End-User Industry, retail & logistics dominates the thermal transfer tapes market while medical grows fastest
The retail & logistics segment makes up 34% of the total end user demand, which is the largest category, and is dependent on the level of barcode label printing, shipping labels, and point of sale requirements. With the increasing use of e-commerce and warehouse automation activities, this segment remains highly robust in terms of demand generation.
The medical industry is the most rapidly growing end-user industry segment with a 8.20% CAGR due to increasing automation in this industry. As more devices need components that have specific qualities like biocompatibility, the demand for thermal transfer tapes is rising steadily. With increasing production and strict requirements for component tracking, the medical industry will continue its above average growth trend.
Regional Analysis
|
Region |
Country |
Share within Region, 2025 (%) |
|
North America |
United States |
87.00% |
|
Asia Pacific |
China |
36.20% |
|
Europe |
Germany |
25.40% |
|
Middle East & Africa |
Saudi Arabia |
17.20% |
|
Latin America |
Brazil |
26.60% |
North America Thermal Transfer Tapes Market Insights
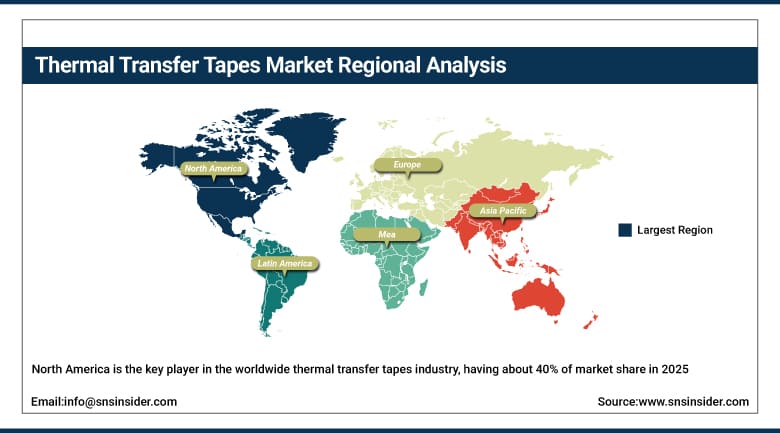
North America is the key player in the worldwide thermal transfer tapes industry, having about 40% of market share in 2025, due to rising demand in the automotive, electronics, and packaging sectors along with supportive government initiatives for green products and advancements in adhesive technologies. In North America, growth is mainly driven by increased usage of thermal transfer tapes in EV and electronics and not through initial adoption of the product in the category due to long-term usage of this tape as a routine product by industries here for many decades.
The United States alone occupies about 87.00% market share in North America, which is attributable to its presence of aerospace, automotive, and electronics manufacturing industries along with adhesive technology research & development investments.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Thermal Transfer Tapes Market Insights
Europe's thermal transfer tapes market is mature and steady, shaped by strong automotive and industrial manufacturing traditions alongside increasing regulatory focus on sustainable and eco-friendly adhesive formulations. Established relationships between major tape manufacturers and automotive and electronics customers continue supporting steady demand across the region.
Germany leads the European market with a 25.40% share, supported by its large automotive and industrial manufacturing base and advanced adhesive technology industry. France and the United Kingdom follow, with demand in both countries tied to established manufacturing sectors and growing electronics production.
Asia Pacific Thermal Transfer Tapes Market Insights
Asia Pacific is growing faster than any other region in this market, driven by rapid industrial automation, expanding electronics and EV manufacturing capacity, and rising government support for advanced manufacturing across China and India. Growing regional production of consumer electronics and electric vehicles continues creating exactly the kind of first-time and expanding adoption growth that mature markets like North America can no longer generate at comparable scale.
China holds roughly 36.20% of the regional market, supported by its massive electronics and EV manufacturing base and expanding industrial automation adoption. India and Southeast Asian markets are growing quickly as electronics manufacturing capacity expands, while Japan and South Korea contribute through their established, technology-forward adhesive and electronics industries.
Middle East & Africa and Latin America Thermal Transfer Tapes Market Insights
The Middle East & Africa region is witnessing steady growth owing to increasing industrial manufacturing capabilities in the Gulf nations fueled by increased investment in modern manufacturing and packaging capabilities. The Latin America region also sees similar growth rates due to the increasing industrial and electronics manufacturing capability in Brazil.
The United Arab Emirates holds the largest market share of 17.20% in the Middle East & Africa region due to its status as the industrial and manufacturing center in the region. In Latin America, Brazil holds the largest market share of 26.60% due to its large industrial manufacturing capability, while Mexico's automotive and electronics manufacturing capability contributes to the region.
Market Dynamics
Growth Drivers: Electronics Manufacturing Growth and EV Thermal Management Demand Fueling Market Growth
The increasing demand for thermal transfer tapes, which go beyond the traditional use in label printing to become part of advanced manufacturing techniques in the automotive and medical devices industries, can be considered the key force driving the growth of this market. Rising electric vehicle production is reinforcing this demand, as high-voltage battery systems require thermal management tapes capable of handling thermal loads that conventional automotive applications never generated.
Advancements in manufacturing processes and growing electronics production globally are adding a meaningful additional demand line, as increasingly compact, high-power electronic devices require more sophisticated thermal and adhesive solutions than earlier generations required.
Restraints: Raw Material Cost Volatility and Substrate Substitution Limiting Market Expansion
Raw material costs for specialty substrates and adhesive chemistries, tied to broader petrochemical commodity markets, make it difficult for tape manufacturers to hold pricing steady with industrial customers on long-term supply contracts. The availability of competing bonding and thermal management systems such as thermal pastes and mechanical fixings represents a true competitive risk in select cases where these products are able to perform comparably.
The regulatory issues associated with adhesion chemistry and material safety are quite different from market to market, representing real challenges when it comes to compliance.
Opportunities: High-Performance Substrate Innovation and Medical Applications Creating New Growth Avenues
High-performance substrate innovation, particularly polyimide formulations suited to aerospace, automotive, and electronics applications, represents a genuine growth opportunity as these industries increasingly require thermal stability and chemical resistance that standard substrates cannot reliably provide. Manufacturers who can scale premium substrate production while maintaining cost competitiveness stand to capture meaningful share as these demanding applications continue expanding.
Expansion into medical device manufacturing offers a second clear opportunity, particularly as rapid industrial automation and rising medical device production create genuine demand for thermal transfer tapes meeting the sector's stringent biocompatibility and performance requirements.
Recent Developments:
-
2024: Nitto Denko Corporation expanded its production capabilities in Malaysia to meet rising demand from the EV and electronics sectors, focusing on advanced adhesive and thermal conductive solutions.
-
2025: tesa SE established new offices in Mumbai and Bengaluru, India, strengthening its presence across Asia-Pacific for insulation and industrial adhesive tape applications.
-
2025: Avery Dennison Corporation launched biodegradable adhesive transfer tapes for medical and labeling industries, expanding its sustainable adhesive product portfolio.
-
2025: Nitto Denko Corporation developed high-temperature-resistant bonding tapes for automotive applications, reinforcing its position in the high-performance automotive bonding segment.
Thermal Transfer Tapes Market key players are:
-
Scapa Group plc
-
I.M. Technologies
-
JBC Technologies
-
H.B. Fuller Company
-
3M Company
-
Avery Dennison Corporation
-
Nitto Denko Corporation
-
tesa SE
-
Clearwater Paper Corporation
-
Lintec Corporation
-
Shurtape Technologies, LLC
-
Saint-Gobain Performance Plastics
-
CCL Industries Inc.
-
Electronic Imaging Materials, Inc.
-
WS Packaging Group, Inc.
-
Online Labels, Inc.
-
Dongguan Shengqiang Heat Transfer Products Co., Ltd.
-
Illinois Tool Works Inc.
-
DIC Corporation
-
Achilles Corporation
Thermal Transfer Tapes Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.69 Billion |
| Market Size by 2035 | USD 3.03 Billion |
| CAGR | CAGR of 6.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Polyester, Polyimide, PVC, Paper, Polyethylene, Others) • By Adhesive Type (Silicone, Acrylic, Rubber) • By Application (Labeling / Printing, Electronics Assembly, Packaging, Automotive, Industrial Applications, Others) • By End-User Industry (Retail & Logistics, Automotive, Electronics, Medical, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Scapa Group plc, I.M. Technologies, JBC Technologies, H.B. Fuller Company, 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, tesa SE, Clearwater Paper Corporation, Lintec Corporation, Shurtape Technologies, LLC, Saint-Gobain Performance Plastics, CCL Industries Inc., Electronic Imaging Materials, Inc., WS Packaging Group, Inc., Online Labels, Inc., Dongguan Shengqiang Heat Transfer Products Co., Ltd., Illinois Tool Works Inc., DIC Corporation, Achilles Corporation |
Frequently Asked Questions
Key players include 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, tesa SE, Scapa Group plc, Lintec Corporation, Shurtape Technologies, LLC, and CCL Industries Inc., alongside other established adhesive tape manufacturers.
Key opportunities include high-performance polyimide substrate innovation for aerospace and electronics applications, expansion into medical device manufacturing, and growing electric vehicle thermal management demand.
The market is driven by growing need for thermal transfer tape applications beyond conventional label printing, rising electric vehicle production, and advancements in electronics manufacturing.
The Polyester segment dominated the Thermal Transfer Tapes Market in 2025.
The North America region dominated the Thermal Transfer Tapes Market in 2025, supported by increasing demand from automotive, electronics, and packaging industries.
