
Underwater Concrete Market Report Scope & Overview:
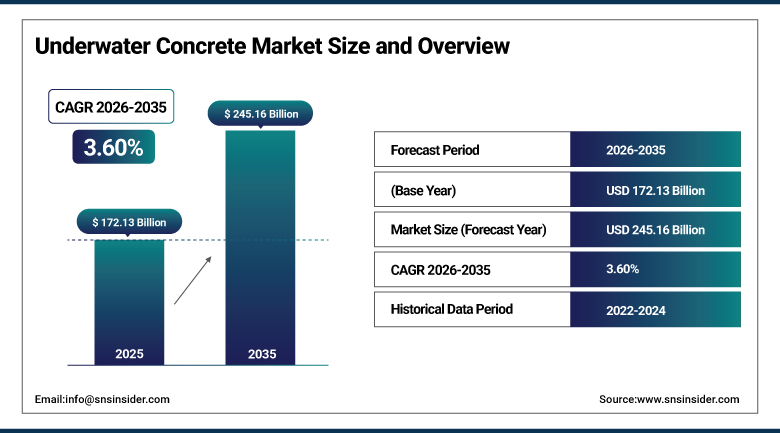
The Underwater Concrete Market was valued at USD 172.13 Billion in 2025 and is expected to reach USD 245.16 Billion by 2035, growing at a CAGR of 3.60% from 2026–2035.
The growth of the Underwater Concrete Market is influenced by higher investments made in marine infrastructure projects, energy projects, port constructions, harbor development, bridge, tunnel, and hydroelectric plant construction. The increasing coastal developments and growth in offshore wind and oil & gas projects are fueling the requirement of concrete material that can perform well under difficult underwater conditions. Development of infrastructure and replacement of old marine infrastructures are also contributing toward market growth. Innovations in concrete materials such as high-performance, fiber-reinforced, and polymer-modified concrete help in increasing strength, durability, and resistance against water infiltration and corrosion.
Royal Boskalis Westminster, in consortium with Bouygues Travaux Publics and Saipem, was awarded a roughly €552 million contract to design, build, and install 71 concrete Gravity-Based Structures as foundations for the Fécamp offshore wind farm off the coast of Normandy, France. Each foundation weighs up to 5,000 tonnes and sits on the seabed at depths between 25 and 30 meters, the kind of large-scale underwater concrete placement that offshore wind expansion is turning into a recurring, rather than occasional, category of work.
To Get more information Underwater Concrete Market - Request Free Sample Report
Underwater Concrete Market Trends
-
Offshore wind foundation construction is becoming a major, recurring demand driver as developers increasingly specify concrete gravity-based structures alongside steel monopiles, particularly for sites with challenging seabed conditions.
-
Self-consolidating, high-flow mix designs continue improving, letting concrete travel further through a tremie pipe and settle into complex formwork without segregating or trapping air pockets that would compromise structural integrity.
-
Admixture technology remains one of the most active areas of innovation, since the right combination of plasticizers and anti-washout agents determines whether an underwater pour actually holds together as it cures.
-
Environmental regulation around underwater construction is tightening, pushing contractors toward lower-turbidity placement methods and materials with reduced environmental impact on surrounding marine ecosystems.
-
Aging dam, lock, and port infrastructure across developed markets is driving a steady stream of rehabilitation work, giving underwater concrete demand a maintenance-driven baseline independent of new construction activity.
U.S. Underwater Concrete Market Outlook
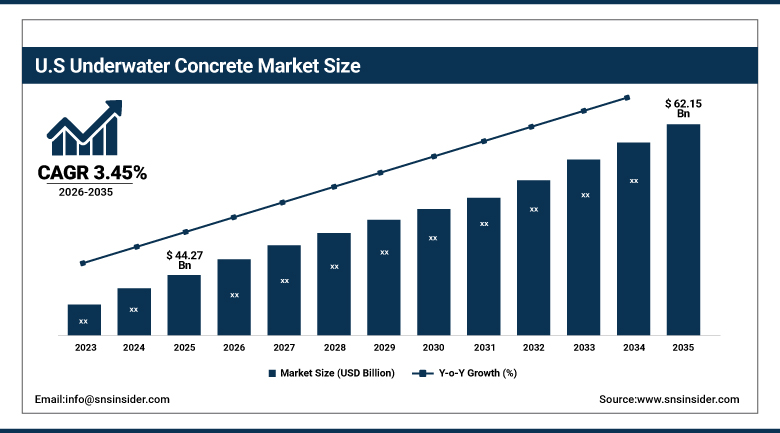
The U.S. Underwater Concrete Market was valued at approximately USD 44.27 Billion in 2025 and is expected to reach approximately USD 62.15 Billion by 2035, growing at a CAGR of approximately 3.45% from 2026–2035.
Much of the underwater concrete demand in the United States runs through U.S. Army Corps of Engineers projects, spanning lock and dam rehabilitation, port deepening, and coastal infrastructure work that increasingly specifies high-performance, self-consolidating mixes designed to place cleanly through a tremie pipe without segregating. That institutional demand gives U.S. suppliers a steadier, if less headline-grabbing, revenue base than the more visible offshore wind foundation work driving growth in Europe and parts of Asia. Growing U.S. offshore wind development along the Atlantic coast is beginning to add a newer layer of demand on top of this traditional infrastructure base.
Growth of the underwater concrete market has notably accelerated across North America in recent periods, led in the broader building materials space by companies including LafargeHolcim, HeidelbergCement, and Cemex, whose cement and admixture divisions supply much of the raw material behind large-scale U.S. marine and hydraulic construction projects.
Underwater Concrete Market Segment Analysis
-
By Product Type, the Tremie Concrete segment dominated the Underwater Concrete Market with approximately 46.0% share in 2025, while the Pumped Concrete segment is the fastest growing with a CAGR of approximately 7.4%.
-
By Technology, the Conventional segment dominated the Underwater Concrete Market with approximately 52.0% share in 2025, while the High-Performance segment is the fastest growing with a CAGR of approximately 8.2%.
-
By Material Type, the Cement segment dominated the Underwater Concrete Market with approximately 44.0% share in 2025, while the Admixtures segment is the fastest growing with a CAGR of approximately 7.8%.
-
By Application, the Marine & Coastal Infrastructure segment dominated the Underwater Concrete Market with approximately 50.0% share in 2025, while the Offshore Energy Projects segment is the fastest growing with a CAGR of approximately 8.6%.
-
By Depth, the Shallow Water segment dominated the Underwater Concrete Market with approximately 64.0% share in 2025, while the Deep Water segment is the fastest growing with a CAGR of approximately 8.9%.
By Product Type, tremie concrete dominates, pumped concrete grows fastest
Tremie concrete held the largest share of the product-type segment in 2025, remaining the industry-standard method for placing concrete underwater by feeding it through a vertical pipe that stays submerged in fresh concrete throughout the pour to prevent water contamination. Decades of proven use across marine construction have made tremie placement the default method contractors specify unless project conditions demand an alternative.
Pumped concrete is growing fastest as offshore and deep-water projects increasingly require the precise placement control and extended reach that pumping systems offer over gravity-fed tremie methods. That precision matters enormously for complex formwork and confined underwater spaces where a tremie pipe's more limited flexibility becomes a genuine constraint.
By Technology, conventional dominates, high-performance grows fastest
Conventional underwater concrete technology accounted for the largest share of the technology segment in 2025, remaining the practical, cost-effective choice for the majority of marine and hydraulic construction projects that don't face extreme structural or durability demands. Its established track record and lower material cost keep it the default specification for routine underwater construction work.
High-performance underwater concrete is growing fastest as offshore energy projects and other demanding applications require superior strength, durability, and resistance to the corrosive marine environment that conventional mixes struggle to match over a multi-decade structural lifespan. Offshore wind foundations in particular are pushing high-performance mix adoption, since these structures need to withstand constant wave and current loading for the life of the project.
By Material Type, cement dominates, admixtures grow fastest
Cement held the largest share of the material-type segment in 2025, representing the foundational binding material that every underwater concrete mix depends on regardless of the specific placement method or performance specification. Its role as the core structural component keeps cement the largest single material category by cost and volume.
Admixtures are growing fastest as high-performance plasticizers, anti-washout agents, and other specialized additives become increasingly central to achieving the flowability, cohesion, and durability that modern underwater placement techniques and regulatory quality standards both demand. Stricter quality requirements for underwater structures are directly reinforcing this shift toward more sophisticated, admixture-dependent mix designs.
By Application, marine & coastal infrastructure dominates, offshore energy projects grow fastest
Marine and coastal infrastructure accounted for the largest application share in 2025, spanning ports, harbors, seawalls, and coastal defense structures that represent the traditional core of underwater concrete demand. Continued global investment in port capacity and coastal protection keeps this the largest and most consistent application category.
Offshore energy projects are the fastest-growing application as offshore wind development in particular continues expanding rapidly across Europe, Asia, and increasingly North America, requiring large-scale concrete gravity-based foundations at sites with challenging seabed conditions. That expansion is pulling underwater concrete demand into an application category that barely existed as a meaningful volume driver a decade ago.
By Depth, shallow water dominates, deep water grows fastest
Shallow water applications held the largest share of the depth segment in 2025, covering the port, harbor, and near-shore construction work that represents the majority of underwater concrete projects by both volume and project count. Easier access and lower project complexity keep shallow water work the more common and cost-efficient category.
Deep water applications are growing fastest as offshore energy projects push construction activity into water depths that traditional port and coastal infrastructure work rarely required. That depth increase brings meaningfully greater technical complexity and cost per project, but the sheer scale of offshore wind and energy expansion is pulling sustained investment into deep-water underwater concrete capability.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
78.0% |
|
Europe |
Netherlands |
22.0% |
|
Asia Pacific |
China |
40.0% |
|
Latin America |
Brazil |
37.0% |
|
Middle East & Africa |
UAE |
33.0% |
North America Underwater Concrete Market Insights
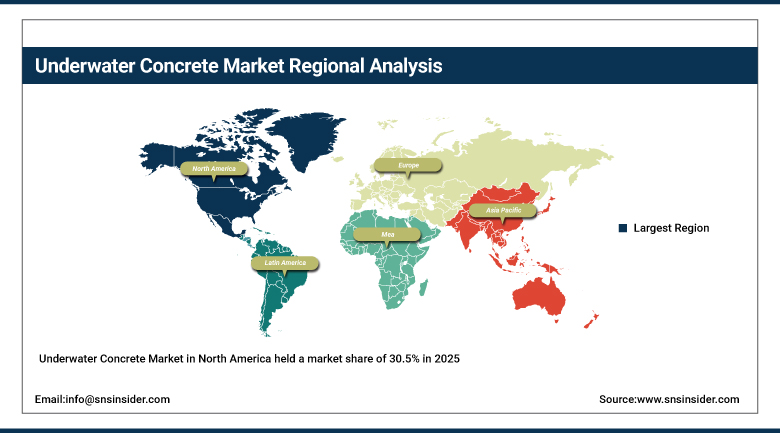
The Underwater Concrete Market in North America held a market share of 30.5% in 2025 owing to the presence of vast networks of ports, dams, and coastal infrastructure in the United States. Coupled with the ongoing growth in offshore wind projects in the Atlantic Coast region, the region holds significant project execution maturity due to established partnerships between cement and admixtures companies and marine contractors.
Canada adds its own significant contribution through the development of its own ports and hydropower resources, while the Mexican market continues developing due to the growth of its offshore and coastal energy activities. Supply chain relations between the countries unite much of North American demand, because the leading manufacturers of cement and admixtures normally deliver their products to all the three markets at once.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Underwater Concrete Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, due to the huge port expansion in China and rapid development of offshore wind energy generation in combination with new constructions of hydropower dams in the region. The rising investment in coastal and marine infrastructure in Southeast Asia stimulates regional demand for underwater concrete.
The development of ports and offshore energy projects in India attracts many investments, while in Japan and South Korea markets have already matured and have developed experience in marine construction. Offshore wind pipelines also develop in the last two countries. Southeast Asian markets are taking the same path.
Europe Underwater Concrete Market Insights
Europe is one of the most mature and technologically advanced markets for underwater concrete, fueled largely by the fact that Europe leads the world in offshore wind projects and has a substantial infrastructure in terms of ports and coastlines. The Netherlands is the driving force behind demand in the region, being home to large marine contractors with experience in underwater concrete placement.
The United Kingdom, France, and Germany also play important roles, each having offshore wind project pipelines that require significant construction of gravity-based foundations. Stringent European environmental regulations for marine construction influence placement methods and materials more directly in Europe than in most other markets.
MEA & Latin America Underwater Concrete Market Insights
The Middle East and Africa represent a smaller but strategically significant underwater concrete market, with the UAE driving demand through large-scale port expansion and coastal infrastructure investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader port and coastal infrastructure development.
The Latin America region represents a developing market, dominated by Brazil, which is driven by an expansion of ports' capacities and offshore construction of oil & gas infrastructure. There is also some secondary demand coming from Mexico and Colombia, driven by their respective port and coastal infrastructure development.
Market Dynamics
Growth Drivers: Offshore wind expansion and marine infrastructure investment fueling demand
Rapid global offshore wind expansion is one of the clearest forces behind rising underwater concrete demand, as developers increasingly specify concrete gravity-based structures for foundations at sites where seabed conditions don't favor steel monopiles. That structural choice is turning underwater concrete into a mainstream, high-volume component of offshore energy project budgets rather than a specialty niche.
Continued investment in marine and coastal infrastructure adds a second major driver, as growing global trade volumes push port operators to expand and deepen facilities that depend on underwater concrete for foundations, breakwaters, and berth construction. Rising coastal defense investment in response to sea-level rise and severe weather risk is reinforcing this demand base further.
Restraints: Project complexity and environmental regulation limiting execution speed
The inherent technical complexity of underwater construction remains a genuine restraint, since placement must succeed on the first attempt given how costly and difficult it is to remediate a flawed underwater pour after the fact. That risk profile pushes project timelines and costs higher than comparable dry-land concrete work, limiting how quickly contractors can execute large-scale programs.
Tightening environmental regulation around marine construction adds a further restraint, requiring contractors to manage turbidity, protect surrounding ecosystems, and navigate lengthy permitting processes before underwater work can even begin. That regulatory burden falls disproportionately on smaller contractors without the specialized environmental compliance capability larger marine construction firms have built over years.
Opportunities: Offshore energy foundation construction and aging infrastructure rehabilitation opening new growth avenues
Continued global offshore wind and energy expansion offers contractors and material suppliers a genuinely large and growing application, since gravity-based foundation construction requires substantially more concrete volume per project than most traditional marine infrastructure work. Companies that build strong offshore energy foundation expertise are positioned to capture disproportionate growth as this application continues expanding globally.
Aging dam, lock, and port infrastructure across developed markets represents a second significant opportunity, as decades-old structures increasingly require underwater rehabilitation and reinforcement work to remain safely operational. Contractors and material suppliers that build genuine underwater repair and rehabilitation expertise are positioned to capture a steady, maintenance-driven revenue stream independent of new construction cycles.
Recent Developments:
-
2025: Boskalis conducted dredging and berth preparation work at the Port of Hull, United Kingdom, supporting marshalling operations for the 1.4 GW Sofia offshore wind farm ahead of turbine foundation installation.
-
2025: Sika continued expanding its portfolio of underwater grouting, waterproofing, and admixture solutions for offshore wind turbine foundations, covering the full process from concrete mix design through post-installation grouting.
-
2025: Several major offshore wind developers continued specifying concrete gravity-based structures as an alternative to steel monopile foundations for sites with challenging seabed conditions, driving sustained demand for large-scale underwater concrete placement.
-
2025: Marine contractors continued advancing self-consolidating and high-performance concrete mix designs aimed at improving flowability and reducing segregation risk during tremie and pumped placement in deep-water applications.
Underwater Concrete Market Key Players
-
Sika AG
-
Holcim Ltd.
-
Heidelberg Materials
-
CEMEX S.A.B. de C.V.
-
CRH plc
-
Saint-Gobain
-
Mapei S.p.A.
-
Fosroc International Limited
-
Master Builders Solutions
-
GCP Applied Technologies
-
RPM International Inc.
-
Pidilite Industries Ltd.
-
Chryso SAS
-
Euclid Chemical
-
Normet Group
-
Kryton International Inc.
-
Xypex Chemical Corporation
-
MC-Bauchemie Müller GmbH & Co. KG
-
Penetron International Ltd.
-
Conmix Ltd.
Underwater Concrete Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 172.13 Billion |
| Market Size by 2035 | USD 245.16 Billion |
| CAGR | CAGR of 3.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Tremie Concrete, Pumped Concrete, Preplaced Aggregate Concrete, Others) • By Technology (Fiber-Reinforced, High-Performance, Polymer-Modified, Conventional) • By Material Type (Cement, Aggregates, Admixtures, Others) • By Application (Marine & Coastal Infrastructure, Offshore Energy Projects, Hydropower Projects, Bridges & Tunnels, Ports & Harbors, Others) • By Depth (Shallow Water, Deep Water) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Sika AG, Holcim Ltd., Heidelberg Materials, CEMEX S.A.B. de C.V., CRH plc, Saint-Gobain, Mapei S.p.A., Fosroc International Limited, Master Builders Solutions, GCP Applied Technologies, RPM International Inc., Pidilite Industries Ltd., Chryso SAS, Euclid Chemical, Normet Group, Kryton International Inc., Xypex Chemical Corporation, MC-Bauchemie Müller GmbH & Co. KG, Penetron International Ltd., Conmix Ltd. |
Frequently Asked Questions
Key opportunities include offshore wind foundations, marine infrastructure, pumped concrete, aging infrastructure rehabilitation, hydropower projects, and durable mix technologies.
Rapid global offshore wind expansion requiring concrete gravity-based foundations, combined with continued investment in marine and coastal infrastructure.
Marine & Coastal Infrastructure dominated with approximately 50.0% share in 2025, while Offshore Energy Projects is the fastest growing segment with a CAGR of approximately 8.6%.
North America dominated the Underwater Concrete Market in 2025, while Asia Pacific is the fastest-growing region.
