
Urinary Incontinence Treatment Devices Market Report Scope & Overview:
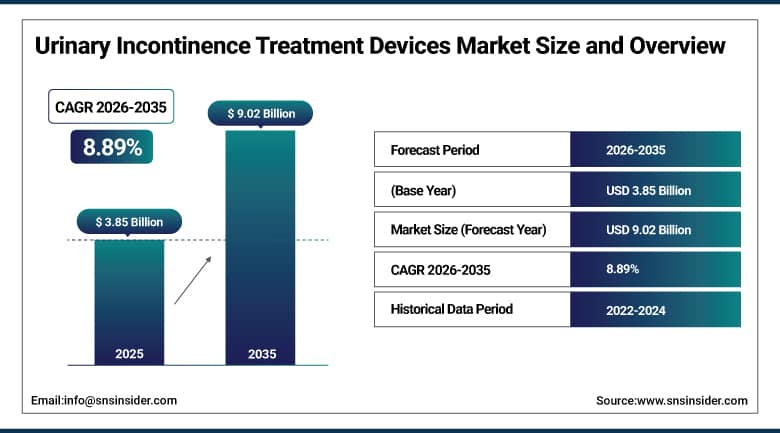
The Urinary Incontinence Treatment Devices Market was valued at USD 3.85 Billion in 2025 and is expected to reach USD 9.02 Billion by 2035, growing at a CAGR of 8.89% from 2026-2035.
Urinary incontinence treatment devices span surgical implants such as urethral and vaginal slings and artificial urinary sphincters, neuromodulation systems that recalibrate nerve signalling between the bladder and brain, and non-surgical products including catheters and pessaries that manage symptoms without an operating room. Roughly thirty million adults in the United States alone experience some form of urinary incontinence, and prevalence rises sharply with age, making this a genuinely large and durable patient population across every major healthcare system in the world. Growth is supported by an ageing global population, rising awareness that effective treatment options exist beyond simply living with the condition, and a wave of device innovation moving away from invasive lower-back implants toward less invasive alternatives that patients and physicians alike are increasingly willing to try. Reimbursement expansion, growing urology and urogynecology specialist capacity, and continued clinical evidence generation supporting device efficacy over pharmacological alternatives are further widening the addressable population for treatment devices rather than medication alone.
On September 19, 2025, Medtronic received U.S. Food and Drug Administration approval for its Altaviva implantable tibial neuromodulation device, the first implantable tibial device for urge urinary incontinence to activate therapy before a patient leaves the clinic, inserted near the ankle without requiring sedation or imaging and powered by a rechargeable battery expected to last fifteen years.
To Get More Information On Urinary Incontinence Treatment Devices Market - Request Free Sample Report
Urinary Incontinence Treatment Devices Market Trends:
-
Rising adoption of implantable tibial neuromodulation as a less invasive alternative to sacral implants.
-
Growing physician and patient preference for minimally invasive procedures performed without sedation or imaging.
-
Expanding rechargeable battery technology extending device longevity and reducing replacement surgery frequency.
-
Increasing merger and acquisition activity as larger device makers acquire specialised incontinence technology firms.
-
Rising diagnostic and treatment capacity within pelvic health as a distinct urology and urogynecology specialty.
-
Growing use of digital patient education and remote device programming supporting long-term therapy adherence.
U.S. Urinary Incontinence Treatment Devices Market Overview:
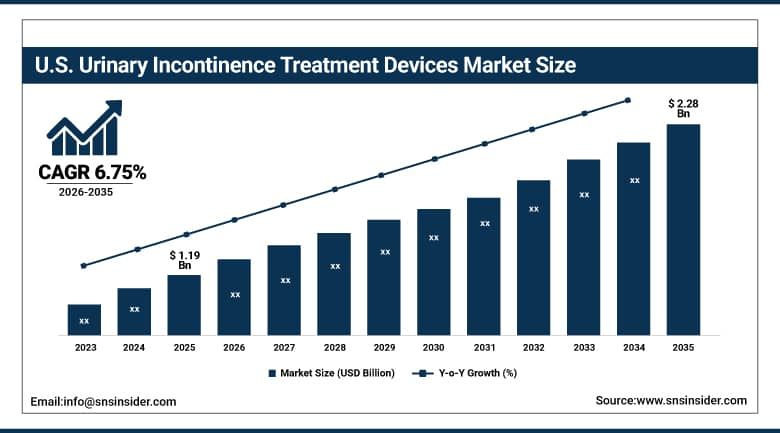
The U.S. Urinary Incontinence Treatment Devices Market was valued at USD 1.19 Billion in 2025 and is expected to reach USD 2.28 Billion by 2035, growing at a CAGR of 6.75% from 2026-2035.
The U.S. Urinary Incontinence Treatment Devices Market benefits from a large and ageing population, broad insurance and Medicare coverage for device-based therapy, and the presence of leading device manufacturers headquartered in the country that continue to compete on procedural simplicity and long-term reliability. Nearly thirty million adults over the age of forty in the country live with symptoms of overactive bladder, and a further nineteen million experience fecal incontinence, giving device makers an unusually large and clinically underserved population to pursue with next-generation therapy. Leading urology and pelvic health practices continue to expand physician training and procedure volume for both sacral and tibial neuromodulation, while established slings and artificial urinary sphincter programs continue to serve patients with more advanced or surgically complex presentations. Continued clinical evidence generation comparing newer minimally invasive options against legacy implants is expected to shift a growing share of eligible patients toward device-based therapy over the forecast period.
Boston Scientific reported that its Urology business, which includes the Axonics sacral neuromodulation portfolio acquired in the fourth quarter of 2024, generated net sales of USD 682 million during the third quarter of 2025 alone, with year-to-date Urology net sales increasing 26.9 percent, driven substantially by the impact of the Axonics acquisition and continued growth in the company's underlying stone management and incontinence franchises.
Urinary Incontinence Treatment Devices Market Segment Analysis:
-
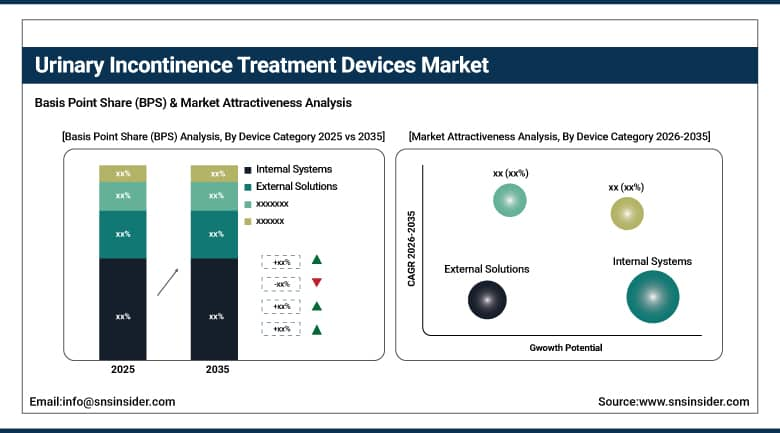
By Device Category, the Internal Systems segment dominated the market with a 61.02% share in 2025, while the External Solutions segment is the fastest growing with a CAGR of 12.02% during 2026-2035.
-
By Product, the Urethral and Vaginal Slings segment dominated the market with a 34.68% share in 2025, while the Electrical and Neuromodulation Devices segment is the fastest growing with a CAGR of 12.08% during 2026-2035.
-
By Incontinence Type, the Stress Incontinence segment dominated the market with a 47.85% share in 2025, while the Urge Incontinence segment is the fastest growing with a CAGR of 9.75% during 2026-2035.
-
By End User, the Hospitals segment dominated the market with a 55.12% share in 2025, while the Home-Care and Long-Term Care Settings segment is the fastest growing with a CAGR of 11.44% during 2026-2035.
By Device Category, Internal Systems Dominates the Market and External Solutions Grows Fastest
Internal systems dominated the market in 2025 with a 61.02% share, reflecting the clinical reality that most durable, long-term incontinence solutions require some form of implanted or surgically placed device rather than an external management product. Slings, artificial urinary sphincters, and neuromodulation implants all fall within this category, and their capacity to address the underlying physiological cause of incontinence, rather than simply managing its symptoms, continues to make internal systems the preferred approach whenever a patient's anatomy and overall health make surgery a reasonable option.
External solutions are expected to grow fastest over the forecast period, registering a CAGR of 12.02% as catheters, absorbent products with active management features, and pessary devices continue gaining ground among patients who are poor surgical candidates or who simply prefer to avoid an implant. Rising home healthcare adoption and growing comfort with self-managed external devices among older patients living independently continue to widen this category's addressable population, particularly as product design continues to improve comfort and discretion relative to older generations of external incontinence management equipment.
By Product, Urethral and Vaginal Slings Dominates the Market and Electrical and Neuromodulation Devices Grows Fastest
Urethral and vaginal slings dominated the market in 2025, built on decades of surgical familiarity and mature, well-established supply chains that continue to make this product category the default surgical option for stress urinary incontinence across most health systems worldwide. Female and male sling variants together cover the large majority of straightforward stress incontinence presentations, and the relatively short procedure time and strong long-term success rates these devices offer continue to sustain steady replacement and new-implant demand even as newer categories gain ground. Surgeons trained decades ago on sling placement continue to specify these products by default in the absence of a compelling reason to switch, and this entrenched clinical familiarity, more than any single technical advantage, continues to anchor slings as the largest product category across the broader urinary incontinence treatment devices market.
Electrical and neuromodulation devices are projected to be the fastest-growing product category over the forecast period, registering a CAGR of 12.08% as tibial and sacral nerve stimulation systems continue moving from a niche specialist procedure toward a genuinely mainstream first-line treatment option. Rising physician confidence in these systems, reinforced by regulatory approvals for devices that activate therapy immediately and require neither sedation nor imaging during implantation, continues to expand the pool of patients and physicians willing to consider neuromodulation ahead of more invasive sling or artificial sphincter surgery. Continued rechargeable battery innovation extending device life toward fifteen years is further reducing the lifetime cost of ownership relative to earlier-generation implants, reinforcing this category's above-market growth trajectory.
By Incontinence Type, Stress Incontinence Dominates the Market and Urge Incontinence Grows Fastest
Stress incontinence dominated the market in 2025. This form of incontinence, caused by physical strain such as coughing, laughing, or exercise placing pressure on a weakened pelvic floor, remains the single most commonly diagnosed incontinence type among women following childbirth and among the broader ageing population, and its well-understood surgical treatment pathway through sling placement continues to anchor stress incontinence as the largest addressable incontinence type.
Urge incontinence is projected to be the fastest-growing incontinence type over the forecast period. Rising prevalence of overactive bladder, a condition closely associated with urge incontinence and affecting an estimated thirty million adults in the United States alone, continues to expand the population of patients eligible for tibial and sacral neuromodulation therapy, positioning urge incontinence for sustained above-market growth as newer device categories increasingly target this specific patient population.
By End User, Hospitals Dominates the Market and Home-Care and Long-Term Care Settings Grows Fastest
Hospitals dominated the market in 2025 with a 55.12% share. Surgical implantation of slings, artificial urinary sphincters, and neuromodulation systems continues to require the operating room infrastructure, anaesthesia support, and post-procedure monitoring capability that only hospitals reliably provide at scale, and this procedural complexity continues to anchor hospitals as the leading end-user setting across the broader market.
Home-care and long-term care settings are projected to grow fastest over the forecast period, registering the highest projected CAGR at 11.44%, as external device management, catheter care, and post-implant device programming increasingly shift toward settings closer to where patients actually live. Growing acceptance of remote device programming and telehealth-supported follow-up care continues to make home-based and long-term care management a genuinely viable option for a growing share of the incontinence patient population.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
81.35% |
|
Europe |
Germany |
26.15% |
|
Asia Pacific |
China |
38.90% |
|
Latin America |
Brazil |
24.75% |
|
Middle East & Africa |
United Arab Emirates |
21.45% |
North America Urinary Incontinence Treatment Devices Market Insights
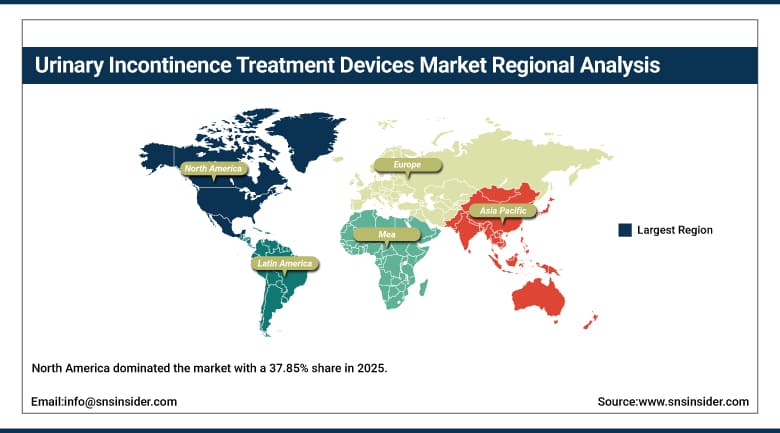
North America dominated the market with a 37.85% share in 2025, and the region is expected to continue growing at a CAGR of 6.75% through the forecast period. Broad insurance and Medicare coverage for device-based incontinence therapy, a large and rapidly ageing population, and the concentration of leading device manufacturers headquartered within the region continue to anchor this leadership position across every product category. The United States alone accounts for the substantial majority of regional revenue, reflecting both the scale of its healthcare system and its early adoption of newer neuromodulation technology relative to most other global markets.
Canada contributes meaningful incremental regional demand through its own publicly funded healthcare system, which continues to expand coverage for device-based incontinence therapy as clinical evidence supporting these approaches over pharmacological alternatives continues to accumulate. Continued expansion of urology and urogynecology specialist training programs across the region, combined with sustained device innovation from domestically headquartered manufacturers, is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets of Asia Pacific.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Urinary Incontinence Treatment Devices Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 9.65% as the region's rapidly ageing population, expanding hospital infrastructure, and growing urology specialist capacity continue to widen access to device-based incontinence treatment across both established and emerging regional healthcare systems.
China anchors regional demand through its enormous and rapidly ageing population combined with expanding private hospital capacity capable of offering advanced urological procedures. Japan contributes substantial mature demand given its exceptionally high proportion of elderly residents, while India and South Korea add further regional depth as urology specialist training programs and device reimbursement coverage continue to expand across both established and newly developing regional healthcare markets.
Europe Urinary Incontinence Treatment Devices Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial hospital sector and its position as home to several of the region's leading urology device manufacturers and clinical research institutions. The region's well-developed public health systems continue to sustain steady demand across both surgical and neuromodulation-based treatment categories.
The United Kingdom, France, and Italy add consistent regional demand as national health systems continue extending device-based incontinence therapy coverage to a broader share of their eligible patient populations. Continued clinical guideline development across major European urology societies is expected to sustain steady growth across the broader European market through the forecast period.
MEA and Latin America Urinary Incontinence Treatment Devices Market Insights
The Middle East and Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding specialist urology capacity and device reimbursement coverage as part of broader healthcare modernisation strategies targeting an ageing regional population.
Latin America is anchored by Brazil, where a growing domestic healthcare sector and expanding private insurance coverage continue to sustain steady demand for incontinence treatment devices. Mexico contributes further incremental growth as regional access to specialist urology and urogynecology care continues to widen gradually across the broader region.
Market Dynamics:
Growth Drivers: Ageing Population and Minimally Invasive Innovation
A rapidly ageing global population stands as the primary growth driver, as urinary incontinence prevalence rises sharply with age and continues to expand the pool of patients who eventually seek treatment beyond simply managing symptoms with absorbent products. Roughly thirty million adults in the United States alone experience overactive bladder symptoms, and comparable prevalence patterns across other major global markets continue to sustain a genuinely large and durable base of underlying patient demand that shows no sign of slowing as life expectancy continues to extend worldwide.
Continued innovation toward minimally invasive treatment options represents a second major driver, as newer implantable tibial neuromodulation systems that activate therapy immediately and require neither sedation nor imaging continue to lower the barrier patients and physicians alike must clear before considering device-based therapy. Growing clinical evidence directly comparing outcomes across sling, sphincter, and neuromodulation approaches continues to give physicians the confidence to expand device-based treatment to a broader range of patients than earlier generations of more invasive, surgically demanding technology ever reasonably allowed.
Restraints: Reimbursement Complexity and Patient Awareness Gaps
Reimbursement complexity remains a genuine restraint across several international markets, as coverage policies for newer neuromodulation devices continue to vary considerably between countries, and in some cases between individual insurers within the same country, creating genuine uncertainty for both patients and prescribing physicians when deciding which treatment pathway to pursue for a given clinical presentation.
Persistent gaps in patient awareness present a further restraint, as many individuals experiencing incontinence symptoms continue to view the condition as an inevitable, untreatable consequence of ageing rather than a genuinely treatable medical condition, delaying diagnosis and treatment initiation by years in some cases and continuing to constrain the addressable treatment population well below its true clinical potential across every major global market.
Opportunities: Tibial Neuromodulation Expansion and Home-Based Care Growth
Continued expansion of implantable tibial neuromodulation represents a substantial opportunity, as manufacturers that can deliver genuinely simpler, faster-activating alternatives to established sacral implants stand to capture a meaningful share of the large, underpenetrated overactive bladder population that has historically been reluctant to pursue more invasive lower-back implant surgery.
Continued growth of home-based and long-term care management offers a further avenue for expansion, as manufacturers that can deliver reliable remote device programming and genuinely comfortable external management products are positioned to capture demand from an ageing population increasingly choosing to manage chronic conditions from home rather than through repeated hospital visits, a shift reimbursement policy across several major markets is increasingly beginning to accommodate and actively encourage.
Recent Developments:
-
2026, UroMems raised USD 60 million from Ajax Health Fund I to support pivotal clinical trials and preparation for commercialization of its UroActive smart artificial urinary sphincter for stress urinary incontinence. The funding supports the company’s ongoing SOPHIA2 clinical trial in the U.S. and France.
-
2026, Bright Uro received FDA 510(k) clearance for its Glean Abdominal Sensor, expanding the Glean Urodynamics System to multi-channel, wireless and catheter-free ambulatory urodynamic studies. The technology is intended to support evaluation of lower urinary tract dysfunction, including urinary incontinence.
-
2026, Wellspect HealthCare launched the Surity Urinary Management System in the U.S., completing its Surity portfolio for urinary incontinence care. The at-home system provides a discreet urine-collection solution, following the company's earlier 2026 launches of female and male external catheters.
Urinary Incontinence Treatment Devices Market Key Players:
-
Boston Scientific Corporation
-
Medtronic plc
-
Coloplast A/S
-
Hollister Incorporated
-
B. Braun Melsungen AG
-
Cook Medical LLC
-
Becton, Dickinson and Company
-
Laborie Medical Technologies
-
ConvaTec Group plc
-
Teleflex Incorporated
-
Caldera Medical, Inc.
-
UroMed Corporation
-
Promedon S.A.
-
Contura International A/S
-
Neomedic International
-
CooperSurgical, Inc.
-
Panpac Medical Corporation
-
Renalis LLC
-
Vesitek, Inc.
-
Sofradim Production (Medtronic)
Urinary Incontinence Treatment Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.85 Billion |
| Market Size by 2035 | USD 9.02 Billion |
| CAGR | CAGR of 8.89% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Urethral and Vaginal Slings, Artificial Urinary Sphincters, Electrical and Neuromodulation Devices, Urinary Catheters, Pessary, and Other Devices) • By Device Category (Internal Systems and External Solutions) • By Incontinence Type (Stress Incontinence, Urge Incontinence, Overflow Incontinence, Functional Incontinence, and Mixed Incontinence) • By End User (Hospitals, Home-Care and Long-Term Care Settings, Ambulatory Surgical Centers, and Specialty Clinics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Boston Scientific Corporation, Medtronic plc, Coloplast A/S, Hollister Incorporated, B. Braun Melsungen AG, Cook Medical LLC, Becton, Dickinson and Company, Laborie Medical Technologies, ConvaTec Group plc, Teleflex Incorporated, Caldera Medical, Inc., UroMed Corporation, Promedon S.A., Contura International A/S, Neomedic International, CooperSurgical, Inc., Panpac Medical Corporation, Renalis LLC, Vesitek, Inc., Sofradim Production (Medtronic) |
Frequently Asked Questions
Key players include Boston Scientific Corporation, Medtronic plc, Coloplast A/S, Hollister Incorporated, and B. Braun Melsungen AG, among other medical device manufacturers.
Continued expansion of implantable tibial neuromodulation and continued growth of home-based and long-term care management represent the primary opportunities.
Growth is primarily driven by a rapidly ageing global population, combined with continued innovation toward minimally invasive treatment options.
By Product, Urethral and Vaginal Slings dominated the market with a 34.68% share in 2025, reflecting decades of surgical familiarity and mature supply chains.
North America dominated the market with a 37.85% share in 2025, supported by broad insurance coverage and a large, ageing population.
