
Welding Materials Market Report Scope & Overview:
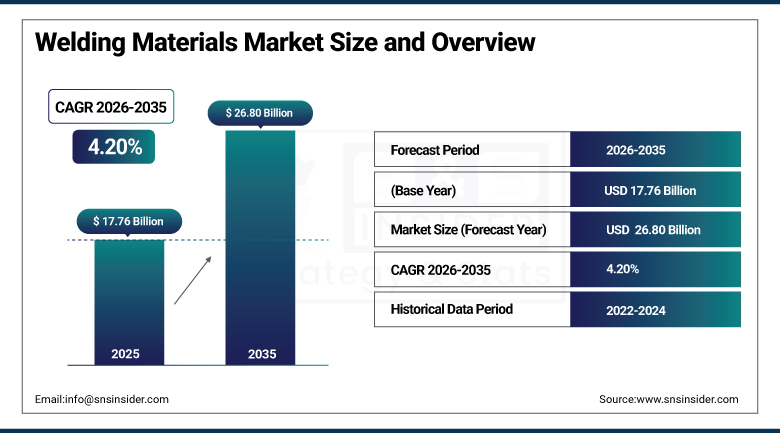
The Welding Materials Market was valued at USD 17.76 Billion in 2025 and is expected to reach USD 26.80 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
The Welding Materials Market is expanding owing to increased infrastructural development, industrial growth, and growing demands from the construction, automotive, transportation, energy, and heavy manufacturing industries. The investments being made in the form of roads, bridges, railways, pipelines, industrial plants, and energy infrastructures have led to constant demands for welding materials. The automobile industry is adopting new-age metals and materials, leading to the need for innovative welding technologies that join such dissimilar substrates. Moreover, there is an increase in automation of welding machines, resulting in the need for high-quality electrodes, wires, fillers, and shielding gases.
In July 2024, Lincoln Electric completed its acquisition of Vanair, a manufacturer of automotive components including compressed air and power generation systems. The company stated the acquisition is projected to add approximately USD 50 million in annual revenue and supports its strategy of expanding its industrial and automated welding solutions portfolio.
To Get more information On Welding Materials Market - Request Free Sample Report
Welding Materials Market Trends
-
Growing adoption of shielding and cutting gases supporting specialized, high-quality welding applications.
-
Rising integration of automation and robotic welding systems across automotive and heavy industry manufacturing.
-
Expanding demand for tubular cored electrodes supporting high-strength steel welding applications.
-
Increasing manufacturer investment in digitalization tools improving weld quality and regulatory compliance.
-
Rising demand for welding materials supporting infrastructure and transportation manufacturing projects.
U.S. Welding Materials Market Overview
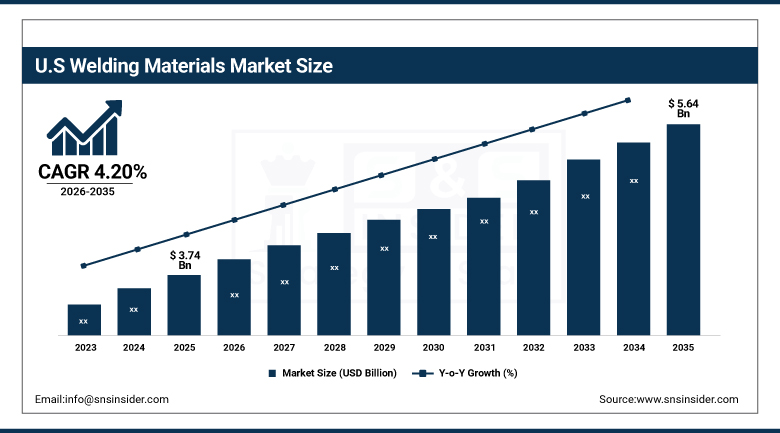
The U.S. Welding Materials Market was valued at USD 3.74 Billion in 2025 and is expected to reach USD 5.64 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
The U.S. Welding Materials Market is growing due to infrastructure development, construction works, and demands of automotive industry, transportation, energy, and heavy industries. Infrastructure modernization is driving up the demand for welding materials like electrodes, wires, rods, and shielding gases required for bridges, pipelines, utilities, and industries. Growing use of automated and robotic welding systems is contributing to the demand for quality welding materials like electrodes, wires, filler metals, and shielding gases. Manufacturers of automobiles are utilizing more lightweight materials, leading to the need for more welding technology. Technological innovations in welding processes and special gases are enhancing efficiency and quality of the welding process.
In February 2025, Lincoln Electric launched its Ranger Air 330MPX multi-function engine drive, expanding its portfolio of field-ready welding power sources. The company stated the launch reflects continued investment in versatile, multi-process equipment supporting demanding fieldwork applications across construction and infrastructure projects.
Welding Materials Market Segment Analysis
-
By Type, the Electrodes & Filler Materials segment dominated the market with a 47.00% share in 2025, while the Gases segment is the fastest growing with a CAGR of 5.80% during 2026-2035.
-
By Technology, the Arc Welding segment dominated the market with a 52.00% share in 2025, while the Resistance Welding segment is the fastest growing with a CAGR of 5.40% during 2026-2035.
-
By End-Use Industry, the Heavy Industries segment dominated the market with a 38.60% share in 2025, while the Transportation segment is the fastest growing with a CAGR of 5.90% during 2026-2035.
By Type, Electrodes & Filler Materials Dominates the Market and Gases Grows Fastest
Electrodes & Filler Materials dominated the market in 2025, a position built on their essential role across virtually every major welding technology, including arc welding, MIG/MAG, and TIG processes. Fabricators favour this material category precisely because it delivers the fundamental consumable input required to complete any welded joint, a combination that continues to make electrodes and filler materials the largest single type category across the broader market, even as gases continue to expand around it for specialized applications.
Gases are projected to be the fastest-growing type category over the forecast period. Rising demand for shielding and cutting gases continues to expand the addressable application base for this type category as industries increasingly adopt advanced manufacturing processes requiring specialized, high-quality, and efficient welding applications. As automated and robotic welding systems continue proliferating across automotive and heavy industry manufacturing, gases continue to close the gap with electrodes and filler materials in overall market demand.
By Technology, Arc Welding Dominates the Market and Resistance Welding Grows Fastest
Arc Welding dominated the market in 2025, accounting for over half of overall global market share. This technology's wide applicability, cost-effectiveness, and operational flexibility across multiple industries continue to anchor its leading position, as arc welding remains the default process specification across construction, automotive, shipbuilding, and general fabrication applications worldwide. This foundational versatility continues to sustain arc welding as the dominant technology category by a clear margin across the broader market.
Resistance Welding is expected to be the fastest-growing technology category over the forecast period. Rising demand for high-speed, automated joining processes continues to expand the addressable application base for this technology category as automotive manufacturers increasingly specify resistance welding for high-volume body panel and structural component assembly. As vehicle production continues incorporating more automated assembly processes, resistance welding continues to close the gap with arc welding in overall market demand.
By End-Use Industry, Heavy Industries Dominates the Market and Transportation Grows Fastest
Heavy Industries end-use dominated the market in 2025. Sustained global industrial manufacturing activity, spanning energy and power, oil and gas, marine, and general fabrication applications, continues to represent the largest single driver of overall welding materials consumption, given the scale and continuous nature of heavy industrial fabrication and maintenance operations. This foundational industrial role continues to sustain heavy industries as the leading end-use category by a clear margin across the broader market.
Transportation end-use is expected to be the fastest-growing category over the forecast period. Rising automotive and rail manufacturing activity, combined with growing adoption of automated and robotic welding systems for vehicle body assembly, continues to expand the addressable application base for this end-use category. As automakers continue pursuing multi-material vehicle architectures and increased production automation, transportation end-use continues closing the gap with heavy industries in overall market demand.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
China |
41.60% |
|
North America |
United States |
78.60% |
|
Europe |
Germany |
31.80% |
|
Latin America |
Brazil |
43.60% |
|
Middle East & Africa |
United Arab Emirates |
29.80% |
North America Welding Materials Market Insights
North America represents a significant regional market for welding materials, anchored by the United States' substantial automotive, heavy machinery, and infrastructure manufacturing industries. The United States accounts for the substantial majority of regional demand, reflecting both its manufacturing scale and its concentration of leading welding materials and equipment manufacturers.
Canada and Mexico contribute additional regional volume through cross-border automotive and heavy industry supply chain integration. Continued domestic investment in automated welding technology and specialty consumables is expected to keep supporting steady regional market development even as growth in percentage terms trails faster-scaling Asia Pacific markets building out manufacturing capacity from a smaller existing base.
Europe Welding Materials Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established welding materials manufacturers and continued advancement in specialty consumables developed for automotive and heavy industry applications. Germany's substantial automotive and industrial manufacturing base anchors regional demand, supported by a well-developed regulatory framework that continues to favour early adoption of automated and digitalized welding technology across the country and neighbouring markets.
The United Kingdom, France, and Italy contribute additional regional demand, supported by established automotive, shipbuilding, and heavy industry manufacturing sectors. Continued European emphasis on digitalization and regulatory compliance supports steady regional demand for advanced, quality-controlled welding consumables.
Asia Pacific Welding Materials Market Insights
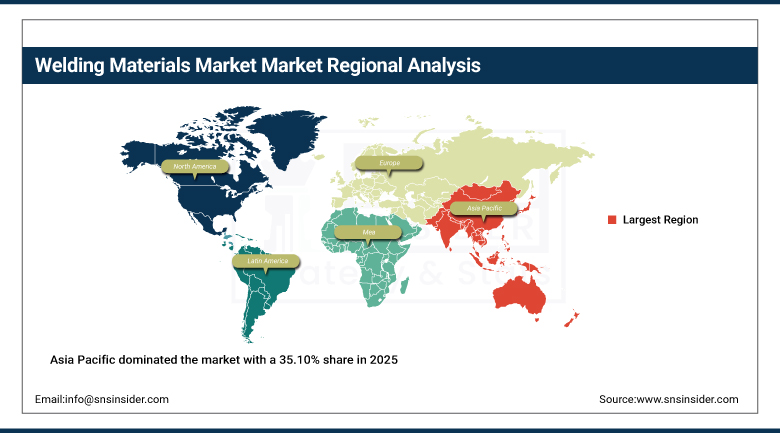
Asia Pacific dominated the market with a 35.10% share in 2025 and is also projected to expand at the fastest pace during the 2026-2035 forecast period, driven by rapid growth in construction, automotive, shipbuilding, and infrastructure projects across the region. China continues to anchor regional demand as domestic construction and manufacturing sectors expand production capability across both established coastal manufacturing hubs and rapidly developing inland provinces, supported by sustained government-led industrialization and manufacturing initiatives.
India's expanding infrastructure and automotive manufacturing sectors continue adding meaningful regional growth as domestic fabricators extend welding capability into previously underserved construction and industrial applications. Japan and South Korea contribute further depth through established, technically advanced shipbuilding and automotive manufacturing sectors, positioning the wider region to sustain both the largest revenue base and the fastest percentage growth of any global market through 2035.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Welding Materials Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand on the strength of its growing automotive and heavy industry manufacturing sector. Gradual growth in domestic infrastructure and manufacturing production continues to support steady regional market development.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding energy, oil and gas, and infrastructure investment is increasingly driving demand for specialty welding consumables. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed industrial manufacturing infrastructure.
Growth Drivers: Infrastructure Development and Automation Adoption
Development of infrastructure and increase in industrial activities are among the key factors fueling growth in the Welding Materials Market as many sectors including construction, transport, heavy industries, energy and manufacturing need significant amounts of welding materials. Road constructions, bridges, railways, utility construction, industrial construction and energy infrastructure have been contributing to demand for welding consumables such as electrodes, filler materials, wires and shielding gases.
The manufacturing of automotive parts and heavy machinery requires steady demands for welding materials. Moreover, increased use of digitalized and automated manufacturing systems results in rising demand for consumable materials suitable for robotic and automated welding operations. In addition, increased use of specialized shielding gases and cutting gases is contributing to the growth of the market.
Restraints: Raw Material Price Volatility and Skilled Labor Shortages
Volatility in raw material prices is yet another constraint for the Welding Materials Market since manufacturers require steel, nickel, aluminum, alloy metals, and other metallic products for the production of electrodes, wires, and fillers. Volatile changes in commodity prices, energy prices, transport costs, and availability of supplies can lead to higher production costs and difficulties for companies that need to develop effective pricing strategies in the long term. Smaller regional companies might face even more pressure as they usually lack purchasing power and are not able to cover sudden cost surges in the input costs.
Shortage of skilled labor is another significant challenge which will have a negative impact on operations, project implementation times and productivity. With more experienced welders retiring, shortage of skilled personnel in the industry might become a major problem.
Opportunities: Automated Welding Systems and Specialty Gas Formulation
The future of robotic and automated welding systems offers considerable potential, especially with manufacturers looking to boost productivity, quality of welds, and efficiency. The automotive industry, heavy machinery industry, transportation industry, and industries involved in manufacturing are beginning to rely more and more on robotic welding technology, giving rise to the need for specialized welding supplies designed to perform at automatic deposition rates and precise feeding.
Robotic welding can also contribute to addressing any shortages in manpower by minimizing reliance on highly skilled manual welding techniques for performing repetitive work. Specialty gases for both shielding and cutting present another key area of development, as the growing complexity of welding technologies calls for gases that are specially formulated for particular metals and processes. Companies possessing good formulation knowledge and distribution networks will benefit from these developments in advanced industrial welding.
Recent Developments
-
2025: Lincoln Electric launched its Ranger Air 330MPX multi-function engine drive, expanding its portfolio of field-ready, multi-process welding power sources.
-
2025: ESAB continued expanding its consumables portfolio, including its Spoolarc MIG wire, Atom Arc stick electrode, and OK flux-cored wire product lines serving fabrication and heavy industry customers.
-
2025: Air Liquide continued expanding its shielding and cutting gas portfolio, addressing rising demand for specialized, high-quality welding applications across advanced manufacturing processes.
-
2025: voestalpine Böhler Welding continued developing specialty welding consumables for demanding industrial applications, including high-strength steel and corrosion-resistant alloy welding.
Welding Materials Companies are:
-
Lincoln Electric Holdings, Inc.
-
Illinois Tool Works Inc.
-
voestalpine Böhler Welding GmbH
-
ESAB Corporation
-
Air Liquide S.A.
-
Tianjin Bridge Welding Materials Group Co., Ltd.
-
Ador Welding Limited
-
Gedik Welding Inc.
-
Panasonic Corporation
-
Hyundai Welding Co., Ltd.
-
Fronius International GmbH
-
Daihen Corporation
-
Thermadyne Holdings Corporation
-
Special Metals Corporation
-
EWM AG
-
Denyo Co., Ltd.
-
Miller Electric Mfg. LLC
-
Golden Bridge
Welding Materials Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 17.76 Billion |
| Market Size by 2035 | USD 26.80 Billion |
| CAGR | CAGR of 4.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Electrodes & Filler Materials, Fluxes & Wires, Gases) • By Technology (Arc Welding, Resistance Welding, Oxy-Fuel Welding) • By End-Use Industry (Heavy Industries, Building & Construction, Transportation) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lincoln Electric Holdings, Inc., Illinois Tool Works Inc., voestalpine Böhler Welding GmbH, ESAB Corporation, Air Liquide S.A., Kobe Steel, Ltd., Tianjin Bridge Welding Materials Group Co., Ltd., Ador Welding Limited, Gedik Welding Inc., Panasonic Corporation, Hyundai Welding Co., Ltd., Fronius International GmbH, Daihen Corporation, Sandvik AB, Thermadyne Holdings Corporation, Special Metals Corporation, EWM AG, Denyo Co., Ltd., Miller Electric Mfg. LLC, Golden Bridge |

Frequently Asked Questions
Key players include Lincoln Electric, Illinois Tool Works, voestalpine Böhler Welding, ESAB, Air Liquide, Kobe Steel, Tianjin Bridge Welding Materials Group, among others.
Automation and robotic welding advancements, alongside specialized shielding and cutting gas development, create significant opportunities for market expansion.
Growth is primarily driven by rising demand from various end-use industries, combined with the growing impact of digitalization and automation across manufacturing operations.
By Technology, Arc Welding dominated the market with a 52.00% share in 2025, reflecting its wide applicability, cost-effectiveness, and operational flexibility across multiple industries.
Asia Pacific dominated the market with a 35.10% share in 2025, driven by rapid growth in construction, automotive, shipbuilding, and infrastructure projects, led by China.
