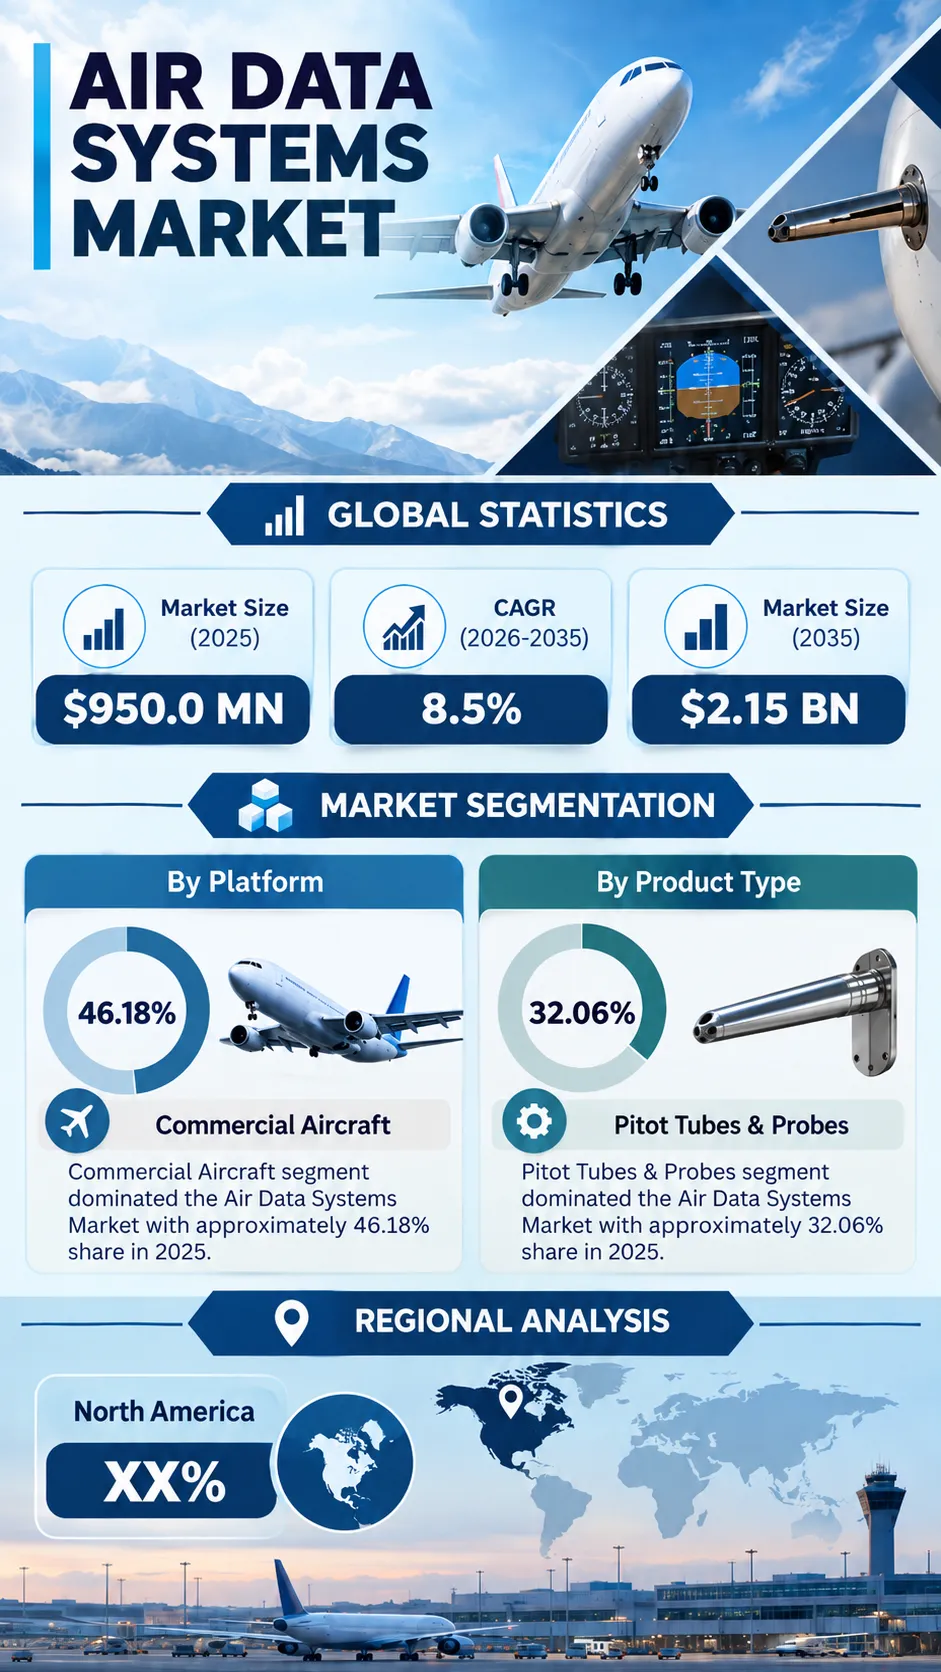
The global Air Data Systems Market continues its steady climb as airlines and defense operators lean further into digital, sensor-rich flight measurement technology. “According to a recent study by SNS Insider, the global Air Data Systems Market Size valued at USD 950.0 million in 2025, is anticipated to grow to USD 2.15 billion by 2035, registering a CAGR of 8.5% over the 2026-2035 forecast period.”
There have been steady changes within sensor and digital processing technology over time, due to which many manufacturers aiming at improved accuracy and reliability can take advantage of this trend. This includes the need for more resilient, MEMS-based digital sensor systems that give operators confidence in flight safety and predictive maintenance, across a wide range of applications from commercial airliners to unmanned aerial vehicles. This applies in situations where air data systems are used across commercial and military aviation applications.
Manufacturers are constantly working to improve sensor accuracy and system reliability in order to meet various needs of airlines and defense operators worldwide.
To Get Detailed Insights on the Air Data Systems Market – Request a Sample Report
Fleet Modernization and Defense Procurement Ecosystems Create New Demand
The air data systems market has evolved from basic mechanical pressure gauges into a broader mix of digital, integrated, and UAV-specific sensing platforms. The growing investment in MEMS-based sensor technology, predictive maintenance integration, and multi-platform development has required the development of more efficient and reliable production systems.
New sensor and processing approaches can improve accuracy, reduce maintenance burden, and expand the range of applications air data systems can serve. This gives manufacturers the possibility to be more effective when reaching airline and defense buyers and strengthening claims around reliability and safety.
Air data system manufacturers, airframers, and defense agencies are increasingly cooperating due to the growing interest in developing future solutions for accurate, reliable flight measurement technology.
Key Market Findings Highlight High-Growth Segments
The commercial aircraft segment dominated all categories in the air data systems market share with a market revenue share of approximately 46.18% in 2025 due to the scale of the global commercial fleet and mandatory redundant systems.
The fastest growing category is expected to be the UAVs segment, which will grow at a CAGR of approximately 11.4% through 2035. This will be possible owing to expanding military and commercial drone programs specifying dedicated air data sensing packages.
By technology, conventional/mechanical held the largest share of total market revenue at approximately 58.14% in 2025 due to the substantial installed base of older aircraft running proven pneumatic systems. The smart/digital segment will see the fastest growth in revenue generation at a CAGR of approximately 12.6%.
Regional trends show North America leading with approximately 34.0% revenue share in 2025, while Asia Pacific is expected to register a fast growth trajectory driven by civil aviation fleet recovery and expanding unmanned aerial systems investment across the region.
Sensor Accuracy, Predictive Maintenance, and Platform Diversification Gain Importance
In this regard, manufacturers have been looking at air data system products that would sense more accurately, predict maintenance needs earlier, and serve more diverse aircraft platforms.
Innovation in MEMS-based digital sensors, AI-driven predictive maintenance, and multi-platform development has been making it possible for companies to come up with products that can meet increasingly demanding airline and regulatory expectations. In addition to that, increasing emphasis on UAV-specific system design is also making it possible for companies to find solutions that support expanding unmanned aviation applications.
Such trends are likely to become even more prominent in the future.
North America Leads Amid Deep Manufacturer Concentration and Defense Spending
North America represented approximately 34.0% share of global market revenue in 2025 and was the largest regional market, owing to the United States' concentration of leading air data system manufacturers and deep military and commercial aerospace procurement activity. In addition, Asia Pacific is expected to register a fast growth trajectory during the forecast period, propelled by civil aviation fleet recovery and China's COMAC C919 program scaling up production across the region.
On the other hand, Europe represented a meaningful share of global market revenue in 2025, aided by France's position as home to Airbus and a deep base of aerospace component suppliers.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on sensor and digital processing technology as well as forming partnerships in order to enhance their position in the industry.
Some of the major companies that operate in the global air data systems market are Honeywell International Inc., RTX Corporation, Curtiss-Wright Corporation, AMETEK, Inc., Thales Group, Safran S.A., Meggitt PLC, Parker Hannifin Corporation, Ultra Electronics Holdings plc, and Ducommun Incorporated.
An SNS Insider Analyst Sushant Kadam commented, “The steady shift toward digital, sensor-rich air data systems is creating consistent demand across commercial and military aviation applications. Manufacturers that successfully combine MEMS-based sensor innovation, predictive maintenance integration, UAV-specific system design, and reliable defense and airline partnerships will be best positioned to capitalize on emerging opportunities across commercial and military aviation applications.”
About the Author
Get in touch