
Air Data Systems Market Report Scope & Overview:
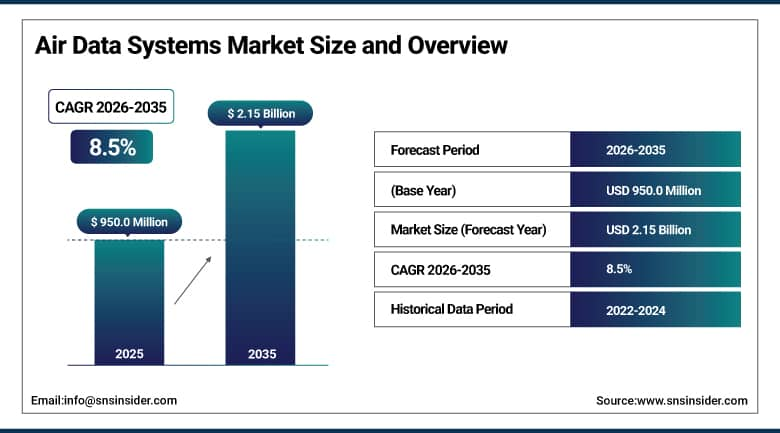
The Air Data Systems Market was valued at USD 950.0 Million in 2025 and is expected to reach USD 2.15 Billion by 2035, growing at a CAGR of 8.5% from 2026–2035.
Air data systems take raw pressure and temperature readings from pitot tubes and static ports and turn them into the airspeed, altitude, and angle-of-attack numbers a pilot and flight computer both depend on to keep an aircraft flying safely. They've evolved from simple mechanical pressure gauges in early propeller aircraft into fully digital, redundant suites that fly-by-wire systems can't function without. Every reading has to be right, since a faulty air data reading has been a contributing factor in some of aviation's most studied accidents, which is exactly why the certification bar for this category sits as high as it does.
Collins Aerospace, an RTX Corporation company with more than 60 years of air data experience, launched a new generation of pitot probes in March 2025 built for enhanced icing resistance, higher reliability, and reduced maintenance across both widebody and narrowbody aircraft. The company tests its designs in a wind tunnel capable of blasting ice particles at Mach 0.9 while holding temperatures down to -90°F, a reminder that an air data sensor's real job isn't measuring airspeed on a clear day, it's still working correctly after an hour flying through freezing rain at altitude.
To Get More Information On Air Data Systems Market - Request Free Sample Report
Air Data Systems Market Trends
-
Smart, MEMS-based digital sensors continue displacing older mechanical designs, offering better accuracy, easier integration with modern avionics, and real-time data processing that older pneumatic systems can't match.
-
AI-driven predictive maintenance modules are being integrated into legacy air data systems, letting operators anticipate sensor drift before it becomes a safety issue rather than relying purely on scheduled inspection intervals.
-
UAV and unmanned platform demand is expanding the addressable market for air data sensors well beyond traditional manned aircraft, with both fixed-wing and rotary-wing drone programs specifying dedicated, miniaturized sensing packages.
-
Consolidation continues among aerospace sensor manufacturers, as companies acquire flight-data analytics and telemetry specialists to offer more complete, end-to-end air data solutions rather than standalone sensors.
-
Lightweight titanium pitot-static probe designs are gaining adoption as airlines pursue every available avenue for cutting drag and fuel burn in support of broader decarbonization commitments.
U.S. Air Data Systems Market Outlook
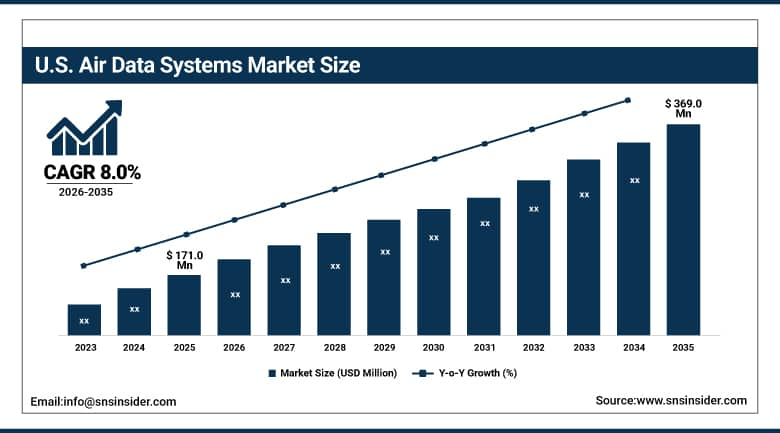
The U.S. Air Data Systems Market was valued at approximately USD 171.0 Million in 2025 and is expected to reach approximately USD 369.0 Million by 2035, growing at a CAGR of approximately 8.0%.
Demand in the United States is anchored by a concentration of leading air data system manufacturers alongside deep military and commercial aerospace procurement activity. Long-duration military sustainment contracts provide domestic suppliers with a more predictable revenue base than the more cyclical commercial aviation order book, particularly as defense modernization programs continue prioritizing UAV and advanced flight test instrumentation capability. Close, decades-long relationships between air data suppliers and major U.S. airframers continue reinforcing domestic manufacturers' leading technology position.
Curtiss-Wright Corporation, based in Davidson, North Carolina, was awarded a roughly USD 80 million Indefinite Delivery, Indefinite Quantity contract by the U.S. Air Force in June 2025 to supply its High-Speed Data Acquisition System hardware and repair services through March 2030. The sole-source award covers flight test instrumentation across current production platforms and future USAF development programs, the kind of long-duration military sustainment contract that gives domestic air data systems suppliers a more predictable revenue base than commercial aviation's boom-and-bust order cycles typically provide.
Air Data Systems Market Segment Analysis
-
By Platform, the Commercial Aircraft segment dominated the Air Data Systems Market with approximately 46.18% share in 2025, while the UAVs segment is the fastest growing with a CAGR of approximately 11.4%.
-
By Product Type, the Pitot Tubes & Probes segment dominated the Air Data Systems Market with approximately 32.06% share in 2025, while the Multi-Function Air Data Systems segment is the fastest growing with a CAGR of approximately 10.8%.
-
By Component, the Sensors segment dominated the Air Data Systems Market with approximately 41.23% share in 2025, while the Electronic Unit segment is the fastest growing with a CAGR of approximately 9.6%.
-
By Technology, the Conventional/Mechanical segment dominated the Air Data Systems Market with approximately 58.14% share in 2025, while the Smart/Digital segment is the fastest growing with a CAGR of approximately 12.6%.
-
By Application, the Commercial segment dominated the Air Data Systems Market with approximately 54.29% share in 2025, while the Military segment is the fastest growing with a CAGR of approximately 9.8%.
By Platform, commercial aircraft dominates, UAVs grow fastest
Commercial aircraft held the largest share of the platform segment in 2025, reflecting the sheer scale of the global commercial fleet and the mandatory redundant air data systems every passenger aircraft carries. Fleet modernization programs across major airlines continue driving steady replacement and upgrade demand within this platform category, keeping it the largest and most consistent source of overall market revenue.
UAVs are growing fastest as both military and commercial drone programs increasingly specify dedicated, miniaturized air data sensing packages rather than adapting equipment designed for manned aircraft. Rising defense modernization investment in unmanned platforms, combined with expanding commercial drone applications in logistics and inspection, is pulling this platform category's growth well ahead of the broader market.
By Product Type, pitot tubes & probes dominates, multi-function air data systems grows fastest
Pitot tubes and probes held the largest share of the product-type segment in 2025, remaining the most fundamental and universally required air data sensing component across virtually every fixed-wing aircraft in service. Their essential role in every aircraft's basic airspeed measurement, combined with periodic replacement needs due to wear and damage, keeps this the largest single product category.
Multi-function air data systems are growing fastest as integrated solutions that combine sensing probes, pressure sensors, and air data computer processing into a single unit gain preference over separately sourced components. That integration reduces installation complexity and improves data consistency across an aircraft's systems, giving airframers and operators a clear incentive to specify multi-function systems on new and retrofit programs alike.
By Component, sensors dominates, electronic unit grows fastest
Sensors held the largest share of the component segment in 2025, covering the pressure, temperature, and angle-of-attack sensing elements that form the foundation of any air data measurement. Their direct exposure to the harsh external flight environment also means sensors typically require more frequent replacement and calibration than other air data system components.
Electronic units are growing fastest as AI-driven predictive maintenance modules and increasingly sophisticated data processing capability get integrated directly into air data computer hardware. That shift toward smarter, more capable electronic processing is pulling investment and revenue growth toward this component category faster than the more mature sensor and probe segments are growing.
By Technology, conventional/mechanical dominates, smart/digital grows fastest
Conventional and mechanical air data technology held the larger share of the technology segment in 2025, reflecting the still-substantial installed base of older aircraft running proven, certified pneumatic and mechanical sensing systems. Airlines and operators often continue running these systems for the remainder of an airframe's service life rather than undertaking a costly, non-mandatory upgrade to digital alternatives.
Smart and digital air data systems are growing fastest as MEMS-based sensor technology and advanced algorithms enable meaningfully improved accuracy, integration capability, and real-time data processing over legacy mechanical designs. New aircraft programs are increasingly specifying digital air data systems from the outset, and that design-in preference is pulling this technology category's growth well ahead of the broader, more mature conventional segment.
By Application, commercial dominates, military grows fastest
Commercial applications accounted for the larger share of the application segment in 2025, driven by the scale of global commercial aviation and the steady replacement and modernization cycle across passenger and cargo airline fleets worldwide. Rising global air travel demand continues supporting sustained commercial aircraft production and, with it, steady air data system demand.
Military applications are the fastest-growing category as defense modernization programs increasingly prioritize both next-generation manned fighter platforms and expanding unmanned aerial vehicle fleets, both of which require rugged, high-reliability air data sensing packages. Government defense budgets committed to multi-year modernization programs give this application category a particularly stable, long-duration growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.0% |
|
Europe |
France |
24.0% |
|
Asia Pacific |
China |
38.0% |
|
Latin America |
Brazil |
36.0% |
|
Middle East & Africa |
UAE |
30.0% |
North America Air Data Systems Market Insights
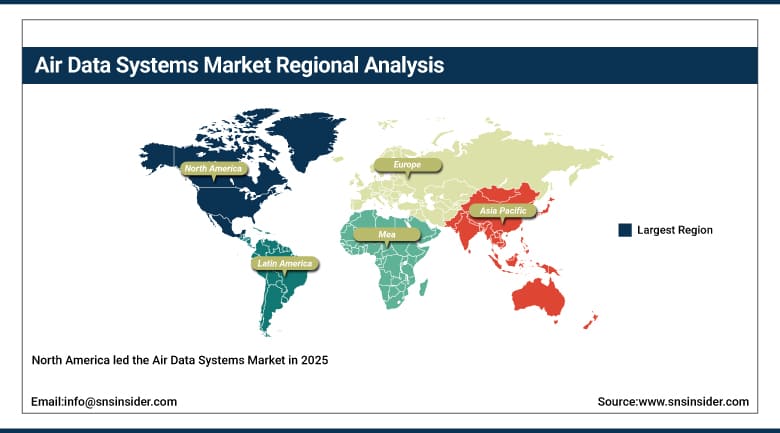
North America led the Air Data Systems Market in 2025, anchored by the United States' concentration of leading air data system manufacturers and deep military and commercial aerospace procurement activity. Long-established relationships between domestic suppliers and major U.S. airframers, combined with substantial defense modernization spending, keep the region at the forefront of both technology development and adoption.
Canada contributes a meaningful share through its own aerospace manufacturing and defense sectors, while Mexico's market remains largely nascent, dependent on components and technology sourced from its northern neighbor. Cross-border supply chains and defense procurement relationships tie much of North American demand together, with major suppliers typically serving both markets through shared production capacity.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Air Data Systems Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, driven by civil aviation fleet recovery, China's COMAC C919 commercial aircraft program scaling up production, and expanding investment in unmanned aerial systems across the region. Rising domestic aerospace manufacturing capability is pushing regional suppliers to build higher-reliability air data packages that can compete with established Western manufacturers.
South Korea's KF-21 indigenous fighter program and aggressive unmanned aerial vehicle roadmap are driving demand for rugged, miniaturized air data sensing architectures, while Japan and India represent additional growing sources of both commercial and defense demand. China's expanding stake in global production reflects the country's growing self-sufficiency ambitions in high-reliability aerospace components.
Europe Air Data Systems Market Insights
Europe represents a mature, technically advanced air data systems market, anchored by France's position as home to Airbus and a deep base of aerospace component suppliers. Strong European aerospace engineering expertise and established relationships between domestic suppliers and both Airbus and regional defense programs support the region's continued technology leadership.
The United Kingdom and Germany contribute significant aerospace manufacturing and defense procurement activity as well, with both countries hosting major aerospace component suppliers and flight test facilities. Continued European defense modernization spending and civil aviation fleet renewal are both reinforcing steady regional demand growth.
MEA & Latin America Air Data Systems Market Insights
The Middle East and Africa host a smaller but strategically significant share of the air data systems market, with the UAE driving demand through substantial defense procurement and growing commercial aviation fleet expansion tied to the region's position as a global aviation hub. Growth elsewhere in the region remains tied closely to the pace of broader aerospace and defense infrastructure development.
Latin America remains an early-stage market, with Brazil showing the clearest interest given its established aerospace manufacturing base centered around Embraer's commercial and regional aircraft programs. Argentina and Mexico are following developments in more advanced markets closely, though commercial air data systems manufacturing activity across the broader region remains limited for now.
Market Dynamics
Growth Drivers: Fleet modernization and defense procurement fueling adoption
Ongoing fleet modernization across commercial and military aviation is one of the clearest forces behind rising air data systems demand, as operators replace aging mechanical and analog systems with digital alternatives offering better accuracy, reliability, and integration with modern avionics suites. That modernization cycle gives the market a dependable, replacement-driven revenue base independent of new aircraft production volume alone.
Expanding defense procurement and unmanned aerial vehicle investment add a second major driver, as military modernization programs worldwide prioritize both next-generation manned platforms and rapidly growing drone fleets that require dedicated, high-reliability air data sensing packages. Multi-year government defense budgets committed to these programs give this driver a particularly stable, long-duration growth trajectory relative to more cyclical commercial aviation spending.
Restraints: Certification complexity and long qualification cycles limiting adoption speed
The rigorous certification requirements air data systems must meet, given their safety-critical role in flight control, add real cost and timeline complexity for manufacturers introducing new sensor or digital technology. That certification burden can slow the pace at which even genuinely superior new technology reaches commercial deployment, since airlines and regulators alike remain understandably cautious about safety-critical system changes.
Long qualification cycles for new aircraft programs add a further restraint, since air data system suppliers must often commit engineering resources years before a platform enters production, with no guarantee the program will proceed on its original timeline or scale. That extended, uncertain qualification process can strain smaller suppliers' resources more than it does the largest, most diversified manufacturers.
Opportunities: Digital sensor upgrades and UAV-specific system design opening new growth avenues
Retrofitting existing aircraft fleets with smart, MEMS-based digital sensors offers manufacturers a genuine path to capturing steady upgrade revenue from operators seeking improved accuracy and predictive maintenance capability without waiting for full fleet replacement. Companies that build strong retrofit-focused product lines are positioned to capture this modernization-driven demand across a large existing installed base.
UAV-specific air data system design represents a second significant opportunity, as expanding drone applications across military, commercial, and logistics sectors create demand for miniaturized, purpose-built sensing packages that traditional manned-aircraft air data systems weren't designed to serve. Manufacturers that build genuine UAV-focused engineering expertise are positioned to capture disproportionate growth as unmanned aviation continues expanding globally.
Recent Developments:
-
2024: Safran announced a strategic collaboration with L3Harris Technologies to co-develop and manufacture integrated air data systems.
-
2025: Honeywell continued expanding its Air Data Module lineup, integrating analog-to-digital converters directly with third-party probes to reduce system weight and plumbing complexity.
-
2025: Multiple air data system suppliers accelerated integration of smart sensors and IoT capabilities into pitot probes, improving performance monitoring and accuracy across both commercial and military aircraft.
-
2025: Leading aerospace sensor manufacturers continued pursuing M&A activity to consolidate flight-data analytics capabilities, while forging partnerships with satellite-communication providers to enhance real-time telemetry streams.
Air Data Systems Market Key Players
-
Honeywell International Inc.
-
RTX Corporation (Collins Aerospace)
-
Curtiss-Wright Corporation
-
AMETEK, Inc.
-
Thales Group
-
Safran S.A.
-
Meggitt PLC
-
Parker Hannifin Corporation
-
Ultra Electronics Holdings plc
-
Ducommun Incorporated
-
Esterline Technologies
-
GE Aerospace
-
L3Harris Technologies, Inc.
-
Elbit Systems Ltd.
-
BAE Systems plc
-
Garmin Ltd.
-
Innovative Solutions and Support, Inc.
-
TE Connectivity Ltd.
-
Woodward, Inc.
-
Moog Inc.
Air Data Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 950.0 Million |
| Market Size by 2035 | USD 2.15 Billion |
| CAGR | CAGR of 8.5% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Platform (Commercial Aircraft, Military Aircraft, Business Jets, Helicopters, UAVs) • by Product Type (Air Data Computers, Pitot Tubes & Probes, Sensors, Data Recorders, Multi-Function Air Data Systems • by Component (Electronic Unit, Probes, Sensors) • byTechnology (Conventional/Mechanical, Smart/Digital), Application (Commercial, Military) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Honeywell International Inc., RTX Corporation (Collins Aerospace), Curtiss-Wright Corporation, AMETEK, Inc., Thales Group, Safran S.A., Meggitt PLC, Parker Hannifin Corporation, Ultra Electronics Holdings plc, Ducommun Incorporated, Esterline Technologies, GE Aerospace, L3Harris Technologies, Inc., Elbit Systems Ltd., BAE Systems plc, Garmin Ltd., Innovative Solutions and Support, Inc., TE Connectivity Ltd., Woodward, Inc., Moog Inc. |
Frequently Asked Questions
Key players in the Air Data Systems Market include Honeywell International Inc., RTX Corporation (Collins Aerospace), Curtiss-Wright Corporation, AMETEK, Inc., and Thales Group, among others.
Key opportunities in the Air Data Systems Market include retrofitting existing aircraft fleets with smart, MEMS-based digital sensors and UAV-specific air data system design for military, commercial, and logistics applications.
The market is driven by ongoing fleet modernization across commercial and military aviation, along with expanding defense procurement and unmanned aerial vehicle investment.
The Commercial Aircraft segment dominated the Air Data Systems Market, accounting for approximately 46.18% market share.
The North America region dominated the Air Data Systems Market in 2025 with an approximately 34.0% share, driven by a concentration of leading manufacturers and deep military and commercial aerospace procurement activity.
