Clinical Trial Investigative Site Network Market is entering a period of continued expansion as pharmaceutical and biotechnology companies seek broader patient access, faster enrollment, and more specialized infrastructure for increasingly complex studies. Growing development activity in precision medicine, oncology, rare diseases, and advanced therapies is increasing demand for organized networks capable of supporting sponsors across multiple locations.
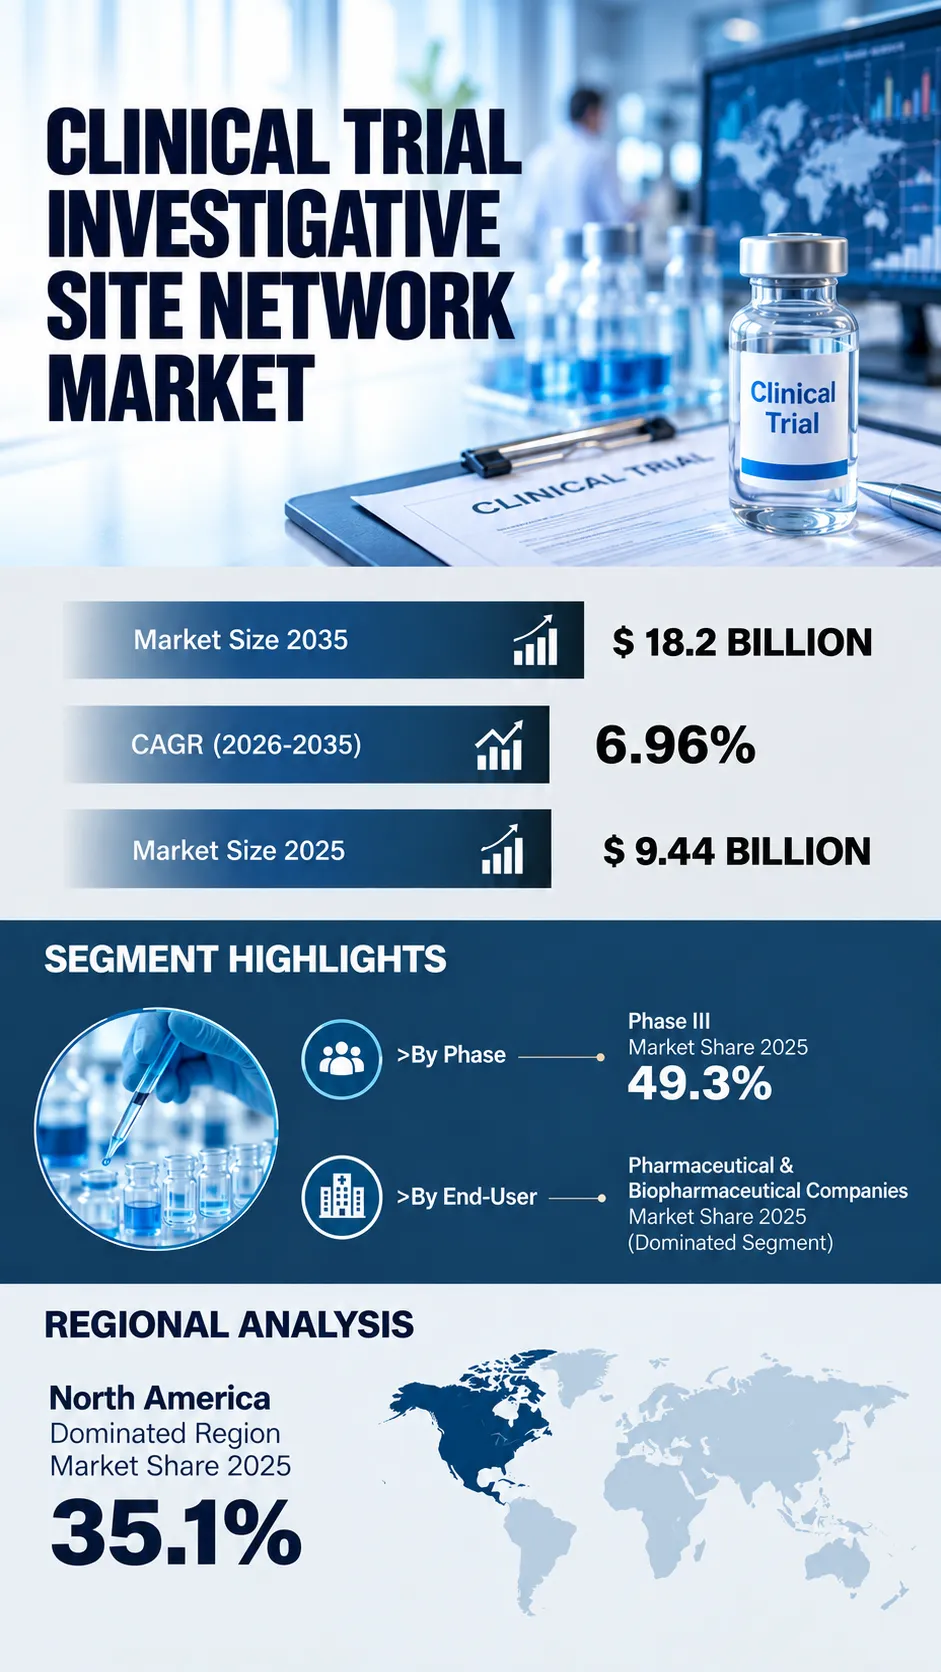
According to a recent study by SNS Insider, the global Clinical Trial Investigative Site Network Market size valued at USD 9.44 billion in 2025, is anticipated to grow to USD 18.2 billion by 2035, registering a CAGR of 6.96% over the 2026–2035 forecast period. The market is also being reshaped by decentralized trial technologies, data-driven recruitment tools, and greater use of specialized commercial research organizations.
Complex Drug Development Raises Demand for Specialized Sites
Increasing complexity associated with clinical investigations is occurring due to the drive toward developing novel pharmaceuticals for smaller patient subpopulations utilizing ever-more-complex biological mechanisms. Investigator networks provide sponsors access to research staff, patient registries, regulatory processes, and logistical operations infrastructure through numerous sites.
Pharmaceutical innovation growth has been fueling this trend, with over 450,000 active clinical investigations having been registered within ClinicalTrials.gov in 2023 based on figures cited during market assessment, while U.S.-based biopharmaceutical companies invested a total of USD 102 billion into R&D activities in 2023 as reported by PhRMA.
To Get Detailed Insights on the Clinical Trial Investigative Site Network Market – Request a Sample Report
Phase III Studies Remain the Largest Revenue Contributor
By trial phase, Phase III accounted for 49.3% of market revenue in 2025. Large pivotal studies typically require extensive patient recruitment and geographically distributed research locations, creating substantial demand for established site networks.
Phase I is projected to register the fastest growth as early-stage development expands across oncology, targeted therapies, cell therapies, and gene therapies. The FDA's Center for Drug Evaluation and Research recorded 1,756 new INDs in FY2023, providing an indication of the volume of development programs entering the clinical pathway.
By therapeutic area, oncology held a 32.1% share in 2025. The specialized eligibility criteria, biomarker testing, treatment histories, and safety monitoring associated with cancer trials create demand for sites with appropriate clinical capabilities. Pain management is expected to record the fastest growth among therapeutic areas.
Pharmaceutical and biopharmaceutical companies remained the leading end-user group, while CROs are expected to expand at the fastest pace as sponsors increasingly outsource portions of trial execution and recruitment.
Digital Recruitment and Decentralized Trials Reshape Operations
Technology is becoming an increasingly important component of site-network management. Artificial intelligence can help identify potential participants by comparing patient information with study eligibility requirements, while electronic records and patient databases can improve recruitment workflows.
Decentralized clinical trial models are also broadening the operational role of research sites. Remote consultations, home-based sample collection, wearable devices, and electronic patient-reported outcomes can complement conventional site visits, allowing networks to support participants beyond traditional clinical facilities.
Private-equity-backed consolidation is another notable development, creating larger organizations with shared technology platforms, centralized regulatory functions, and standardized operating procedures.
North America Leads While Asia Pacific Expands
North America accounted for approximately 35.1% of global revenue in 2025, making it the largest regional market. The United States contributed approximately 93% of North American revenue, supported by substantial pharmaceutical research activity and a mature commercial clinical research infrastructure.
The U.S. Clinical Trial Investigative Site Network Market was valued at USD 3.22 billion in 2025 and is projected to reach USD 6.20 billion by 2035, advancing at a 6.75% CAGR.
Asia Pacific is projected to be the fastest-growing regional market. China represented approximately 38% of regional revenue, while expanding research infrastructure in India and other Asian economies is increasing their participation in multinational studies.
In Europe, the United Kingdom accounted for 28% of regional revenue. Israel represented 40% of Middle East & Africa revenue, while Brazil accounted for 52% of Latin America's regional market.
Rare Diseases Create New Network Opportunities
Rare-disease research is creating demand for sites with specialized investigators, patient registries, diagnostic capabilities, and experience with complex protocols. The FDA granted 295 orphan drug designations in 2025, highlighting the continued development activity surrounding treatments for uncommon conditions.
AI-assisted recruitment represents another emerging opportunity, particularly where eligibility criteria are narrow and potential participants are geographically dispersed. Networks capable of combining clinical expertise with patient-identification technologies may increasingly become part of sponsors' recruitment strategies.
Industry Developments Reflect Ongoing Consolidation
Recent activity includes Velocity Clinical Research's 2026 expansion to 75 investigative sites through its acquisition of ClinPoint Trials' Southeast network. ICON plc introduced PRA Site Solutions in 2025, combining site identification, feasibility, management, and recruitment capabilities. The FDA's 2025 updated guidance on diversity in clinical trials has also increased attention on reaching broader patient populations through community and geographically diverse research locations.
Some key players within the Clinical Trial Investigative Site Network Market include IQVIA Holdings Inc., ICON plc, Labcorp Drug Development, Velocity Clinical Research, WCG Clinical LLC, Elligo Health Research Inc., Clinipace Ltd., Meridian Clinical Research, Javara Inc., ClinChoice Ltd., Novatek International, Syneos Health Inc., Premier Research Group Ltd., Worldwide Clinical Trials LLC, Vericel Corporation, HCA Healthcare Inc., Inovalon Holdings Inc., Roper Technologies Inc. (Accelrys), Medpace Holdings Inc., and BioClinica Inc.
An SNS Insider analyst Parry Kardani commented, "The clinical research site environment is evolving alongside pharmaceutical development, with specialized patient access, digital recruitment, decentralized trial capabilities, and operational standardization becoming increasingly important to sponsors managing complex studies."
About the Author
Get in touch