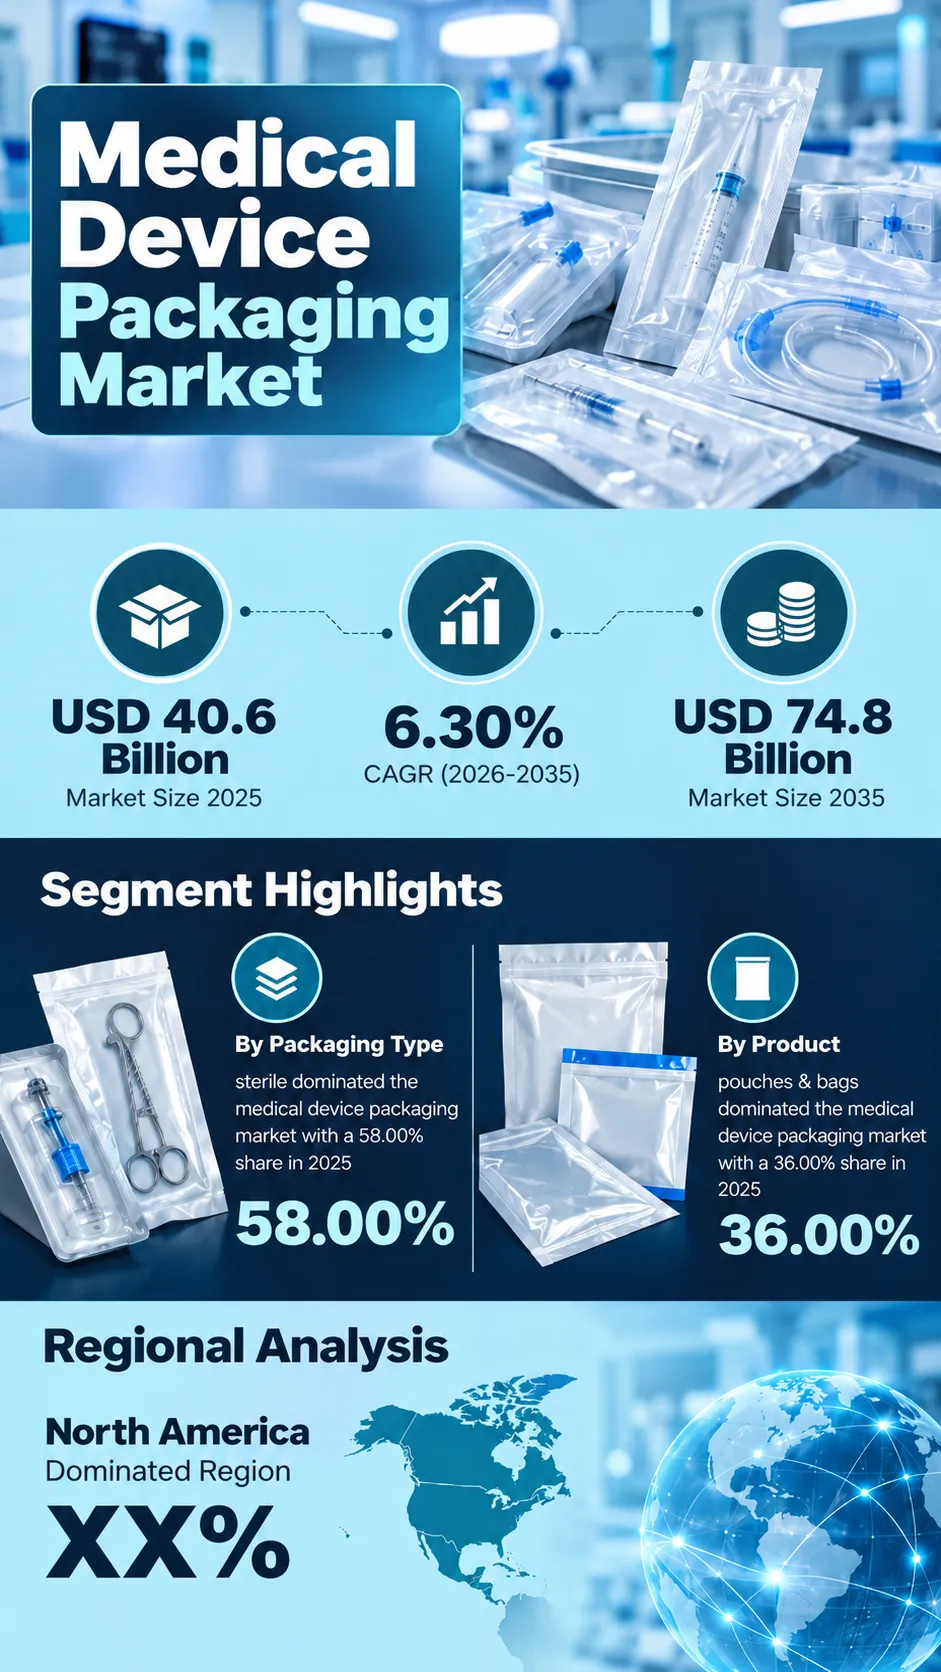
The global Medical Device Packaging Market is set for significant expansion as surgical procedure volumes and single-use device adoption continue to reshape healthcare packaging worldwide. “According to a recent study by SNS Insider, the global Medical Device Packaging Market size valued at USD 40.6 billion in 2025, is anticipated to grow to USD 74.8 billion by 2035, registering a CAGR of 6.30% over the 2026–2035 forecast period.”
There have been notable changes within sterile barrier and traceability technology over time, due to which many manufacturers who aim at improving compliance and patient safety can take advantage of this trend. This includes the need for more advanced smart packaging and recyclable mono-material techniques that will provide medical device manufacturers with the ability to achieve validated sterility while meeting sustainability goals. This applies in situations where medical device packaging supports surgical equipment, disposable consumables, and diagnostic device applications. Manufacturers are constantly working hard to ensure that their packaging products perform better than before in order to meet various sterility and traceability requirements.
To Get Detailed Insights on the Medical Device Packaging Market – Request a Sample Report
Smart Packaging Technology and Recyclable Materials Create New Demand
The medical device packaging market has evolved from conventional sterile barrier systems to increasingly sophisticated, technology-enhanced and sustainable packaging solutions. The growing investment in RFID-enabled smart labels, recyclable mono-material development, and cleanroom manufacturing capacity across manufacturers of all sizes has required the development of more capable and compliant medical device packaging products.
New technology and material innovations can increase traceability, improve sterile barrier sustainability, and allow for expansion into increasingly diverse surgical, diagnostic, and disposable consumable applications. This gives healthcare providers and device manufacturers the possibility to achieve validated compliance while meeting growing environmental sustainability expectations.
Medical device packaging manufacturers, healthcare providers, and regulatory bodies are increasingly cooperating thanks to the growing interest in developing future solutions for compliant, technology-enhanced sterile packaging.
Key Market Findings Highlight High-Growth Segments
The sterile packaging segment dominated all categories in the medical device packaging market share with a 58% share in 2025 due to surgical instruments and implants requiring validated barrier systems. The fastest growing category is expected to be non-sterile packaging which will grow at a CAGR of 7.60% through 2035, owing to rising home healthcare usage and reusable device categories.
By product, pouches and bags dominated the market with a 36% share in 2025 due to versatile, cost-effective sterile barrier performance. Trays will see the fastest growth in revenue generation at a 7.20% CAGR, driven by growing demand for enhanced device protection and automated sterilization compatibility.
Based on material, plastic held a 54.3% share in 2025 thanks to established barrier performance and sterilization compatibility. On the other hand, paper and paperboard will be the segment recording the fastest revenue growth at a 6.60% CAGR, supported by growing development of recyclable mono-material solutions.
Distributive end-use trends are changing as well. Surgical equipment accounted for a 41.6% revenue share owing to the rise in surgical procedures worldwide. But disposable consumables will turn out to be the fastest-growing end-use category through 2035, on the back of expanding single-use medical device adoption.
Sterile Barrier Integrity, Traceability, and Sustainability Gain Importance
In this regard, healthcare providers and device manufacturers have been looking at medical device packaging products that would deliver more consistent sterile barrier integrity while requiring greater traceability and sustainability credentials.
Innovation in RFID-enabled smart labels, recyclable mono-material development, and cleanroom manufacturing capacity has been making it possible for companies to come up with products that appeal to increasingly compliance-focused and sustainability-conscious healthcare manufacturers. In addition to that, increasing emphasis on anti-counterfeit serialization is also making it possible for manufacturers to find solutions that enhance patient safety and supply chain visibility. Such trends are likely to become even more prominent in the future.
North America Emerges as the Largest Market Amid Rising Surgical Procedure Volumes
The North America region represented a significant share of regional market revenue in 2025, driven by rising surgical procedure volumes and stringent FDA sterility-assurance requirements. On the other hand, Asia Pacific is expected to witness the fastest growth rate during the forecast period through 2035, propelled by expanding healthcare infrastructure investment and rising medical device manufacturing capacity.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on smart packaging technology and recyclable materials as well as forming partnerships in order to enhance their position in the industry. Some of the major companies that operate in the global medical device packaging market are Amcor, AptarGroup, Becton Dickinson, Cardinal Health, DuPont de Nemours, Nelipak Corporation, Oliver Healthcare Packaging, Coveris Holdings, Bemis Company, and WestRock Company.
An SNS Insider analyst Himanshu Sharma commented, "The growing convergence of surgical procedure growth and single-use device adoption is creating sustained demand for validated, technology-enhanced sterile packaging. Manufacturers that successfully combine smart traceability innovation, recyclable material development, and cleanroom capacity expansion will be best positioned to capitalize on emerging opportunities across surgical, diagnostic, and disposable consumable segments."
About the Author
Get in touch