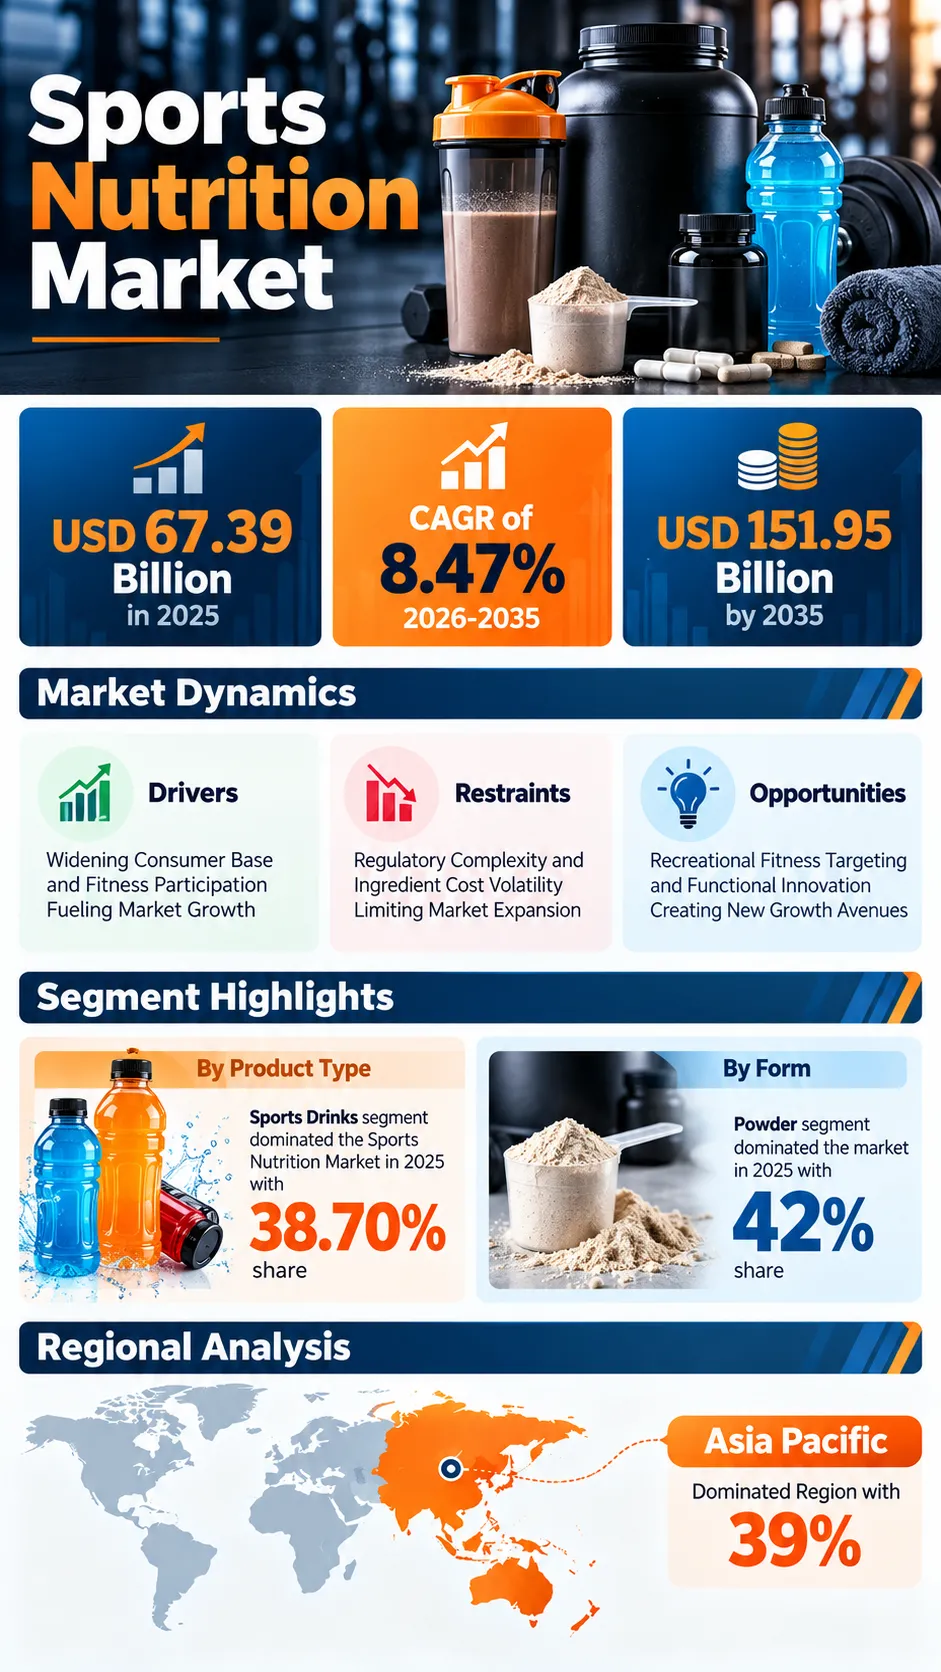
The global Sports Nutrition Market is on a steady growth path through 2035, as the category's consumer base keeps widening well beyond its traditional competitive-athlete roots. “According to a recent study by SNS Insider, the global Sports Nutrition Market size valued at USD 67.39 billion in 2025, is anticipated to grow to USD 151.95 billion by 2035, registering a CAGR of 8.47% over the 2026-2035 forecast period.”
Sports nutrition has quietly outgrown its own name over the past decade, the products once sold almost exclusively to competitive athletes and bodybuilders now reach recreational runners, casual gym-goers, and consumers who simply want better hydration and recovery without any competitive ambition at all. That broadening audience is reshaping everything from flavor development to where these products actually sit on store shelves.
Format innovation has followed the audience just as much as ingredient science has, ready-to-drink protein, functional sports drinks, and creatine gummies are pulling in buyers who never would have bought a tub of powder in the first place.
To Get Detailed Insights on the Sports Nutrition Market – Request a Sample Report
Creatine's Mainstream Crossover Reshapes Category Growth
Creatine has done more than almost any other single ingredient to demonstrate how far sports nutrition can expand beyond its traditional athletic performance positioning, as growing clinical research into cognitive function and healthy aging pulls in an entirely new wellness-focused buyer base.
This crossover is changing how brands think about ingredient marketing more broadly, since positioning a product around multiple health benefits rather than pure athletic performance opens up a meaningfully larger addressable market.
Manufacturers investing in clinical research that supports these broader wellness claims are positioning themselves to capture demand well beyond the category's traditional gym-focused customer base.
Key Market Findings Highlight High-Growth Segments
Sports Drinks occupied the highest market share of 38.70% in 2025 due to wide availability of this product and low barriers of entry for non-professional users.
Creatine & Amino Acids is the most rapidly growing segment with CAGR of 9.35%. This is facilitated by the use of creatine in popular discussions on healthy aging and brain function.
By application, pre-workout led with 35% share in 2025, while post-workout is growing fastest, at a 8.96% CAGR, as recovery science gains mainstream consumer attention.
Active lifestyle consumers remained the largest end-user segment at 38% share, but recreational sports participants are climbing fastest, at a 9.15% CAGR, as casual fitness culture continues expanding the category's addressable audience.
Clinical Credibility and Format Convenience Anchor Competitive Positioning
Brands are increasingly being evaluated on clinical credibility and format convenience simultaneously, a combination that used to be treated as largely separate purchasing considerations.
Investment in functional ingredient research and convenience-focused formats like ready-to-drink protein is becoming a genuine competitive differentiator, while brands relying on generic formulations in traditional powder form increasingly compete only on price.
This trend is expected to accelerate further as the category's consumer base continues widening beyond its traditional athletic core.
Asia Pacific Leads on Both Scale and Growth
Asia Pacific holds both the largest share of global market revenue and the fastest growth rate, driven by rising disposable incomes, expanding urban populations, and growing sports participation across China, India, and Southeast Asia. North America holds a steady, mature share as well, anchored by decades of established gym culture and deep retail distribution.
Europe holds a meaningful, mature share too, shaped by strong fitness culture and the region's comparatively strict regulatory frameworks around health claims and novel ingredients.
Leading Companies Drive Innovation and Competition
Competition in this market is playing out across format innovation, functional ingredient research, and brand positioning nearly as much as on price and distribution reach, with challenger brands increasingly pulling share from established legacy players.
Some of the major companies that operate in the global sports nutrition market are Glanbia plc, BellRing Brands, Inc., Iovate Health Sciences International Inc., Abbott Laboratories, Clif Bar & Company, The Coca-Cola Company, Quest Nutrition LLC, PepsiCo, Inc.
An SNS Insider Analyst Parry Kardani commented, “Sports nutrition has moved well past being a niche category for competitive athletes, brands now need to win on format convenience, functional credibility, and broad wellness appeal all at once, and the companies capturing the fastest-growing parts of this market are the ones treating recreational and casual fitness consumers as a genuine growth opportunity rather than an afterthought. As fitness participation keeps expanding globally, the bar for what counts as a competitive sports nutrition product is only going to keep rising.”
About the Author

Get in touch