
3nm Process Technology for Semiconductor Market Report Scope & Overview:
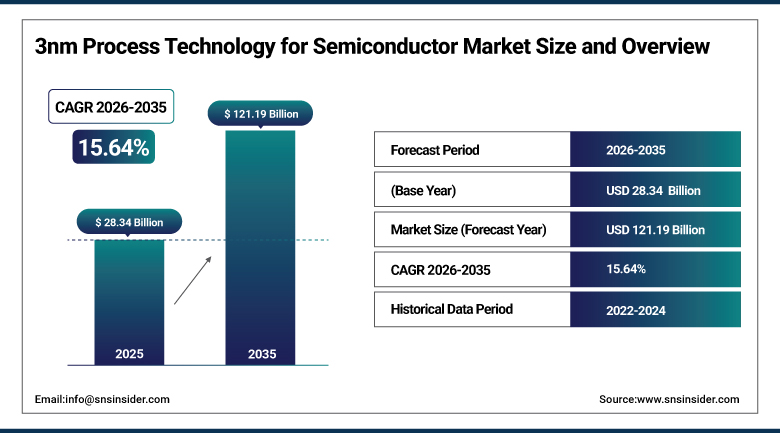
The 3nm Process Technology for Semiconductor Market was valued at USD 28.34 Billion in 2025 and is expected to reach USD 121.19 Billion by 2035, growing at a CAGR of 15.64% from 2026-2035.
The 3nm Process Technology for Semiconductor Market covers the wafer fabrication of chips built on 3-nanometer-class nodes, including FinFET and gate-all-around variants. These chips power flagship smartphones, notebook processors, graphics processors, data center accelerators and custom artificial intelligence silicon, offering higher transistor density, better performance and lower power than 5nm and 7nm designs. Demand from mobile platforms and artificial intelligence computing, together with heavy investment in extreme ultraviolet lithography and advanced packaging, is shaping the market through 2035. Suppliers range from the leading foundries to chip designers, design software vendors, intellectual property providers and the equipment makers that supply lithography, deposition, etch and inspection tools.
⮞The World Semiconductor Trade Statistics organization reported in August 2026 that global semiconductor sales reached USD 702 Billion in the first half of 2026, up 102% year on year.
To Get more information 3nm Process Technology for Semiconductor Market - Request Free Sample Report
3nm Process Technology for Semiconductor Market Trends
-
Enhanced 3nm variants with higher performance and improved power efficiency are being adopted by smartphone processors and data center accelerators. Designers value the extra performance without moving to a new node.
-
Custom artificial intelligence chips from cloud providers and fabless designers are being taped out on 3nm to raise compute per watt. Such programs create anchor demand for foundries.
-
Advanced packaging, including large silicon interposers and stacked memory, is being paired with 3nm logic to scale accelerator performance. Packaging capacity has become as scarce as wafer capacity.
-
Foundries are adding 3nm capacity outside Taiwan, with new fabs planned in the United States and Japan to diversify supply. These sites reduce risks from concentrated production.
-
Rising wafer prices and tight supply are pushing designers to reserve capacity years ahead and to share costs through long-term agreements. Long-term agreements are becoming standard.
U.S. 3nm Process Technology for Semiconductor Market Outlook
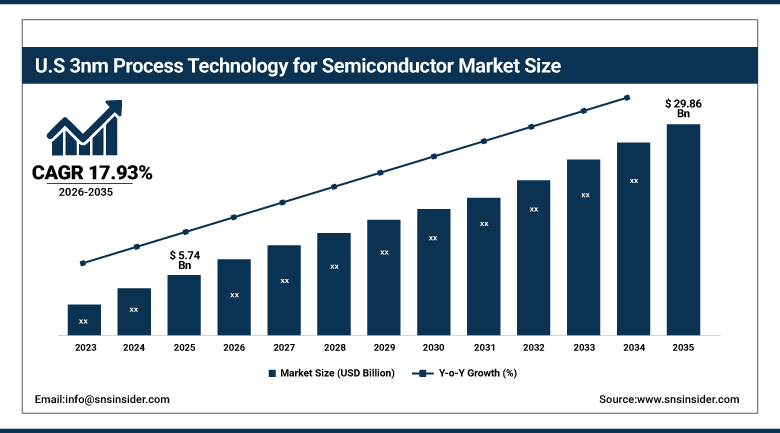
The U.S. 3nm Process Technology for Semiconductor Market was valued at USD 5.74 Billion in 2025 and is expected to reach USD 29.86 Billion by 2035, growing at a CAGR of 17.93% from 2026-2035.
The U.S. 3nm Process Technology for Semiconductor Market is the largest national market in North America, led by the world’s biggest fabless chip designers and a growing base of advanced manufacturing sites. American designers of smartphone processors, graphics processors and custom accelerators account for a large share of global 3nm wafer demand, while new fabs in Arizona are bringing 3nm production closer to these customers. Federal incentives and trade measures encourage local capacity through 2035. Partnerships between designers, foundries and packaging houses are shortening the time from tape-out to volume. Strong venture funding supports custom chip start-ups. Utilities and state agencies are supporting the build-out of power and water supply.
⮞The White House proclaimed on 14 January 2026 a 25% Section 232 tariff on certain advanced computing chips, effective 15 January 2026.
3nm Process Technology for Semiconductor Market Segment Analysis
-
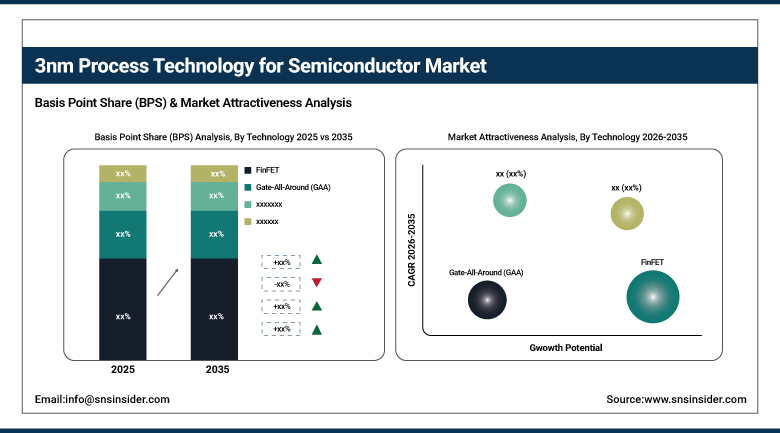
By Technology, the FinFET segment dominated the 3nm Process Technology for Semiconductor Market with approximately 68.43% share in 2025, while the Gate-All-Around (GAA) segment is the fastest growing with a CAGR of approximately 29.64%.
-
By Application, the Consumer Electronics segment dominated the 3nm Process Technology for Semiconductor Market with approximately 42.86% share in 2025, while the High-Performance Computing and Data Centers segment is the fastest growing with a CAGR of approximately 21.37%.
-
By Chip Type, the CPUs and Application Processors segment dominated the 3nm Process Technology for Semiconductor Market with approximately 41.53% share in 2025, while the ASICs and AI Accelerators segment is the fastest growing with a CAGR of approximately 24.18%.
-
By End User, the Fabless Companies segment dominated the 3nm Process Technology for Semiconductor Market with approximately 64.28% share in 2025, and is also the fastest growing with a CAGR of approximately 17.52%.
By Technology, FinFET Dominates the 3nm Process Technology for Semiconductor Market and Gate-All-Around Grows Fastest
FinFET holds approximately 68.43% of the 3nm Process Technology for Semiconductor Market in 2025. The leading foundry runs its 3nm family on refined FinFET transistors, which offer proven yields, mature design kits and broad customer support. Smartphone processors, notebook chips and accelerators already in volume production rely on these nodes, so FinFET captures the bulk of wafer revenue. Refinements such as enhanced performance variants allow designers to improve products without a full redesign. Long-lived process families spread development costs across many products.
Gate-all-around transistors are the fastest growing technology, with a CAGR of approximately 29.64% during 2026-2035. Nanosheet structures surround the channel on all sides, improving electrostatic control and allowing lower voltage operation at smaller dimensions. One major foundry introduced GAA at 3nm, and the approach is becoming the standard for 2nm and beyond, drawing attention from designers planning future chips. Capital intensity is high, since each new transistor generation requires new tools, masks and process development. Yield maturity is the key hurdle, and customers watch it closely.
⮞The Korean Ministry of Trade, Industry and Resources reported on 1 October 2026 that September chip exports reached USD 60.3 Billion, up 263% year on year, the first month above USD 60 Billion.
By Application, Consumer Electronics Dominates the 3nm Process Technology for Semiconductor Market and High-Performance Computing and Data Centers Grows Fastest
Consumer electronics account for approximately 42.86% of the market in 2025. Flagship smartphones and notebooks were among the first products to adopt 3nm, because their processors benefit from higher performance and longer battery life. Annual upgrade cycles by major device makers create large, predictable wafer orders that keep this segment at the top of the application ranking. Notebook processors with built-in neural engines widen the base of 3nm devices. Wearables and tablets also adopt the node for premium models. Product launches are timed to holiday seasons. Demand also rises as artificial intelligence features reach midrange devices.
High-performance computing and data centers are the fastest growing application, with a CAGR of approximately 21.37% during 2026-2035. Artificial intelligence training and inference chips need maximum transistor density and energy efficiency, and cloud providers are booking 3nm capacity for custom accelerators. Automotive, telecom and other uses add smaller volumes, with automotive adoption growing as advanced driver assistance computers become more complex. Networking and storage controllers for data centers add to the pull for leading-edge capacity. Co-design with software teams helps maximize efficiency.
⮞SEMI reported around September 2026 that global semiconductor equipment billings increased 23% year on year in the second quarter of 2026.
By Chip Type, CPUs and Application Processors Dominate the 3nm Process Technology for Semiconductor Market and ASICs and AI Accelerators Grow Fastest
CPUs and application processors hold approximately 41.53% of the market in 2025. Mobile system-on-chip designs and notebook processors were the first volume products on 3nm, and several vendors now ship multiple generations. Their large die sizes and repeat annual launches generate significant wafer demand, and the segment benefits from established design flows and strong yields. Repeat orders from the same customers each year give foundries clear production visibility. Strong software ecosystems reinforce their position. Compute-intensive games push graphics performance. Product refreshes arrive on a yearly rhythm.
ASICs and artificial intelligence accelerators are the fastest growing chip type, with a CAGR of approximately 24.18% during 2026-2035. Cloud providers and networking vendors are designing custom silicon to cut costs and raise efficiency, often on 3nm to maximize compute per watt. Graphics processors remain a large category as data center and gaming demand rises, while field programmable gate arrays and other devices add smaller volumes. Advanced packaging capacity, particularly for large interposers, shapes how quickly these chips can ship. Memory bandwidth and packaging choices influence design wins.
⮞Taiwan’s Ministry of Economic Affairs reported on 22 September 2026 that August export orders reached a record USD 102.96 Billion, up 71.4% year on year.
By End User, Fabless Companies Dominate the 3nm Process Technology for Semiconductor Market and Also Grow Fastest
Fabless companies account for approximately 64.28% of the market in 2025. They design chips and rely on foundries for manufacturing, which makes them the principal buyers of 3nm wafers. Mobile platform vendors, graphics chip makers and custom silicon designers reserve foundry capacity well in advance and sign multi-year supply agreements to secure access to leading nodes. Volume discounts and prepayments are common features of these agreements. Few firms can match this scale of engineering resources. Many sign prepayment deals to lock capacity.
The same group is the fastest growing end user, with a CAGR of approximately 17.52% during 2026-2035, as cloud providers and system companies create in-house chip teams that behave like fabless firms. Integrated device manufacturers use 3nm for selected products and increasingly buy foundry capacity for the most advanced parts, while research institutions and others account for a small portion. Design service providers and intellectual property vendors help smaller entrants reach the node. Chip start-ups backed by large funding rounds target the node for flagship products. Venture-backed teams also target the node.
⮞Taiwan’s Directorate-General of Budget, Accounting and Statistics raised its 2026 economic growth forecast to 11.05% on 14 August 2026, the highest in 39 years, citing artificial intelligence demand.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
Taiwan |
54.37% |
|
North America |
United States |
88.46% |
|
Europe |
Germany |
27.43% |
|
Latin America |
Mexico |
46.21% |
|
Middle East & Africa |
United Arab Emirates |
41.28% |
Asia Pacific 3nm Process Technology for Semiconductor Market Insights
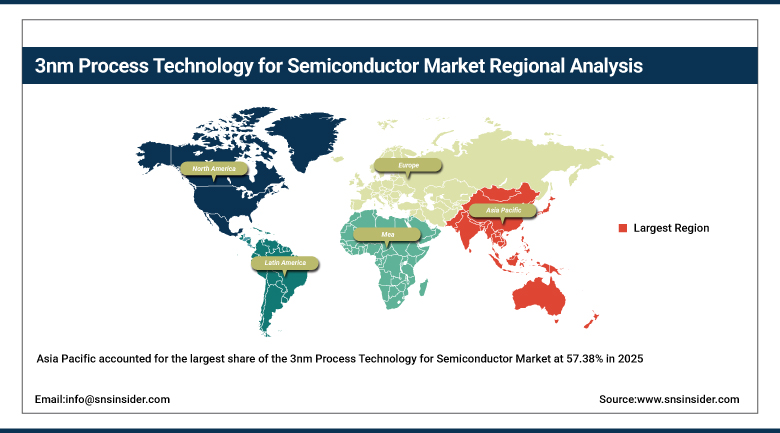
Asia Pacific accounted for the largest share of the 3nm Process Technology for Semiconductor Market at 57.38% in 2025. The region hosts the leading foundry in Taiwan, a second major foundry in South Korea and the largest concentrations of chip packaging, testing and device assembly. Almost every 3nm wafer in volume production today is made in Asia, which anchors supply. Government support for chip manufacturing in Taiwan, Korea and Japan keeps investment flowing. Dense supplier clusters shorten logistics for materials and tools.
Taiwan is the largest country market, with 54.37% of regional demand, because its leading foundry runs the bulk of global 3nm output. South Korea contributes through its own foundry and memory ecosystem, Japan supplies materials and equipment and is adding a 3nm-capable fab, and China builds chip design capacity despite export controls. India is the fastest growing country, helped by design and packaging incentives. Southeast Asian countries add testing and packaging operations that serve 3nm products. Wafer and packaging capacity remains concentrated in a handful of sites.
⮞China’s National Bureau of Statistics reported on 15 July 2026 that integrated circuit output reached 279.8 billion units in the first half of 2026, up 23.1% year on year.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America 3nm Process Technology for Semiconductor Market Insights
North America held approximately 22.89% of the 3nm Process Technology for Semiconductor Market in 2025 and is the fastest growing region, with a CAGR of 18.74% during 2026-2035. The United States contributes about 88.46% of regional demand, with Canada accounting for the balance. Chip designers, cloud operators and device makers headquartered here drive the largest share of 3nm wafer orders, and new local fabs are starting to build capacity. Federal incentives and tax credits for chip manufacturing support the build-out. Government support strengthens the local ecosystem.
Canada is a smaller but active market with artificial intelligence chip design firms and research clusters. Mexico, which belongs to Latin America, assembles servers and electronics that use 3nm chips. Government incentives for local fabs and advanced packaging in the United States are expected to lift regional production, and demand for custom accelerators keeps order books full. Research partnerships with universities support talent development for advanced fabs. Stable power and water supply are important siting factors. Talent pipelines are strengthening through new programs.
⮞The Semiconductor Industry Association reported on 7 October 2026 that global chip sales reached USD 159.7 Billion in August 2026, up 144.3% year on year, with sales surpassing USD 1 Trillion in the first eight months of the year.
Europe 3nm Process Technology for Semiconductor Market Insights
Europe held approximately 12.47% of the 3nm Process Technology for Semiconductor Market in 2025, with Germany, the Netherlands, France, the United Kingdom and Italy leading demand. The region does not manufacture 3nm chips at scale, but it is a major consumer through its automotive, industrial and telecom sectors, and it supplies the extreme ultraviolet lithography systems that make the node possible. Equipment exports to leading fabs in Asia and the United States are a major revenue source. Industrial policy aims to expand local design capabilities.
Germany is the largest market, with about 27.43% of regional demand, because of its carmakers and industrial electronics suppliers adopting advanced processors. The Netherlands is critical as the home of the leading lithography equipment maker, and the United Kingdom is a hub for processor architecture and design. Public programs aim to attract leading-edge manufacturing and strengthen design capabilities. Research centers in Belgium and France contribute process development expertise. Automotive chip demand is expected to rise steadily. Cooperation with Asian foundries is growing.
⮞The German electrical industry association ZVEI reported in July 2026, citing Destatis data, that real electronics production in Germany fell 5.4% year on year in May 2026.
MEA & Latin America 3nm Process Technology for Semiconductor Market Insights
The Middle East and Africa and Latin America together account for approximately 7.26% of the 3nm Process Technology for Semiconductor Market in 2025, with Latin America at 4.15% and the Middle East and Africa at 3.11%. In the Gulf, Saudi Arabia and the United Arab Emirates are investing in artificial intelligence data centers that import accelerators built on leading nodes, while Israel hosts major chip design centers of global vendors. Sovereign investment programs are funding large computing clusters that depend on imported advanced chips.
Latin America is led by Mexico and Brazil. Mexico has become a major assembly point for servers and computer equipment that carry leading-edge processors, creating indirect demand for 3nm chips. Brazil is building data center and design capacity, and Argentina and Chile contribute smaller volumes. The region imports virtually all advanced chips, so demand follows cloud and server investment. Regional distributors and system integrators play a central role in reaching enterprise customers. Public tenders for cloud infrastructure also influence volumes.
⮞Mexico’s national statistics agency INEGI reported in September 2026 that exports rose 29.3% in the first eight months of 2026, with non-automotive manufacturing exports up more than 63% in August, led by computer equipment.
Market Dynamics
Growth Drivers: Artificial Intelligence Computing and Flagship Mobile Demand Drive Growth in the 3nm Process Technology for Semiconductor Market
Artificial intelligence computing is the strongest force behind the 3nm Process Technology for Semiconductor Market. Training and inference accelerators need the highest transistor density and best energy efficiency available, and cloud providers are placing large, multi-year orders for leading-node capacity. Every performance gain translates into lower cost per computation, which justifies the premium paid for 3nm wafers. Model sizes continue to grow, which pushes operators to upgrade to the most efficient silicon available. Enterprise adoption of generative tools broadens the customer base.
Flagship mobile and notebook processors form the second driver. Device makers use the node to deliver faster graphics, on-device artificial intelligence features and longer battery life, and annual product cycles supply a steady wafer baseline. Rising selling prices of premium devices help cover the higher chip costs, which keeps designers migrating from 5nm to 3nm. Software features that run locally on devices raise the compute needed per chip. Premium positioning supports pricing power across product lines. Replacement cycles in data centers are shortening.
⮞Japan’s Ministry of Economy, Trade and Industry data compiled by JEITA showed that integrated circuit production in June 2026 reached 154.2% of the level a year earlier.
Restraints: High Wafer Costs and Capacity Constraints Restrain Growth in the 3nm Process Technology for Semiconductor Market
High wafer costs restrain the 3nm Process Technology for Semiconductor Market. A leading-edge design can cost hundreds of millions of dollars in engineering, masks and validation, and wafer prices have been rising. Only a limited group of companies can afford to build chips at this node, which narrows the customer base and delays adoption among mid-sized firms. Geopolitical tensions add risk to supply chains and raise the cost of building secondary capacity. Tool lead times lengthen the planning horizon. Packaging capacity also limits output.
Capacity constraints and yield challenges add further friction. Extreme ultraviolet tools are scarce, new fabs take years to build, and one foundry has struggled to win large customers because of yield issues. Trade restrictions, geopolitical risk around Taiwan and the shift of attention toward 2nm may also redirect investment and shorten the commercial life of the node. Power and water needs of new fabs also create permitting hurdles in some regions. Environmental permits add delays. Cost sharing is difficult for smaller firms.
⮞Malaysia’s Ministry of Investment, Trade and Industry reported on 18 September 2026 that total exports rose 45.5% year on year in August 2026 to RM191.05 Billion.
Opportunities: Custom Silicon and Regional Fab Expansion Create Opportunities in the 3nm Process Technology for Semiconductor Market
Custom silicon creates a major opportunity. Cloud providers, networking companies and carmakers are designing their own accelerators and system-on-chip products to lower cost and tune performance, and many target 3nm. Design service firms, intellectual property vendors and packaging specialists benefit as this wave of new designers needs support from concept to production. Chiplet architectures let designers combine 3nm compute dies with older nodes to lower costs. Open instruction set architectures broaden the pool of designers. Edge devices will also adopt the node.
Regional fab expansion forms a second opening. New 3nm capacity planned in Arizona, Japan and Taiwan will reduce supply concentration and give customers more choice. Equipment makers, materials suppliers and local design ecosystems stand to gain, and countries in Southeast Asia that already assemble and test advanced chips are positioning for deeper roles in the supply chain. Governments are offering subsidies, which lower the barrier for companies investing in new facilities. Joint ventures between foundries and customers are also emerging.
⮞Vietnam Customs data reported on 28 July 2026 showed that exports of computers and electronics reached USD 71.16 Billion in the first half of 2026, up 49.1%.
Recent Developments:
- 2025: NVIDIA taped out six chips of its Rubin architecture on TSMC’s N3P process, packaged with CoWoS-L advanced packaging, for next-generation AI computing platforms.
- 2025: Qualcomm unveiled the Snapdragon 8 Elite Gen 5 mobile platform, built on TSMC’s N3P 3nm process for flagship smartphones.
- 2026: TSMC raised capital spending to expand N3 capacity because of artificial intelligence demand, with a new Tainan 3nm fab due in the first half of 2027 and Arizona fab 2 and Kumamoto fab 2 following.
- 2026: ASML reported record third-quarter net sales of EUR 11.7 Billion, selling 113 new lithography systems, and said planned 2027 and 2028 supply would not fully meet demand.
3nm Process Technology for Semiconductor Market Key Players are:
-
Taiwan Semiconductor Manufacturing Company Limited
-
Samsung Foundry (Samsung Electronics Co., Ltd.)
-
Intel Foundry (Intel Corporation)
-
Apple Inc.
-
Qualcomm Incorporated
-
MediaTek Inc.
-
NVIDIA Corporation
-
Advanced Micro Devices, Inc.
-
Broadcom Inc.
-
Synopsys, Inc.
-
Cadence Design Systems, Inc.
-
Arm Holdings plc
-
ASML Holding N.V.
-
Applied Materials, Inc.
-
Lam Research Corporation
-
Tokyo Electron Limited
-
KLA Corporation
3nm Process Technology for Semiconductor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 28.34 Billion |
| Market Size by 2035 | USD 121.19 Billion |
| CAGR | CAGR of 15.64% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (FinFET, Gate-All-Around (GAA), and Others) • By Application (Consumer Electronics, High-Performance Computing and Data Centers, Automotive, Telecom, and Others) • By Chip Type (CPUs and Application Processors, GPUs, ASICs and AI Accelerators, FPGAs, and Others) • By End User (Fabless Companies, Integrated Device Manufacturers, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Taiwan Semiconductor Manufacturing Company Limited, Samsung Foundry (Samsung Electronics Co., Ltd.), Intel Foundry (Intel Corporation), Apple Inc., Qualcomm Incorporated, MediaTek Inc., NVIDIA Corporation, Advanced Micro Devices, Inc., Broadcom Inc., Synopsys, Inc., Cadence Design Systems, Inc., Arm Holdings plc, ASML Holding N.V., Applied Materials, Inc., Lam Research Corporation, Tokyo Electron Limited, KLA Corporation |

Frequently Asked Questions
The key players in the 3nm Process Technology for Semiconductor Market include Taiwan Semiconductor Manufacturing Company Limited, Samsung Foundry (Samsung Electronics Co., Ltd.), Intel Foundry (Intel Corporation), Apple Inc., Qualcomm Incorporated, among others.
Key opportunities include custom silicon for cloud providers, networking companies and carmakers, and new regional fab capacity in the United States, Japan and Taiwan.
The major growth factor is demand for artificial intelligence accelerators and flagship mobile processors that need the highest transistor density and energy efficiency.
The FinFET segment dominated the 3nm Process Technology for Semiconductor Market with approximately 68.43% share in 2025, because the leading foundry runs its 3nm family on proven FinFET transistors.
Asia Pacific dominated the 3nm Process Technology for Semiconductor Market with a 57.38% share in 2025, supported by leading foundries in Taiwan and South Korea and large packaging and assembly bases.
