
Advanced Tires Market Report Scope & Overview:
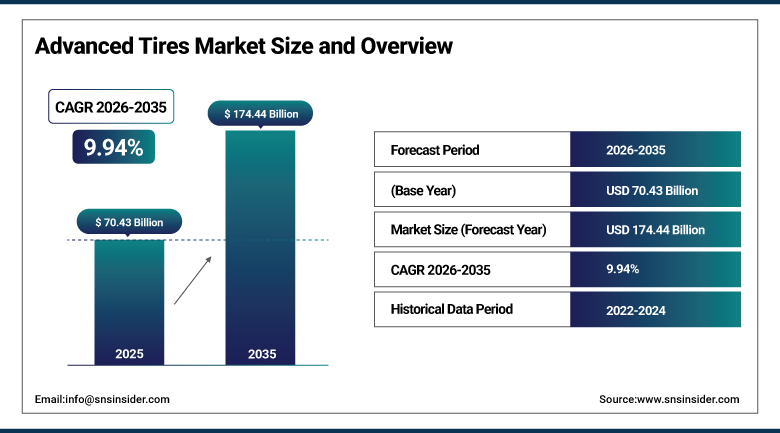
The Advanced Tires Market was valued at USD 70.43 Billion in 2025 and is expected to reach USD 174.44 Billion by 2035, growing at a CAGR of 9.94% from 2026-2035.
The advent of advanced tires is the next frontier in tire technology, which involves the use of built-in sensors, smart materials, and connectivity features to turn a passive vehicle part into an active source of data about performance and safety. Smart tires fitted with such sensors are capable of monitoring pressure, temperature, and wear of the tire tread in a continuous manner, thereby improving the ability to predict and prevent tire blowouts, which has made them more popular among fleet operators and car owners.
Global automotive production increased by 10.3% between 2022 and 2023 according to OICA data, a recovery that has directly reinforced demand across the advanced tire supply chain as automakers ramp production back toward pre-disruption volumes. Growing integration of telematics and vehicle diagnostics into tire technology continues to expand beyond simple pressure monitoring into comprehensive vehicle uptime and on-road performance management, a shift that is turning tire manufacturers into genuine technology suppliers competing on sensor and software capability rather than purely on rubber compound and tread design as they historically did.
To Get more information Advanced Tires Market - Request Free Sample Report
Advanced Tires Market Trends
- Sensor-embedded smart tires continue expanding real-time monitoring capability for pressure, temperature, and tread wear detection.
- Low-rolling-resistance tire designs continue gaining priority as electric vehicle manufacturers optimize for maximum driving range.
- Non-pneumatic and self-sealing tire technology continues advancing to reduce blowout risk and improve fleet vehicle uptime.
- Growing telematics integration is expanding tire technology beyond pressure monitoring into comprehensive vehicle performance diagnostics.
- Premium ultra-large rim size tires above 21 inches continue gaining share alongside rising high-performance SUV and EV penetration.
The U.S. Advanced Tires Market Outlook
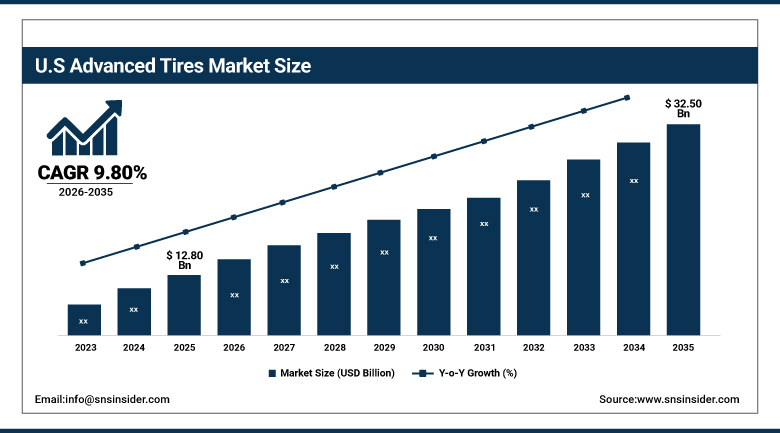
The U.S. Advanced Tires Market was valued at approximately USD 12.80 Billion in 2025 and is expected to reach approximately USD 32.50 Billion by 2035, growing at a CAGR of approximately 9.80%.
In the U.S., there is high growth potential for the use of EVs along with the presence of an efficient fleet management industry that focuses on using predictive maintenance to cut down vehicle downtime and enhance their safety. Growing consumer demand for premium SUVs and high-performance electric vehicles continues to reinforce demand for larger rim size, sensor-equipped tire products that combine performance with the real-time monitoring capability increasingly expected in modern vehicle ownership.
The U.S. fleet operators continued expanding smart tire adoption through 2024 and 2025, integrating sensor-embedded tire data directly into existing telematics and fleet management platforms to enable predictive maintenance scheduling that reduces unplanned downtime and roadside blowout incidents. This integration trend reflects a broader domestic shift toward treating tire performance data as a core input into overall fleet operational efficiency, comparable in strategic importance to engine diagnostics and fuel consumption monitoring that fleet managers have tracked for decades.
Advanced Tires Market Segment Analysis
- By Tire Type, the pneumatic tires segment dominated the advanced tires market with approximately 57.00% share in 2025, while the non-pneumatic/self-sealing tires segment is the fastest growing with a CAGR of approximately 12.60%.
- By Rim Size, the up to 17 inches segment dominated the advanced tires market with approximately 41.00% share in 2025, while the above 21 inches segment is the fastest growing with a CAGR of approximately 13.20%.
- By Vehicle Type, the passenger vehicles segment dominated the vehicle tire market with approximately 67.00% share in 2025, while the commercial vehicles segment is expected to be the fastest-growing vehicle type segment during the forecast period.
- By Technology, the sensor-embedded/TPMS-integrated segment dominated the advanced tires market with approximately 46.80% share in 2025, while the RFID-enabled segment is the fastest growing with a CAGR of approximately 12.90%.
By Tire Type, pneumatic tires dominates, non-pneumatic/self-sealing tires grows fastest
Pneumatic tires dominated the tire type segment in 2025 with approximately 57.00% share, given their superior structure and performance relative to bias tire construction. Because radial tire cords are placed at right angles to the direction of travel, they allow better flexibility, improved fuel efficiency, and longer tread life across nearly every vehicle category. Manufacturers continue refining radial construction to further reduce rolling resistance, a performance metric increasingly central to both fuel-efficient combustion vehicles and range-optimized electric vehicle platforms alike.
Non-pneumatic and self-sealing tires are the fastest-growing tire type segment, expanding at a CAGR of approximately 12.60% over the forecast period, driven by their convenience and safety features that reduce blowout risk and improve fleet vehicle uptime, particularly valuable for commercial and logistics operators managing large vehicle networks where downtime carries direct operational cost. Commercial logistics operators in particular continue to prioritize this technology, given the direct operational cost savings from avoided roadside breakdowns and reduced vehicle downtime across large delivery fleets.
By Rim Size, up to 17 inches dominates, above 21 inches grows fastest
Up to 17 inches dominated the rim size segment in 2025 with approximately 41.00% share, growth driven by wide vehicle fit and a solid mix of function and lower cost, since these tires primarily equip small to medium passenger cars that make up a major share of overall global vehicle production. Cost-conscious consumers purchasing mainstream passenger vehicles continue to represent the largest volume segment within this rim size category, sustaining its leading market position across most global regions.
More than 21 inches forms the fastest growing rim size category and is expected to grow at a CAGR of around 13.20% over the forecast period due to the increasing adoption of ultra-luxury SUVs, high-performance electric vehicles, and tuned sport models requiring larger rim sizes for both performance and styling reasons. The increasing launches of luxury and performance electric vehicle models form the primary factor behind this growing demand in the rim size category.
By Technology, sensor-embedded/TPMS-integrated dominates, RFID-enabled grows fastest
Sensor-embedded and TPMS-integrated tires dominated the technology segment in 2025 with approximately 46.80% share, providing real-time monitoring of tire pressure, temperature, and wear that enhances safety, performance, and predictive maintenance capability across both individual consumer and commercial fleet applications. Regulatory mandates requiring tire pressure monitoring systems across multiple major markets continue to reinforce this technology category's dominant position within the broader advanced tire market.
RFID-enabled tires constitute the highest-growth technology category, growing at a CAGR of around 12.90% during the forecast period, due to the increasing demand from fleet owners for the capacity to monitor the identity, performance, and maintenance history of each tire used by the fleet throughout its operational life cycle. Increasing sophistication of fleet asset management practices is a significant factor behind the increasing need for the tracking of the identity of each tire used.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
47.60% |
|
North America |
United States |
78.20% |
|
Europe |
Germany |
27.80% |
|
Latin America |
Brazil |
28.40% |
|
Middle East & Africa |
UAE |
23.10% |
North America Advanced Tires Market Insights
North America is the fastest-growing region in the Advanced Tires Market, expanding at a CAGR of approximately 11.40% over the forecast period, driven by strong electric vehicle adoption growth and a well-established fleet management industry increasingly prioritizing predictive maintenance technology. Growing state-level electric vehicle adoption incentive programs across the U.S. continue to indirectly support demand for compatible low-rolling-resistance tire technology.
The United States accounts for the substantial majority of regional demand, with fleet operators increasingly integrating smart tire data into existing telematics platforms. Canadian and Mexican automotive markets continue to expand alongside similar advanced tire adoption trends across the broader North American market. Growing logistics and e-commerce delivery fleet expansion continues to reinforce commercial vehicle advanced tire adoption across the broader North American market.
Europe Advanced Tires Market Insights
Europe represents a mature, technologically advanced tires market, with Germany leading regional demand through its large premium automotive manufacturing base and strong domestic tire engineering and sensor technology supplier ecosystem. Growing European automaker investment in vehicle electrification programs continues to reinforce demand for tires specifically optimized for EV range and performance requirements.
France and Italy contribute additional demand, both markets favoring advanced tire technology supporting regional vehicle electrification programs. Growing EU vehicle safety regulation continues to reinforce sensor-embedded tire adoption across the broader European automotive market. Nordic countries continue to lead regional smart tire pilot program adoption, supported by strong domestic connected vehicle infrastructure investment.
Asia Pacific Advanced Tires Market Insights
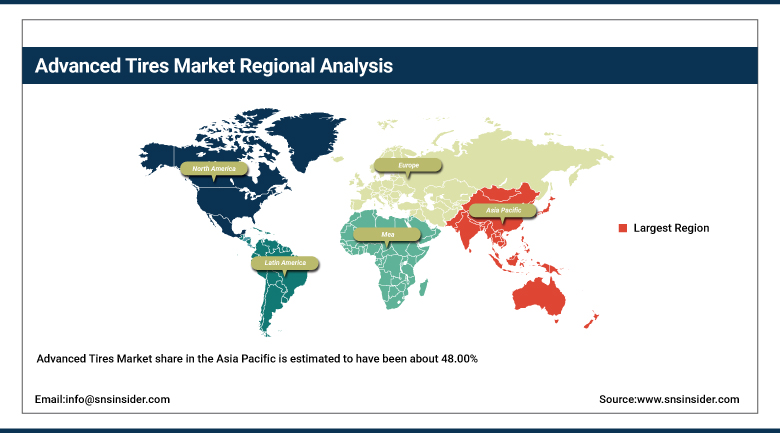
Advanced Tires Market share in the Asia Pacific is estimated to have been about 48.00%, owing to the growth in automobile production in countries such as China, Japan, and India, where increased production in electric vehicles has increased the need for advanced tire technology that has low rolling resistance. Increased government encouragement for manufacturing electric vehicles has indirectly increased the need for advanced tire technology.
China anchors regional demand through its massive automotive production base and rapidly growing domestic electric vehicle manufacturing sector, while India's expanding vehicle production continues to drive strong incremental regional demand. Japan and South Korea continue contributing advanced sensor and materials technology supporting the broader regional tire innovation base. Southeast Asian markets continue expanding domestic tire manufacturing capacity to serve both growing regional vehicle production and export demand.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Advanced Tires Market Insights
The Middle East and Africa represent a smaller but growing market, with the UAE driving regional demand through strong premium vehicle ownership and growing fleet management sophistication tied to the country's logistics and transportation sector. Growing regional logistics and transportation sector sophistication continues to expand the addressable market for advanced tire technology across Gulf state markets.
Latin America is a growing market led by Brazil, where an expanding domestic vehicle production sector continues to drive advanced tire demand. Mexico contributes meaningful secondary demand through its large automotive export manufacturing sector serving North American vehicle platforms. Argentine and Colombian commercial fleet operators continue to gradually adopt advanced tire technology as regional logistics sophistication increases.
Market Dynamics
Growth Drivers: EV adoption and predictive maintenance demand fueling growth
Rapid automotive industry transition toward electric vehicles remains the primary driver of advanced tire demand, as manufacturers focus on next-generation tires incorporating low rolling resistance designs that directly optimize vehicle range and energy efficiency in ways that carry substantially greater commercial significance for EVs than conventional vehicles. Growing regulatory pressure on vehicle emissions standards worldwide continues to indirectly reinforce this driver, as lower rolling resistance directly translates into measurable fuel and energy efficiency improvements.
Growing fleet operator and individual consumer demand for predictive maintenance technology continues to drive smart tire adoption, as embedded sensors providing real-time pressure, temperature, and tread wear data enable proactive service scheduling that reduces costly unplanned downtime and roadside blowout incidents.
Restraints: Infrastructure gaps and integration complexity limiting broader adoption
Lack of infrastructure for the broader smart tire ecosystem, including compatible diagnostic and data management systems, continues to constrain adoption among smaller fleet operators and consumers who lack the technical infrastructure to fully utilize advanced tire monitoring capability. Manufacturers increasingly partner with telematics providers specifically to help smaller fleet customers overcome this infrastructure barrier through simplified, pre-integrated solution packages.
Integration complexity of smart tire systems, requiring coordination between sensor hardware, vehicle telematics platforms, and fleet management software, continues to create implementation friction that particularly challenges smaller automotive manufacturers and developing regions with limited technical expertise.
Opportunities: Fleet telematics integration and airless technology widening addressable demand
Growing integration between smart tire sensor data and broader fleet telematics platforms presents a significant opportunity for manufacturers to position advanced tires as a core component of comprehensive vehicle diagnostics rather than a standalone monitoring feature. Manufacturers that successfully position advanced tires as a core telematics data source stand to capture stronger, more durable customer relationships than those competing purely on traditional tire performance metrics.
Continued advancement of airless and non-pneumatic tire technology presents a substantial opportunity to address blowout risk entirely, particularly appealing to commercial fleet operators and government agencies managing large vehicle fleets in demanding operational environments.
Recent Developments:
- 2025- Global Market Insights reported that light-duty vehicle advanced tire applications reached over USD 800 million in 2024, with substantial growth expected as EV adoption accelerates.
- 2024- Michelin expanded its connected tire sensor technology portfolio, targeting fleet operators seeking integrated predictive maintenance and telematics platform compatibility.
- 2024- Bridgestone announced expanded airless tire technology development, targeting commercial fleet customers seeking reduced blowout risk and improved vehicle uptime.
- 2023- Continental AG expanded its sensor-embedded tire production capacity, targeting electric vehicle manufacturers seeking low-rolling-resistance, connected tire solutions.
Advanced Tires Market Key Players
- Bridgestone Corporation
- Continental AG
- The Goodyear Tire & Rubber Company
- Hankook Tire & Technology Co., Ltd.
- Compagnie Générale des Établissements Michelin
- Nokian Tyres Plc
- Pirelli & C. S.p.A.
- Sumitomo Rubber Industries, Ltd.
- Toyo Tire Corporation
- The Yokohama Rubber Company Limited
- Infineon Technologies AG
- Schrader TPMS Solutions (Sensata)
- NXP Semiconductors N.V.
- Revvo Technologies Inc.
- JK Tyre & Industries Ltd.
- Apollo Tyres Ltd.
- MRF Limited
- Cooper Tire & Rubber Company (Goodyear)
- Kumho Tire Co., Inc.
- Ceat Limited
Advanced Tires Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 70.43 Billion |
| Market Size by 2035 | USD 174.44 Billion |
| CAGR | CAGR of 9.94% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Tire Type (Pneumatic Tires, Tires, Non-Pneumatic/Self-Sealing Tires, Run-Flat Tires) • By Rim Size (Up to 17 Inches, 18-21 Inches, Above 21 Inches) • By Vehicle Type (Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Off-Highway Vehicles, Two-Wheelers, Others) • By Technology (Sensor-Embedded/TPMS-Integrated, RFID-Enabled, Airless Technology, Self-Sealing, Multi-Chamber, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Hankook Tire & Technology Co., Ltd., Compagnie Générale des Établissements Michelin, Nokian Tyres Plc, Pirelli & C. S.p.A., Sumitomo Rubber Industries, Ltd., Toyo Tire Corporation, The Yokohama Rubber Company Limited, Infineon Technologies AG, Schrader TPMS Solutions (Sensata), NXP Semiconductors N.V., Revvo Technologies Inc., JK Tyre & Industries Ltd., Apollo Tyres Ltd., MRF Limited, Cooper Tire & Rubber Company (Goodyear), Kumho Tire Co., Inc., Ceat Limited. |
Frequently Asked Questions
Key players in the Advanced Tires Market include Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Hankook Tire & Technology Co., Ltd., and Compagnie Générale des Établissements Michelin, among others.
Key opportunities include growing integration between smart tire sensor data and fleet telematics platforms, and continued advancement of airless and non-pneumatic tire technology addressing blowout risk.
The market is driven by rapid automotive industry transition toward electric vehicles requiring low-rolling-resistance tires, alongside growing demand for predictive maintenance technology among fleet operators and consumers.
The Pneumatic Tires segment dominated the Advanced Tires Market, accounting for approximately 57.00% market share.
Asia Pacific dominated the Advanced Tires Market in 2025 with approximately 48.00% share, driven by rising automotive production across China, Japan, and India.
