
Aircraft Filters Market Report Scope & Overview:
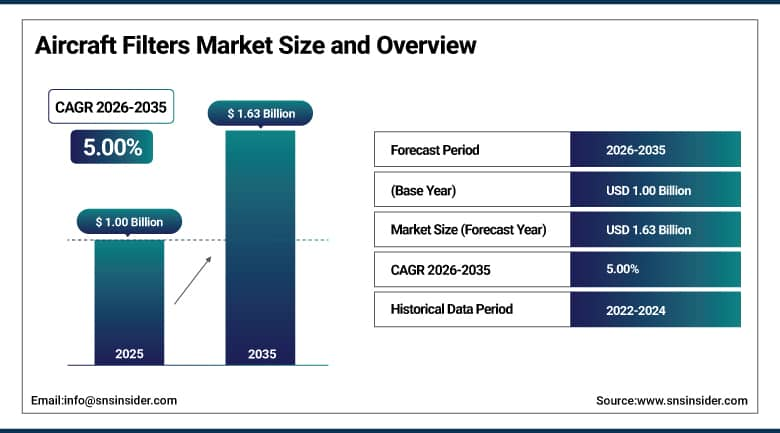
The Aircraft Filters Market was valued at USD 1.00 Billion in 2025 and is expected to reach USD 1.63 Billion by 2035, growing at a CAGR of 5.00% from 2026-2035.
The Aircraft Filters Market growth will be led by factors such as increased air traffic, growth in commercial fleets, and increasing demand for advanced aviation systems. Filtration systems have become extremely crucial for complying with regulations as well as ensuring resilience across the global aerospace industry. The aircraft filter market includes air intake filters, cabin air filters, fuel filters, hydraulic filters, and oil filters, all of which have their respective validation and replacement needs ranging across various categories such as commercial aircraft, general aviation, helicopters, and military aircraft. Considering the number of aircraft in the global commercial fleet, which has crossed the 29,000 mark, the need for filters to be replaced keeps on growing and averaging out to every 1,000 flight hours, making the filter replacement process a non-discretionary after-market opportunity that is immune to economic cycle fluctuations owing to aviation safety regulations that specify replacement of filters at certain intervals.
In 2024, Parker Hannifin Corporation received regulatory approval for its new high-efficiency particulate air filter designed for commercial aircraft cabins, meeting stringent air quality standards amid growing airline and passenger focus on cabin health and comfort. The approval reflects continued supplier investment in next-generation cabin filtration technology as airlines and aircraft manufacturers increasingly prioritize passenger health and comfort, leading to greater investment in high-quality air filtration systems that ensure a clean and safe cabin environment, reinforcing Parker Hannifin's position among the aerospace industry's leading filtration technology suppliers as it continues to strengthen relationships across nearly every major aircraft platform in service today.
To Get More Information On Aircraft Filters Market - Request Free Sample Report
Aircraft Filters Market Trends:
-
Rising integration of nanofiber-based cabin air filtration technology improving particulate and pathogen capture efficiency.
-
Growing development of finer liquid filtration systems supporting sustainable aviation fuel and hydrogen propulsion systems.
-
Expanding unmanned aerial system filtration demand as a distinct, high-growth niche within the broader aircraft filters category.
-
Increasing integration of IoT-enabled predictive maintenance capability within aircraft filtration monitoring systems.
-
Rising consolidation among filtration suppliers through acquisitions expanding aftermarket and regional manufacturing capability.
-
Growing airline and OEM investment in advanced HEPA and activated-carbon filtration to enhance passenger cabin comfort.
U.S. Aircraft Filters Market Outlook:
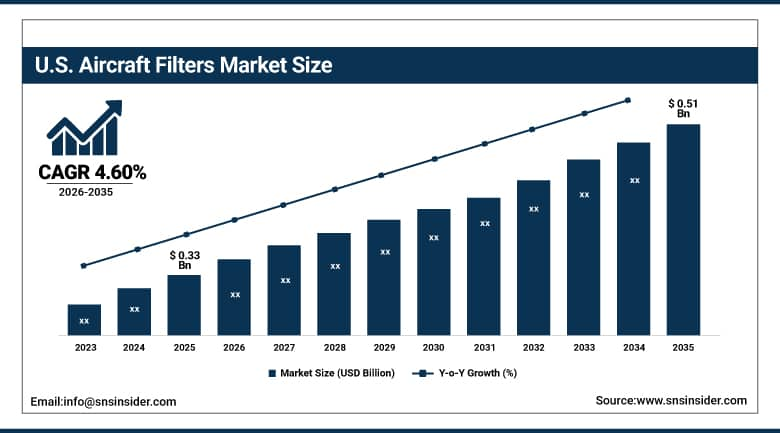
The U.S. Aircraft Filters Market was valued at USD 0.33 Billion in 2025 and is expected to reach USD 0.51 Billion by 2035, growing at a CAGR of 4.60% from 2026-2035.
The growth in the US aircraft filters market will continue to be driven by effective OEM and MRO systems and stringent regulations such as those issued by the FAA and EPA, making North America the largest market for aircraft filtration in the world. The large number of aircraft in the US along with the recovery in the number of passengers using air transportation back to the numbers before the pandemic ensures that there will be constant growth in the deliveries of aircrafts and demand for better filtration systems. At the same time, global increase in defense spending and replacement of old military fleets ensure growth in defense filtration sales, while the presence of domestic vendors in all current and future aircraft platforms ensures opportunities in the aftermarket.
In 2025, Ametek MRO completed the acquisition of a UK-based aviation filter manufacturer, strengthening its position in the aircraft filter aftermarket and expanding its product portfolio for global customers seeking comprehensive filtration solutions across commercial and military aircraft platforms.
Aircraft Filters Market Segment Analysis:
-
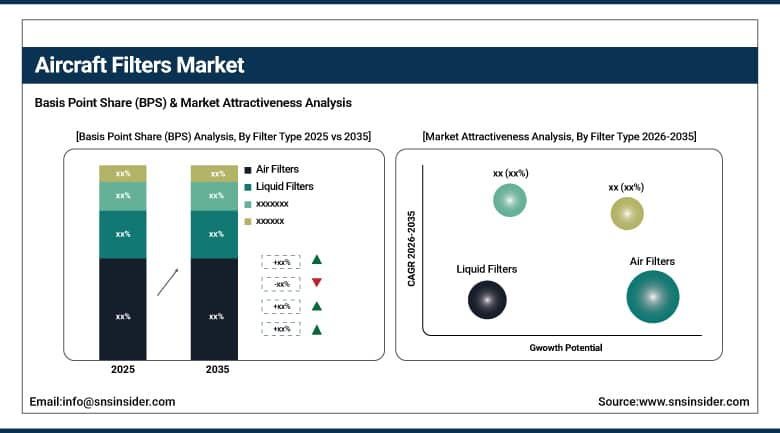
By Filter Type, the Air Filters segment dominated the Aircraft Filters Market with approximately 55.60% share in 2025, while the Liquid Filters segment is the fastest growing with a CAGR of approximately 5.60%.
-
By Platform, the Commercial Aviation segment dominated the Aircraft Filters Market with approximately 50.60% share in 2025, while the Unmanned Aerial Systems segment is the fastest growing with a CAGR of approximately 8.60%.
-
By Application, the Engine Systems segment dominated the Aircraft Filters Market with approximately 30.60% share in 2025, while the Cabin Systems segment is the fastest growing with a CAGR of approximately 5.80%.
-
By End-User, the Aftermarket segment dominated the Aircraft Filters Market with approximately 62.60% share in 2025, while the OEM segment is the fastest growing with a CAGR of approximately 5.20%.
By Filter Type, Air Filters Dominates the Aircraft Filters Market and Liquid Filters Grows Fastest
Air filters continue to be dominant in the industry due to their importance in ensuring protection of the engines of the aircraft from ingesting particulates while ensuring the air in the cabin is of good quality, thus contributing to the health and comfort of the passengers of commercial as well as military aviation platforms. Air intake filters protect the engine from dust and other particles or objects getting into the engine parts while cabin air filters ensure that particulates, allergens, and sometimes pathogens do not make it into the cabin air that gets recirculated, a process that has become particularly significant following the pandemic and the importance placed on health and hygiene of passengers.
Liquid Filters, which include fuel filters, hydraulic filters, and oil filters, represent the fastest growing segment as a result of the growing requirement for more refined fuel filtration systems due to sustainable aviation fuels and hydrogen-powered propulsion systems. This is further supported by the introduction of higher durability hydraulic filters by suppliers to increase reliability while minimizing maintenance downtime, as well as lightweight hydraulic filters to reduce overall aircraft weight without affecting filtration efficiency. Increasing usage of other propulsion systems, together with airlines’ increasing emphasis on minimizing unexpected maintenance, further supports the faster-than-market growth of liquid filters.
By Platform, Commercial Aviation Dominates the Aircraft Filters Market and Unmanned Aerial Systems Grows Fastest
Commercial aviation dominates the market, reflecting the scale of the global commercial fleet exceeding 29,000 aircraft and the sector's recovery to pre-pandemic passenger traffic and flight volumes, which continues to sustain predictable, scheduled maintenance-driven filter replacement demand. Commercial aircraft deliveries continue to expand as airlines modernize fleets with more fuel-efficient aircraft, each requiring a full complement of engine, cabin, fuel, and hydraulic filtration systems validated to strict certification standards. The predictable nature of commercial fleet maintenance cycles, combined with aviation safety regulations mandating filter replacement at specified flight-hour intervals, continues to sustain commercial aviation's position as the largest and most stable platform category for aircraft filter suppliers, providing a reliable revenue base largely insulated from short-term economic volatility.
Unmanned aerial systems have emerged as the fastest-growing platform category due to the fact that the introduction of new niches of high growth in the aircraft filters market segment will provide a sizeable market opportunity over the next few years. The above statement is based on the growing number of drones being used for both military and commercial purposes and the requirement of filters that can be integrated into an aircraft design having different engine and fuel systems compared to manned aircraft platforms. Companies that design and manufacture filters designed specifically for such unmanned systems are expected to benefit disproportionately.
By Application, Engine Systems Dominates the Aircraft Filters Market and Cabin Systems Grows Fastest
Engine systems dominate the market because protecting aircraft engines from particulate ingestion represents the most safety-critical filtration application across every aircraft platform, directly affecting engine reliability, performance, and operational safety throughout the aircraft's service life. Engine air intake filters must meet exceptionally stringent certification and validation requirements given the catastrophic consequences of engine failure, sustaining premium pricing and rigorous supplier qualification standards relative to less safety-critical filtration applications. The universal requirement for engine filtration across commercial, military, general aviation, and helicopter platforms alike continues to sustain engine systems' position as the largest application category, reinforced by rising global aircraft production and the corresponding scheduled maintenance and replacement demand this expanding fleet continues to generate.
Cabin Systems Segment is the fastest growing segment driven by rising passenger traffic and stringent air quality requirements that have continued to fuel demand for superior cabin air filtration technology that can address issues of particulate matter and pathogen elimination. This trend has been boosted by the current pandemic-related focus on health and hygiene standards as airlines and manufacturers invest in high efficiency particulate air filters and nanofiber filter material capable of trapping finer particulate matter. The top players in the market are continually introducing new cabin air filtration technology using innovative materials, driving the continued above average growth rate of cabin systems segment.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
|
Latin America |
Brazil |
27.60% |
North America Aircraft Filters Market Insights
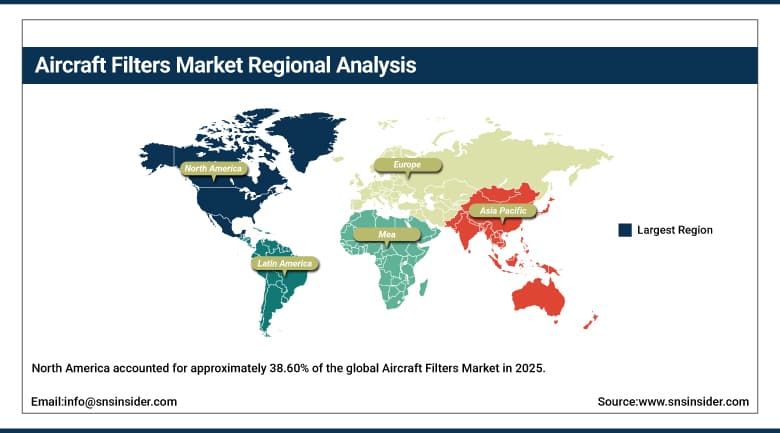
North America accounted for approximately 38.60% of the global Aircraft Filters Market in 2025, making it the largest regional market, supported by strong OEM and MRO systems and rigorous FAA and EPA regulatory requirements governing both engine and cabin air filtration standards. The United States anchors regional demand given its substantial commercial and military fleet, home to established filtration suppliers with decades-long relationships across nearly every major aircraft platform currently in service. Continued fleet modernization, combined with rising defense spending replacing aging military aircraft, continues to sustain robust filtration demand across both commercial and defense aviation segments within the region.
Canada is contributing incremental regional demand as its commercial and general aviation sectors continue to expand alongside broader North American fleet growth. The region's mature MRO ecosystem, combined with stringent regulatory oversight governing filter replacement intervals and certification standards, continues to sustain predictable, non-discretionary aftermarket demand largely insulated from short-term economic cycles. Continued domestic supplier investment in sustainable aviation fuel-compatible filtration technology and next-generation cabin air quality systems is expected to reinforce North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Aircraft Filters Market Insights
Asia Pacific is the fastest-growing regional market, gaining from increased aircraft production, including expanding domestic manufacturing programs such as COMAC, alongside growing MRO operations and localization efforts across the region. China's rapidly expanding commercial aviation sector continues to drive substantial regional demand for both engine and cabin filtration systems, as domestic airlines expand fleets to meet rising passenger travel demand across the country's rapidly growing air travel market. Japan and South Korea contribute additional scale through established aerospace manufacturing sectors increasingly localizing filtration component production.
India and Southeast Asian markets are contributing significant incremental growth as expanding commercial aviation infrastructure and rising air travel demand continue to extend aircraft filter adoption into a broader range of domestic and regional carriers. Although the region currently has no significant filter manufacturers, incessant demand continues to fuel growth as global suppliers expand distribution and support infrastructure to serve the region's rapidly growing fleet. This combination of rising aircraft production, expanding MRO capacity, and growing localization efforts is expected to sustain Asia Pacific's position as the fastest-growing aircraft filters market through the forecast period.
Europe Aircraft Filters Market Insights
Europe holds an important place in the global Aircraft Filters Market owing to the large-scale presence of aerospace manufacturing in Germany and the presence of well-established filtration technology companies in the region that cater to commercial and military aviation applications. Companies from Europe are continuing to hold the leadership position in terms of development of advanced air cabin filtration technologies, as demonstrated through cooperation between filtration companies and aircraft makers for developing next generation air cabin filtration systems.
Demand in France and UK is expected to grow steadily owing to the increased usage of advanced filtration technologies in regional aircraft manufacturing. The regional companies continue to focus on odor neutralization as well as business jet specific filters. The region's demand will continue to grow steadily due to its well-established aerospace manufacturing presence and passenger comfort considerations in both commercial as well as business aviation segments.
MEA & Latin America Aircraft Filters Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing commercial aviation investment across the United Arab Emirates and Saudi Arabia sustains demand for aircraft filtration technology supporting the region's rapidly expanding airline fleets. Regional carriers' continued fleet expansion, combined with the region's role as a major international aviation hub, continues to support steady filtration replacement and maintenance demand across both engine and cabin air systems.
Latin America's market is led by Brazil, where a substantial domestic aerospace manufacturing and commercial aviation sector sustains steady demand for aircraft filters across both OEM and aftermarket channels. Mexico is contributing growth as regional aerospace manufacturing continues to expand alongside nearshoring-driven investment. Across the region, adoption remains concentrated among larger commercial carriers and established aerospace manufacturing operations with mature MRO infrastructure.
Market Dynamics:
Growth Drivers: Rising Air Traffic and Fleet Expansion
The increasing volume of air traffic and expansion of commercial aircraft fleets constitute the key factor influencing the Aircraft Filters Market, due to the increase in the demand for passenger transport and subsequent delivery of aircraft with required filtration equipment. Air travel volumes have rapidly recovered from pandemic levels and now are higher than before; therefore, there is a continued demand for increased aircraft delivery volumes and the necessary filtration equipment. Higher expenditures on defense and renewal of outdated military fleets constitute other significant drivers of the market, driving the demand for defense-oriented filters regardless of the commercial segment demand cycle.
Growing demand for modern aviation systems and the need for environmental sustainability make up the second driver of the Aircraft Filters Market growth, due to the increasing demands for emission and cabin air regulations. The development of sustainable fuels and hydrogen propulsion makes an additional demand for fuel filtration systems able to work with new types of fuel. There is an increasing demand for air filtration in airlines and aircraft manufacturers due to the need to provide comfortable and healthy conditions for passengers.
Restraints: Fluctuating Raw Material Costs and Certification Complexity
Uncertain costs of raw materials also pose an important limitation, as the producers of filtration media need to deal with fluctuating costs of specialized raw materials such as glass fiber, activated carbon, and specialized synthetic media used in various kinds of filters. Uncertain costs of specialized materials may reduce margins of suppliers or cause the necessity of frequent price changes making it difficult to negotiate contracts with airline companies and OEMs who operate under strict cost management, especially during periods of turmoil in commodity markets that disrupt the supply of specialized filtration materials.
Uncertainty associated with certification processes poses yet another limitation to the market as the aircraft filtration components have to be validated and approved prior to being installed on aircrafts of commercial and military type, increasing development and production costs compared to industrial applications where there is no such need. The complexity of certification process also presents a barrier to entry for new suppliers and also limits the ability of existing suppliers to introduce advanced filtration technologies due to separate certification requirements.
Opportunities: Sustainable Aviation Fuel Compatibility and Unmanned System Filtration
Development of advanced filtration technologies for sustainable aviation fuel represents a substantial opportunity, as the aviation industry's transition toward alternative fuel chemistries and hydrogen propulsion systems continues to require specialized fuel filtration technology capable of handling different particulate profiles and chemical compositions than conventional jet fuel. Suppliers that can develop validated, certified filtration solutions compatible with emerging alternative fuel and propulsion technology are positioned to capture premium pricing and long-term supply relationships as airlines and manufacturers accelerate their transition toward more sustainable aviation fuel sources across the global commercial fleet.
Expansion into emerging markets with tailored filtration solutions, combined with the continued growth of unmanned aerial system filtration demand, offers a further avenue for growth, as suppliers develop compact, lightweight filtration technology suited to the unique operational requirements of drone and unmanned aircraft platforms. Suppliers that can pair cost-competitive manufacturing with IoT-enabled predictive maintenance capability are well positioned to capture demand from both emerging market commercial fleets and rapidly expanding unmanned aerial system operators seeking to minimize unplanned maintenance events across their growing platform fleets.
Recent Developments:
-
In August 2024, Mann+Hummel introduced the Mann-Filter FreciousPlus, a new cabin air filter incorporating nanofibers to enhance particulate and pathogen capture efficiency for commercial aircraft applications.
-
In 2024, Pall Corporation launched an extended-life hydraulic filter for commercial aircraft, aiming to reduce maintenance downtime and improve operational reliability for airline operators.
-
In 2025, Parker Hannifin Corporation introduced a lightweight hydraulic filter designed to reduce overall aircraft weight while maintaining filtration performance standards.
-
In 2024, Porvair PLC entered into a partnership with a major Asian aircraft manufacturer to supply fuel system filters for new aircraft models.
Aircraft Filters Market Key Players:
-
Parker Hannifin Corporation
-
Pall Corporation (Danaher Corporation)
-
Freudenberg Filtration Technologies GmbH & Co. KG
-
Donaldson Company, Inc.
-
Amphenol Corporation
-
Camfil AB
-
Porvair plc
-
Swift Filters, Inc.
-
Hollingsworth & Vose Company
-
Honeywell International Inc.
-
MANN+HUMMEL Group
-
Eaton Corporation plc
-
Filtration Group Corporation
-
HYDAC International GmbH
-
Champion Laboratories, Inc.
-
Sofima Filters S.p.A.
-
Safran Group
-
FAUDI Aviation GmbH
-
PTI Technologies, Inc.
-
Ametek MRO
Aircraft Filters Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.00 Billion |
| Market Size by 2035 | USD 1.63 Billion |
| CAGR | CAGR of 5.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Filter Type (Air Filters and Liquid Filters) • by Platform (Commercial Aviation, Military Aviation, General Aviation, Helicopters, and Unmanned Aerial Systems) • by Application (Engine Systems, Cabin Systems, Hydraulic Systems, and Fuel Systems) • by End-User (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Parker Hannifin Corporation, Pall Corporation (Danaher Corporation), Freudenberg Filtration Technologies GmbH & Co. KG, Donaldson Company, Inc., Amphenol Corporation, Camfil AB, Porvair plc, Swift Filters, Inc., Hollingsworth & Vose Company, Honeywell International Inc., MANN+HUMMEL Group, Eaton Corporation plc, Filtration Group Corporation, HYDAC International GmbH, Champion Laboratories, Inc., Sofima Filters S.p.A., Safran Group, FAUDI Aviation GmbH, PTI Technologies, Inc., Ametek MRO |
Frequently Asked Questions
Key players include Parker Hannifin Corporation, Pall Corporation, Freudenberg Filtration Technologies GmbH & Co. KG, Donaldson Company, Inc., Honeywell International Inc., and MANN+HUMMEL Group, among other aerospace filtration suppliers.
Development of advanced filtration technologies for sustainable aviation fuel and continued growth of unmanned aerial system filtration demand represent the primary opportunities.
Growth is primarily driven by increasing air traffic and expanding commercial fleets combined with rising demand for advanced aviation systems and growing focus on environmental sustainability.
By Filter Type, Air Filters dominated the market with approximately 55.60% share in 2025, reflecting their critical role in engine protection and cabin air quality maintenance.
North America dominated the market with approximately 38.60% share in 2025, supported by strong OEM and MRO systems and rigorous FAA and EPA regulatory requirements.
