
Aircraft Insulation Market Report Scope & Overview:
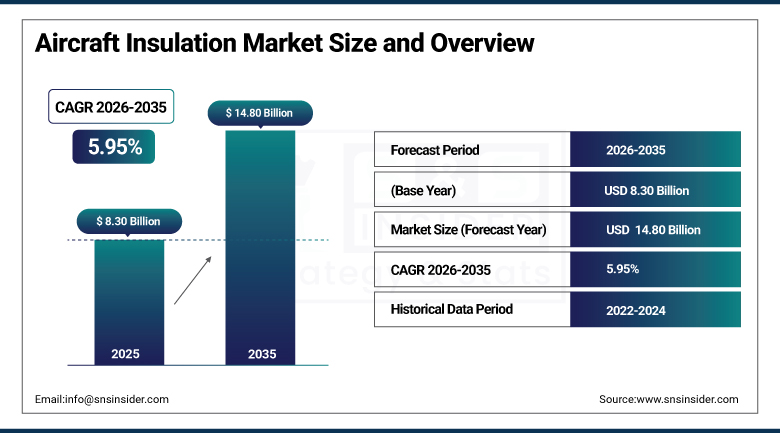
The Aircraft Insulation Market was valued at USD 8.30 Billion in 2025 and is expected to reach USD 14.80 Billion by 2035, growing at a CAGR of 5.95% from 2026-2035.
Growth in the Aircraft Insulation Market is fueled by increasing production levels in commercial aviation and the aging of the global fleet such that many aircraft are nearing the end of their lifespan and need insulation systems replaced in heavy checks. Tougher regulations on issues like fire protection, thermal capabilities, and reduction of cabin noise are pushing manufacturers towards ever more advanced insulation products, while at the same time, the ongoing efforts to improve fuel economy make light-weighting materials a priority in the research and development process. Bio-based and otherwise sustainable insulation products are increasingly becoming important to suppliers.
Triumph Group introduced a next-generation lightweight thermal insulation blanket in July 2025, constructed from advanced composite fibers and delivering a 12% improvement in thermal efficiency alongside an 8% reduction in weight relative to conventional blanket designs, with the product specifically engineered to improve fuel efficiency on regional jet platforms.
To Get more information On Aircraft Insulation Market - Request Free Sample Report
Aircraft Insulation Market Trends:
-
Rising adoption of bio-based foam insulation formulations reducing lifecycle carbon footprint without sacrificing thermal performance.
-
Growing demand for high-temperature ceramic fiber insulation supporting next-generation turbine engine compartment requirements.
-
Expanding scheduled insulation replacement programs across aging widebody fleets reaching first-round heavy maintenance checks.
-
Increasing development of lightweight polyurethane foam insulation tailored to electric aircraft thermal management systems.
-
Growing integration of AI-enabled material design and IoT-based monitoring improving insulation performance validation.
-
Rising passenger comfort expectations driving continued investment in advanced acoustic insulation and cabin noise reduction technology.
U.S. Aircraft Insulation Market Outlook:
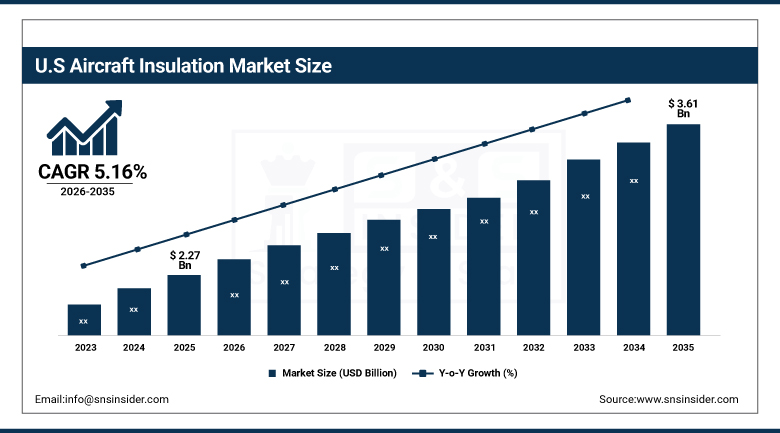
The U.S. Aircraft Insulation Market was valued at USD 2.27 Billion in 2025 and is expected to reach USD 3.61 Billion by 2035, growing at a CAGR of 5.16% from 2026-2035.
Growth in the U.S. Aircraft Insulation Market is consistently being driven by the dominance of the nation in terms of its aircraft production globally, huge defense budgets that provide backing for insulation needs of military aircrafts and a large number of aging aircrafts which require insulation retrofits. The continual investment made in eco-friendly insulation materials and formulations for ceramics fiber further drive the supplier growth.
Boeing's 787 Dreamliner fleet, launched in the early 2010s with composite fuselages and new insulation formulations designed to reduce weight and improve fuel efficiency, is now reaching 15 or more years in service, bringing the fleet to its first round of D-checks and cabin re-insulation programs.
Aircraft Insulation Market Segment Analysis:
-
By Type, the Thermal Insulation segment dominated the Aircraft Insulation Market with approximately 46.80% share in 2025, while the Acoustic & Vibration Insulation segment is the fastest growing with a CAGR of approximately 7.10%.
-
By Material, the Fiberglass segment dominated the Aircraft Insulation Market with approximately 44.60% share in 2025, while the Ceramic-Based Materials segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Application, the Airframe segment dominated the Aircraft Insulation Market with approximately 63.40% share in 2025, while the Propulsion System segment is the fastest growing with a CAGR of approximately 7.30%.
-
By Aircraft Type, the Commercial Aircraft segment dominated the Aircraft Insulation Market with approximately 61.20% share in 2025, while the General Aviation segment is the fastest growing with a CAGR of approximately 6.90%.
By Type, Thermal Insulation Dominates the Aircraft Insulation Market and Acoustic & Vibration Insulation Grows Fastest
Thermal insulation remains at the top of the type segment, as thermal insulation plays a crucial part in ensuring that aircraft systems and passengers are protected from wide temperature changes that occur during all phases of flight. The need for insulation standards that require minimum thermal protection in almost all commercial and military aircraft types keeps this segment as the leading type revenue generator in the insulation market.
Acoustic and vibration insulation emerges as the fast-growing type segment, as customer demands for comfortable travel experience and the differentiation strategy of airlines based on quiet cabins drive the growth of this segment. Higher demands for noise-reducing materials in the face of increasing demands to reduce engine and airframe noise contribute to the above average growth rate of this segment.
By Material, Fiberglass Dominates the Aircraft Insulation Market and Ceramic-Based Materials Grows Fastest
Fiberglass remains dominant in the material category due to its optimal combination of heat resistance, noise reduction, and manufacturing costs compared to more specific types of materials. The material is produced in excess of two million square meters per year in volume by leading material manufacturers serving commercial and military end-user segments. Ceramic fiber material manufacturers who have invested in their production facilities earlier can benefit from high margins as new generation engines will need materials resistant to high operational temperatures.
Ceramic-based materials emerge as the fastest growing segment of the market because of the increasing need for high-temperature-resistant ceramic fiber materials that can replace fiberglass in some applications. Increasing demand for new generation turbine engines drives growth in this segment.
By Application, Airframe Dominates the Aircraft Insulation Market and Propulsion System Grows Fastest
The airframe application group remains the most dominant of all applications and consists of insulation for the cabin, cargo, and fuselage. Together, these make up the biggest surface areas that need thermal and acoustic insulation on any commercial or military aircraft and ensure the group maintains its leadership by a wide margin. Those companies designing and manufacturing insulation systems for future engine designs such as the hybrid electric engine can be expected to garner good revenues from this group as this becomes commercial.
Propulsion application is by far the fastest growing group and is fueled by the increased requirement for special high-temperature insulation for turbine engines, exhausts, and auxiliary power units from high thermal loads. The continued development of new engine programs that require complex thermal management ensures the trend persists.
By Aircraft Type, Commercial Aircraft Dominates the Aircraft Insulation Market and General Aviation Grows Fastest
Commercial aircraft continue to dominate the aircraft-type segment, consistent with the sheer scale of global commercial fleet size and sustained new aircraft production rates across major manufacturers, sustaining consistent demand for both original equipment and aftermarket replacement insulation. Manufacturers targeting business jet and light commercial platforms continue to develop insulation systems optimized for the specific space and weight constraints these smaller aircraft categories present relative to larger commercial platforms.
General aviation represents the fastest-growing aircraft-type category, driven by rising business jet deliveries and growing demand for advanced, lightweight insulation systems on smaller platforms where weight savings translate directly into meaningful range and fuel efficiency improvements. Continued expansion of the global business aviation fleet reinforces this segment's accelerating adoption.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.20% |
|
Europe |
France |
23.40% |
|
Asia Pacific |
China |
36.80% |
|
Latin America |
Brazil |
28.60% |
|
Middle East & Africa |
UAE |
30.20% |
North America Aircraft Insulation Market Insights
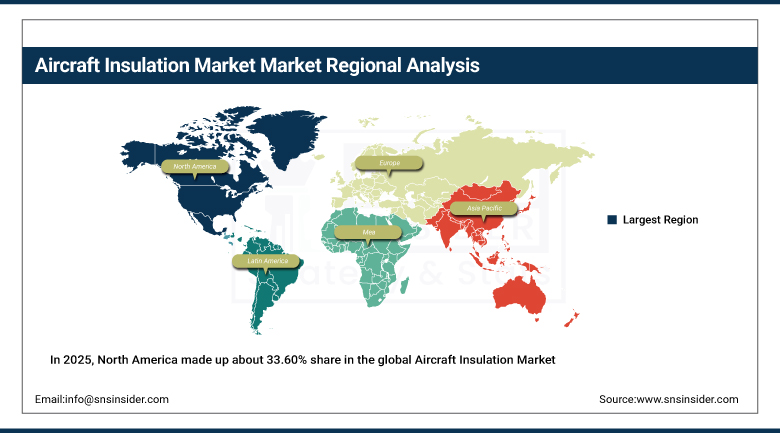
In 2025, North America made up about 33.60% share in the global Aircraft Insulation Market becoming the largest regional market owing to advanced aerospace manufacturing facilities and the dominance of the country in commercial and military aircraft manufacturing. Further bolstering the position of this region is the high defense budget allocation for military aircraft insulation applications. Investment in material science research further helps the region consolidate its dominant position because suppliers keep on developing next generation material formulations before others do in other regions.
Canada helps boost the demand of the region through participation in aerospace manufacturing supply chain of North America. Further investment in development of next generation aerospace insulation materials and systems further helps in consolidating the position of the region.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Aircraft Insulation Market Insights
The Asia Pacific region is expected to have the fastest CAGR in terms of growth of the Aircraft Insulation Market from 2026 to 2035 because of increasing fleets and rising indigenous aspirations for aerospace manufacturing in the major economies of the Asia Pacific region. The major player of the Asia Pacific region is China which can be a leader in aircraft insulation production and consumption due to growing domestic and export demands. India and Japan are also significant players of the Asia Pacific region because of the expansion of their commercial fleet size and domestic manufacturing capability.
South Korea is an important demand driver in the region since it has domestic aerospace insulation market estimated at about USD 0.6 billion in 2025 due to increasing opportunities for export and governmental incentives stimulating development of new materials. India and Japan are additional demand contributors due to expanding commercial fleet size. Increasing governmental incentives for developing new materials in domestic aerospace manufacturing increase the pace of technology gap elimination compared to Western providers.
Europe Aircraft Insulation Market Insights
Europe serves as a significant market region in the production of aircraft insulation, which is based on the presence of a significant number of airframe manufacturers in France along with its robust aerospace industry base. Italy and Spain form other markets in the region that benefit from growing aerostructures manufacturing operations and the involvement of these nations in the European commercial aircraft programs.
The German and UK markets form additional regional markets owing to the existing aerostructures manufacturing capacity along with increased focus on the development of bio-based insulation formulations in a bid to reduce the carbon footprint over the lifecycle. The increasing focus on reducing carbon footprint over the lifecycle drives product development in the region, with manufacturers developing bio-based formulations prior to any regulations coming into effect.
MEA & Latin America Aircraft Insulation Market Insights
The Middle East and Africa region reflects growing strategic importance, with the UAE accounting for the largest regional contribution through its position as a major international aviation hub and growing MRO capacity investment supporting the region's rapidly expanding commercial fleet. Saudi Arabia is following a similar trajectory as it builds out domestic aviation infrastructure alongside broader economic diversification investment across the Gulf states.
Latin America is led by Brazil, home to Embraer, whose continued aircraft delivery programs support sustained demand for both airframe and propulsion system insulation. Mexico and Argentina contribute additional secondary demand tied to their respective aviation sectors. Mexico and Argentina contribute additional secondary demand tied to their respective aviation sectors, with both countries continuing to expand domestic MRO capacity supporting regional carrier fleets.
Market Dynamics:
Growth Drivers: Fleet Aging and Regulatory Requirements
Increased production and aging fleet of aircraft requiring maintenance with regard to insulation replacement are considered the main factor driving market growth as manufacturers and MRO service providers continue developing products which satisfy rising demands with regard to fire resistance and thermal performance. The increase in application of IoT solutions and AI in materials' design serves to reinforce this underlying demand trend as manufacturers are increasingly relying on continuous data gathering for validation of insulation performance.
Strict regulations regarding the noise level in the cabin and safety in the case of fire provide another significant source of growth for the market, as these regulations continue to become stricter in the most developed aviation markets. Rising demand for light-weighting solutions for improving fuel efficiency is yet another aspect reinforcing this underlying demand trend. Increasing regulatory pressures regarding aircraft emissions continue to drive the speed of material innovation.
Restraints: Raw Material Cost Volatility and Certification Timelines
Fluctuating input costs for fiberglass, ceramic fiber, and specialty foam materials represent a significant restraint, as insulation manufacturers remain exposed to broader commodity market swings that directly affect production economics across the supply chain. Suppliers without long-term material supply agreements are particularly exposed to these swings, which can compress margins even when finished-product demand remains steady across the broader commercial aviation supply chain.
Extended certification timelines for new insulation formulations add a further restraint, as achieving FAA and EASA compliance for novel materials requires years of fire, thermal, and durability testing before commercial deployment becomes possible, a barrier that continues to favor established suppliers over newer entrants. Smaller suppliers without dedicated regulatory affairs capability face particular difficulty absorbing these extended certification timelines, often limiting their ability to compete for major OEM contracts against larger, established competitors.
Opportunities: Bio-Based Materials and Electric Aircraft Thermal Management
The continued innovation of bio-based and other eco-friendly insulation materials provides significant room for growth, as companies addressing increased pressure regarding the environmental impact of the products’ lifecycle will increasingly be looking for material partners that offer equal performance while minimizing their environmental impact. The development of engineering capabilities specific to the insulation of batteries and power electronics in order to protect them from overheating is likely to result in design-win opportunities for material suppliers as electric aviation moves closer to certification.
Another area where there is room for growth is the thermal management systems of electric aircraft, which can be insulated by material companies developing insulation materials specifically for this purpose.
Recent Developments:
-
In June 2025, BASF announced the commercial launch of a bio-based foam insulation achieving a 30% reduction in lifecycle carbon footprint, targeting commercial aircraft manufacturers seeking alternative materials to conventional petroleum-based foam formulations.
-
In May 2025, DowDuPont announced a proprietary high-temperature-resistant ceramic fiber insulation directed toward engine compartment applications, offering improved weight and fire resistance for next-generation turbine engine programs.
-
In March 2025, Rogers Corporation launched a new lightweight polyurethane foam tailored specifically for electric aircraft thermal management systems, targeting improved insulation and fire resistance for battery and power electronics protection.
-
In April 2025, Insperial, a portfolio company of Adagia Partners, completed the acquisition of MGR Foamtex, a major United Kingdom supplier of soft furnishing and foam-based comfort products for aircraft interiors.
Aircraft Insulation Market Key Players:
-
Lydall, Inc.
-
Triumph Group, Inc.
-
BASF SE
-
DowDuPont Inc.
-
Rogers Corporation
-
Zotefoams plc
-
Unifrax LLC (Alkegen)
-
3M Company
-
Collins Aerospace (RTX Corporation)
-
Boeing Company
-
Airbus SE
-
Promat International N.V.
-
Mid-Mountain Materials, Inc.
-
Lamart Corporation
-
Vibro-Acoustics
-
Heatcon Composite Systems
-
Duna Group
-
Boyd Corporation
-
TISICS Ltd.
-
Federal-Mogul Corporation
Aircraft Insulation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.30 Billion |
| Market Size by 2035 | USD 14.80 Billion |
| CAGR | CAGR of 5.95% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Thermal Insulation, Acoustic & Vibration Insulation, Electric Insulation) • by Material (Fiberglass, Foamed Plastics, Mineral Wool, Ceramic-Based Materials) • by Application (Airframe, Propulsion System) • by Platform (Fixed Wing, Rotary Wing, Unmanned Aerial Vehicles) • by Aircraft Type (Commercial Aircraft, Military Aircraft, General Aviation) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lydall, Inc., Triumph Group, Inc., BASF SE, DowDuPont Inc., Rogers Corporation, Zotefoams plc, Unifrax LLC (Alkegen), 3M Company, Collins Aerospace (RTX Corporation), Boeing Company, Airbus SE, Promat International N.V., Mid-Mountain Materials, Inc., Lamart Corporation, Vibro-Acoustics, Heatcon Composite Systems, Duna Group, Boyd Corporation, TISICS Ltd., Federal-Mogul Corporation |
Frequently Asked Questions
Key players include Lydall, Inc., Triumph Group, Inc., BASF SE, DowDuPont Inc., and Rogers Corporation, among other leading aerospace materials manufacturers.
Continued development of bio-based insulation formulations and electric aircraft thermal management systems represent the primary opportunities.
Growth is primarily driven by rising commercial aircraft production rates and an aging global fleet reaching scheduled insulation replacement intervals.
By Type, Thermal Insulation dominated the market with approximately 46.80% share in 2025, reflecting its essential role in protecting aircraft systems against temperature fluctuations.
North America dominated the market with approximately 33.60% share in 2025, supported by strong aerospace manufacturing capabilities and defense budget allocations.
