
Angiography Equipment Market Report Scope & Overview:
The Angiography Equipment Market was valued at USD 12.92 Billion in 2025 and is expected to reach USD 22.86 Billion by 2035, growing at a CAGR of 5.87% from 2026-2035.
Angiography equipment market covers the imaging systems, catheters, guidewires, contrast agents and accessories used to see blood vessels in the heart, brain, limbs and organs, both to diagnose disease and to guide treatment. Fixed C-arm systems in catheterization laboratories are the core installed base, supported by consumables used in each procedure. Growth is supported by rising cardiovascular and stroke burden, minimally invasive procedures and artificial intelligence that cuts radiation dose, while capital cost and reimbursement shape purchases.
⮞In May, 2026, Philips unveiled SmartIQ, an AI-based coronary imaging technology for its Azurion image-guided therapy platform, ahead of EuroPCR 2026. SmartIQ adds an ultra-low-dose protocol that uses more than 50% less X-ray radiation than the lowest settings of the earlier ClarityIQ technology, and a trial comparing the two has reached 60% enrolment across European sites.
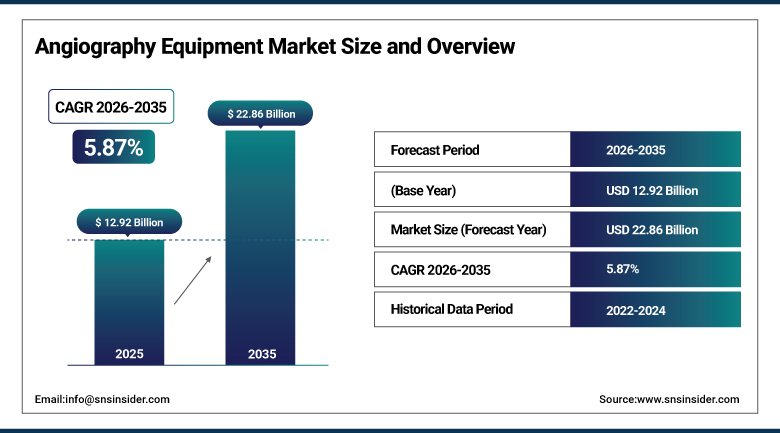
To Get more information Angiography Equipment Market - Request Free Sample Report
Angiography Equipment Market Trends
- Artificial intelligence that adjusts X-ray settings and lowers radiation dose automatically
- Hybrid rooms that combine angiography with CT for stroke and trauma care
- Shift of coronary and peripheral procedures to ambulatory surgical centers
- Local manufacturing of angiography systems in emerging markets
- Robotic and remote-assisted interventional procedures
- Growth of CT angiography as a non-invasive diagnostic option
U.S. Angiography Equipment Market Outlook
The U.S. Angiography Equipment Market was valued at USD 4.26 Billion in 2025 and is expected to reach USD 6.94 Billion by 2035, growing at a CAGR of 5.00% from 2026-2035.
The U.S. Angiography Equipment Market is the largest national market, supported by a high volume of coronary, peripheral and neurovascular procedures, a large installed base of catheterization laboratories and strong adoption of new imaging software. Hospitals and ambulatory centers renew systems on regular cycles to gain dose reduction and workflow features. Growth is moderated by capital budgets, pricing pressure from payers and a mature installed base.
⮞In May, 2026, Siemens Healthineers announced FDA clearance for six Artis interventional imaging systems: the Artis vision platform in floor, biplane, ceiling and robotic versions, plus Artis icono.explore and Artis genio floor systems. Each includes the Optiq AI imaging chain, which adjusts tube voltage, current and detector dose in real time to lower radiation while keeping image quality.
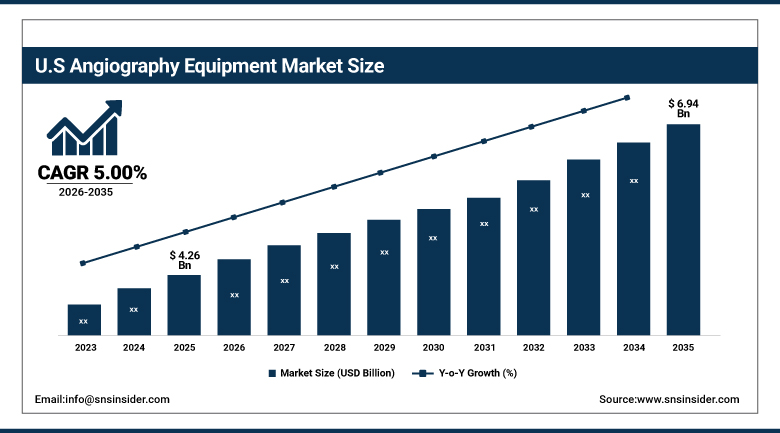
Angiography Equipment Market Segment Analysis
- By Product, angiography systems segment dominated the Angiography Equipment Market in 2025 with an estimated 44.00% share; catheters segment is the fastest-growing segment, with an estimated CAGR of 6.90% during 2026–2035.
- By Technology, X-ray angiography segment dominated the Angiography Equipment Market in 2025 with an estimated 57.00% share; CT angiography segment is the fastest-growing segment, with an estimated CAGR of 7.60% during 2026–2035.
- By Application, coronary angiography segment dominated the Angiography Equipment Market in 2025 with an estimated 46.00% share; neurovascular angiography segment is the fastest-growing segment, with an estimated CAGR of 7.80% during 2026–2035.
- By End User, hospitals segment dominated the Angiography Equipment Market in 2025 with an estimated 62.00% share; ambulatory surgical centers segment is the fastest-growing segment, with an estimated CAGR of 7.50% during 2026–2035.
By Product, Angiography Systems Dominates Angiography Equipment Market; Catheters to Register Fastest Growth.
Angiography systems dominate the Angiography Equipment Market because each catheterization laboratory needs a high-priced fixed C-arm or biplane system, and prices run into the hundreds of thousands of dollars per room. Hospitals replace systems every several years to gain dose reduction, image quality and workflow tools. Service contracts and software upgrades add further revenue for suppliers. Vendors increasingly sell packages that combine imaging, hemodynamic monitoring, intravascular imaging and software, which raises the value of each lab. Upgrades to image processing can often be installed on existing hardware, extending system life.
Catheters are projected to register the fastest growth because every diagnostic and interventional procedure uses them and procedure counts keep rising with an aging population. Newer designs offer better control, smaller diameters and access through the wrist, which improves comfort and shortens recovery. Hospitals buy large volumes, and suppliers add specialized catheters for neurovascular and peripheral cases. Single-use devices bring recurring revenue and are less dependent on hospital capital budgets. Manufacturers are also developing smart catheters with sensors, and hospitals are standardizing on a few preferred suppliers to gain volume discounts.
By Technology, X-Ray Angiography Dominates Angiography Equipment Market; CT Angiography to Register Fastest Growth.
X-ray angiography dominates the Angiography Equipment Market because it remains the standard for guiding catheters in real time during heart, brain and vascular procedures. It offers high resolution of small vessels and allows treatment during the same session. Interventional cardiologists and radiologists are trained on these systems, and hospitals have large installed fleets that are regularly upgraded. Newer detectors, faster rotation and 3D reconstruction add further capability, so a single room can handle diagnosis, planning and treatment. Robotic and remote-assisted systems are being added to selected rooms.
CT angiography is projected to register the fastest growth as it provides a non-invasive way to examine coronary and cerebral vessels and helps plan procedures. Faster scanners, lower contrast dose and artificial intelligence reading tools support its use in emergency departments and screening. Hybrid rooms that combine CT with angiography systems are also drawing investment. Photon-counting and spectral CT detectors are improving detail in small vessels, and automated analysis of plaque and flow helps referring physicians decide which patients need invasive angiography. This also supports use before elective procedures.
By Application, Coronary Angiography Dominates Angiography Equipment Market; Neurovascular Angiography to Register Fastest Growth.
Coronary angiography dominates the Angiography Equipment Market because heart disease is the leading cause of death worldwide and angiography remains the definitive way to see blocked arteries before stenting. Hospitals perform very large numbers of diagnostic and interventional heart procedures each year. Guidelines, chest pain pathways and reimbursement for stenting keep demand high. Heart procedures are supported by a large evidence base, clinical guidelines and well-established reimbursement. Intravascular imaging and physiology tools used with coronary angiography add to the value of each procedure.
Neurovascular angiography is projected to register the fastest growth as stroke treatment moves toward mechanical thrombectomy and as brain aneurysm care relies on catheter-based tools. Hospitals are building stroke centers, which need biplane systems with high image quality at low dose. Faster door-to-treatment targets support purchases of new systems and hybrid rooms. Robotic thrombectomy, flow diversion and liquid embolic agents are emerging, giving neurointerventionalists more options and encouraging hospitals to equip additional rooms. Telestroke networks help send patients quickly to capable centers.
By End User, Hospitals Dominates Angiography Equipment Market; Ambulatory Surgical Centers to Register Fastest Growth.
Hospitals dominate the Angiography Equipment Market because they handle emergency heart attacks, strokes and complex vascular surgery that need full catheterization laboratories and support teams. They have the capital budgets, trained staff and referral volumes to justify high-priced systems. Many operate several rooms, including hybrid operating suites that combine surgery and imaging. Large academic and community hospitals also use their rooms for electrophysiology and structural heart cases, spreading costs across more procedure types. Dedicated staff and nurse training programs support high utilization.
Ambulatory surgical centers are projected to register the fastest growth as payers encourage moving low-risk coronary and peripheral procedures out of hospitals to cut costs. Physician-owned centers buy compact, lower-cost systems and consumables for same-day procedures. Policy changes that allow more cardiac procedures in outpatient settings support the shift. Smaller centers can lower costs through shared service agreements and simplified workflows. Vendors offer financing and pay-per-use plans, which help new facilities begin operations without large upfront investments. Procedure bundles and bundled payments also encourage lower-cost settings.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
88.00 |
|
Asia Pacific |
China |
38.00 |
|
Europe |
Germany |
27.00 |
|
Latin America |
Brazil |
46.00 |
|
Middle East & Africa |
Saudi Arabia |
32.00 |
North America Angiography Equipment Market Insights
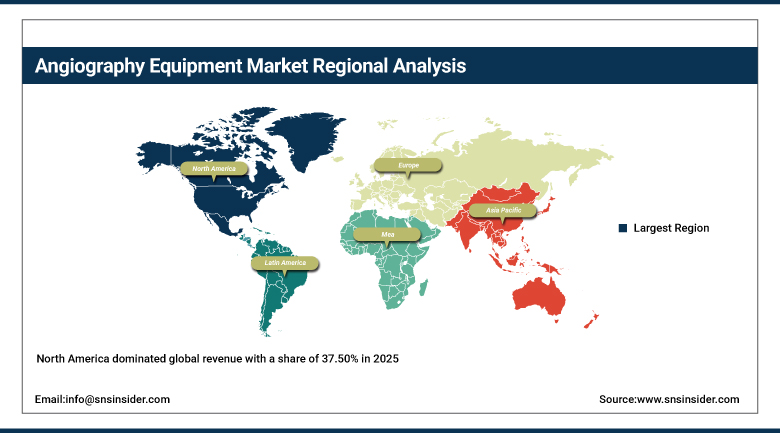
North America dominated revenue with a share of 37.50% in 2025. The United States accounts for dominant share of regional demand, with Canada adding volume. GE HealthCare, Siemens Healthineers, Philips, Canon Medical, Boston Scientific, Medtronic, Abbott and Terumo serve hospitals and outpatient centers. Group purchasing organizations and large hospital systems negotiate bundled contracts for systems and consumables, which gives suppliers strong incentives to offer full portfolios. Growth in outpatient cardiac catheterization is changing the type of systems purchased.
A high number of heart and vascular procedures, extensive reimbursement and quick adoption of AI-based tools support leadership. Hospitals invest in hybrid rooms and low-dose imaging, and outpatient centers are adding capacity. Capital budgets, payer pressure on procedure prices and a mature installed base moderate growth, though replacement of aging systems provides steady demand. Medical societies promote radiation safety and appropriate use, and regulators clear new software quickly. Companies also expand service networks and training, which helps retain customers over long equipment lifetimes.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Angiography Equipment Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 7.40% during 2026-2035. China leads regional demand, followed by Japan, India, South Korea and Australia. Canon Medical, Shimadzu, Fujifilm, Siemens Healthineers, Philips, GE HealthCare, United Imaging and Terumo supply the region, and local manufacturers are growing in China and India. Japan has a large installed base with high replacement rates, and South Korea and Australia are advanced markets. India and Southeast Asia show the fastest growth as new private hospital chains open catheterization laboratories.
Rising rates of heart disease and stroke, expanding hospital networks and government health programs are lifting installations of catheterization laboratories. Cath lab density in India and other countries remains low, leaving room for growth. Price sensitivity, uneven distribution of trained specialists and competition from local brands moderate growth, but large patient populations provide a wide base. Government schemes that cover heart procedures for low-income patients are widening access, and local production reduces import duties. Training programs for interventional cardiologists help build the skills required to use new systems effectively.
⮞In April, 2026, Siemens Healthineers announced local production of the Artis One Edition X angiography system at its Bengaluru factory, alongside mobile C-arms, CT scanners, MRI and digital radiography systems. The company tied the move to the Make in India initiative and cited India's cath lab density of 1.5 to 1.75 per million people.
Europe Angiography Equipment Market Insights
In Europe Germany, France, the United Kingdom, Italy and Spain lead regional demand. Siemens Healthineers, Philips, Canon Medical, Bracco Imaging, B. Braun and Terumo are among the suppliers serving public and private hospitals. Radiation protection rules and sustainability targets influence purchasing, and suppliers highlight lower energy use and recyclability. Cross-border tenders and shared procurement in some regions push prices down. Hospital mergers in several countries are consolidating purchasing and centralizing complex cases.
Strong public health systems, high rates of cardiovascular care and a focus on radiation safety support steady demand. Hospitals are upgrading to systems with dose-reduction software and adding hybrid rooms for stroke and structural heart care. Tight public budgets, long procurement cycles and a mature installed base moderate growth, though replacement purchases remain consistent. Clinical research networks run multi-country trials of new imaging and dose-reduction tools, and results often shape adoption elsewhere. Strong university hospitals act as early adopters and reference sites for suppliers.
⮞In November, 2025, Canon Medical announced FDA clearance for its Alphenix 4D CT with Aquilion One/Insight Edition, which combines the Alphenix Sky+ angiography system with a CT scanner in one room. The first clinical site is CHU Montpellier in France, and commercial availability was planned for summer 2026.
MEA & Latin America Angiography Equipment Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina, Colombia and Chile. Private hospital groups buy most advanced systems, while public hospitals expand more slowly. Currency swings and import costs restrain purchases, so refurbished systems are common. Private hospital groups in Brazil and Mexico lead adoption, and medical tourism supports demand for modern systems. Local distributors provide service, financing and training that international suppliers rely on. Public tenders in Latin America favor lower-priced options, while private buyers choose premium brands.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Turkey, South Africa and Egypt lead demand. Large hospital projects in the Gulf and rising heart disease rates support investment, while limited specialist staff and funding restrain growth across much of Africa. Gulf states are building specialist heart and stroke centers as part of national health plans, and regional hospital groups specify the latest hybrid rooms. Service capacity and trained staff remain constraints across many African countries.
Market Dynamics
Growth Drivers: Cardiovascular Burden, Minimally Invasive Care and AI Dose Reduction
Heart disease and stroke remain leading causes of death, and aging populations need more diagnostic and interventional procedures. Catheter-based treatment is replacing open surgery in many cases. Growth in diabetes and obesity adds to the number of patients with vascular disease. Public awareness campaigns and screening programs for heart disease also increase the number of patients referred for angiography each year, supporting higher procedure volumes.
Software that lowers radiation and contrast dose makes procedures safer for patients and staff, and gives hospitals a reason to replace older systems. Training programs for interventional physicians widen the number of operators able to use systems. Government funding for stroke and heart attack networks in many countries adds to purchases of new catheterization laboratory equipment and hybrid rooms.
Restraints: Capital Cost, Reimbursement and Radiation Concerns
Fixed angiography systems are expensive to buy, install and service, and smaller hospitals often postpone purchases or buy refurbished units. Lengthy purchasing cycles and the need for room renovation also slow replacement projects. Service costs and the need for trained technologists add to the total cost of ownership, which weighs on smaller hospitals when planning new rooms. Supply chain disruptions for detectors and tubes can delay installation schedules and raise prices for buyers.
Reimbursement pressure and concern about radiation and contrast exposure can limit procedure volumes in some settings. Shortages of cardiologists and technologists in some regions limit how many rooms can operate. Debate about the appropriate use of invasive diagnostic angiography, given non-invasive CT alternatives, may moderate procedure growth in some health systems.
Opportunities: Emerging Markets, Hybrid Rooms and Outpatient Procedures
Low cath lab density in India, China and other emerging markets leaves room for new installations, and local production lowers prices. Software subscriptions and service agreements create steady revenue for system makers. Local manufacturing and assembly can shorten delivery times, reduce import duties and make systems more affordable for hospitals in markets with limited budgets. Hospitals in smaller cities can then offer services nearer to patients, reducing travel for emergency heart and stroke care.
Hybrid rooms for stroke and structural heart care, and outpatient centers for routine procedures, open new buyers for compact systems and consumables. Portable and compact systems can bring angiography to smaller hospitals that cannot afford full rooms. Remote proctoring and teleradiology tools allow experts to support procedures at smaller sites, extending the reach of advanced interventional care.
Recent Developments:
- In May 2026, Philips unveiled SmartIQ, an AI-based coronary imaging technology for its Azurion platform, at EuroPCR 2026.
- In May 2026, Siemens Healthineers received FDA clearance for six Artis interventional imaging systems with Optiq AI.
- In April 2026, Siemens Healthineers announced local production of the Artis One Edition X angiography system in Bengaluru, India.
- In November 2025, Canon Medical announced FDA clearance for its Alphenix 4D CT interventional imaging system.
Angiography Equipment Market Key Players are:
- Siemens Healthineers AG
- Koninklijke Philips N.V.
- GE HealthCare Technologies Inc.
- Canon Medical Systems Corporation
- Shimadzu Corporation
- Boston Scientific Corporation
- Terumo Corporation
- Abbott Laboratories
- Medtronic plc
- Bracco Imaging S.p.A.
- Fujifilm Holdings Corporation
- B. Braun Melsungen AG
- Cardinal Health, Inc.
- Cordis
- Merit Medical Systems, Inc.
- MicroPort Scientific Corporation
- Stryker Corporation
- Cook Medical
- Bayer AG
- United Imaging Healthcare Co., Ltd.
Angiography Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 12.92 Billion |
| Market Size by 2035 | USD 22.86 Billion |
| CAGR | CAGR of 5.87% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Angiography Systems, Catheters, Guidewires, Contrast Media, and Others) • By Technology (X-Ray Angiography, CT Angiography, MR Angiography, and Others) • By Application (Coronary Angiography, Neurovascular Angiography, Peripheral Angiography, and Others) • By End User (Hospitals, Ambulatory Surgical Centers, and Diagnostic Imaging Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens Healthineers AG; Koninklijke Philips N.V.; GE HealthCare Technologies Inc.; Canon Medical Systems Corporation; Shimadzu Corporation; Boston Scientific Corporation; Terumo Corporation; Abbott Laboratories; Medtronic plc; Bracco Imaging S.p.A.; Fujifilm Holdings Corporation; B. Braun Melsungen AG; Cardinal Health, Inc.; Cordis; Merit Medical Systems, Inc.; MicroPort Scientific Corporation; Stryker Corporation; Cook Medical; Bayer AG; United Imaging Healthcare Co., Ltd. |

Frequently Asked Questions
Key players include Siemens Healthineers AG, Koninklijke Philips N.V., GE HealthCare Technologies Inc., Canon Medical Systems Corporation, Shimadzu Corporation, Boston Scientific Corporation, Terumo Corporation and Abbott Laboratories.
Key opportunities include new installations in emerging markets, hybrid rooms for stroke and structural heart care, and outpatient procedure centers.
The major growth factor is the rising burden of heart disease and stroke, together with the shift to minimally invasive catheter-based treatment.
By Product, the Angiography Systems segment dominated the market in 2025 with an estimated 44.00% share, supported by the high price of fixed C-arm systems in catheterization laboratories.
North America dominated the market with a share of 37.50% in 2025, driven by high procedure volumes, reimbursement and quick adoption of new imaging software.
