
Contrast Media Market Report Scope & Overview:
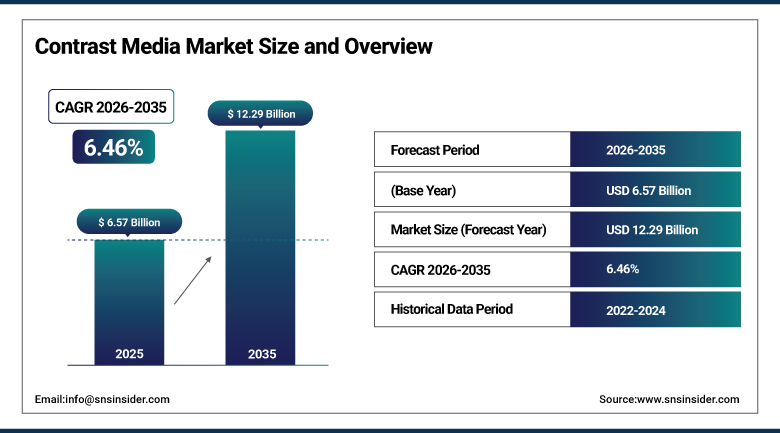
The Contrast Media Market was valued at USD 6.57 Billion in 2025 and is expected to reach USD 12.29 Billion by 2035, growing at a CAGR of 6.46% from 2026-2035.
The Contrast Media Market is expanding as imaging volumes rise with chronic disease, population aging and wider use of computed tomography and magnetic resonance imaging. Iodinated agents remain the largest group because they support routine CT and angiography. Gadolinium agents are moving toward macrocyclic and lower dose formulas. Ultrasound microbubbles are gaining use in cardiac and liver imaging. Suppliers are expanding fill and finish capacity after the shortage of 2022. Artificial intelligence is helping reduce the dose needed for diagnostic quality images. Safety concerns about kidney injury and gadolinium retention continue to shape product choice. Price pressure from tenders and generics also affects margins. The market is expected to grow as new low dose agents reach clinics.
⮞In June 2026, Bayer received FDA approval for gadoquatrane (Ambelvist), a macrocyclic MRI agent that the company says contains 60% less gadolinium than agents dosed at 0.1 mmol per kilogram. The approval shows how suppliers are lowering the gadolinium dose to address safety concerns.
To Get more information Contrast Media Market - Request Free Sample Report
Contrast Media Market Trends
-
Shift toward macrocyclic and lower dose gadolinium agents for magnetic resonance imaging
-
Expansion of iodinated contrast manufacturing and fill and finish capacity to secure supply
-
Growing use of microbubble agents in cardiac, liver and vascular ultrasound
-
Use of artificial intelligence to reduce contrast dose while preserving image quality
-
Growth of local manufacturers in China and India through national procurement and essential drug lists
U.S. Contrast Media Market Outlook
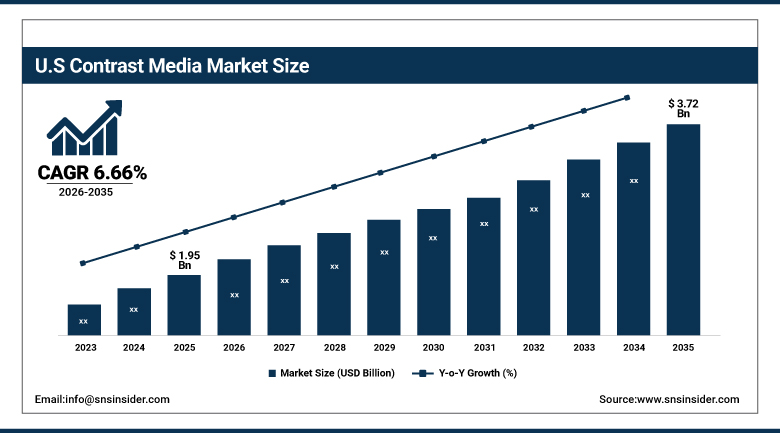
The U.S. Contrast Media Market was valued at USD 1.95 Billion in 2025 and is expected to reach USD 3.72 Billion by 2035, growing at a CAGR of 6.66% from 2026-2035.
The U.S. Contrast Media Market is the largest national market and is supported by a high volume of CT and MRI examinations in hospitals and outpatient centers. Cancer staging, stroke assessment and cardiac imaging use contrast agents daily. U.S. manufacturing of iodinated agents expanded after the shortage of 2022. The Food and Drug Administration has approved new low dose gadolinium and ultrasound agents in recent years. Group purchasing organizations negotiate prices, which limits pricing power for suppliers. Generic iodinated products add competition. Concerns about kidney function and gadolinium retention guide agent selection. Demand is therefore expected to grow with imaging volumes and the shift toward newer agents.
⮞For instance, in July 2026, Amneal cited IQVIA data showing U.S. iohexol injection sales of about USD 706 million for the 12 months to May 2026, as the FDA approved additional strengths of its iohexol injection. The figure shows the scale of the U.S. iodinated market that generic suppliers are entering.
Contrast Media Market Segment Analysis
-
By Product, the Iodinated Contrast Media segment dominated the Contrast Media Market with approximately 66.91% share in 2025, while the Microbubble Contrast Media segment is the fastest growing with a CAGR of approximately 9.02%.
-
By Modality, the X-ray and CT segment dominated the Contrast Media Market with approximately 60.17% share in 2025, while the Ultrasound segment is the fastest growing with a CAGR of approximately 7.89%.
-
By Route of Administration, the Intravascular segment dominated the Contrast Media Market with approximately 69.48% share in 2025, while the Rectal segment is the fastest growing with a CAGR of approximately 7.19%.
-
By Application, the Cardiovascular Disorders segment dominated the Contrast Media Market with approximately 32.51% share in 2025, while the Oncology segment is the fastest growing with a CAGR of approximately 9.73%.
-
By End User, the Hospitals and Clinics segment dominated the Contrast Media Market with approximately 61.44% share in 2025, while the Diagnostic Imaging Centers segment is the fastest growing with a CAGR of approximately 8.33%.
By Product, Iodinated Contrast Media Dominates the Contrast Media Market and Microbubble Contrast Media Grows Fastest
Iodinated contrast media lead the market because they are the standard agents for computed tomography, angiography and many interventional procedures. Hospitals rely on them for emergency, cancer and cardiac imaging, and low osmolar and iso-osmolar formulas have improved patient tolerance. Several suppliers hold broad portfolios and long-term contracts, which supports stable volumes. Generic versions are available in many countries, and they widen access in price-sensitive health systems. Radiology departments also keep multiple concentrations in stock to match examination protocols and body regions. Hospitals also stock several concentrations and container sizes, which supports repeat purchases from the same supplier throughout the year.
Microbubble agents are growing fastest as ultrasound moves into liver lesion characterization, echocardiography and vascular assessment. These agents carry no kidney burden and can be used at the bedside, which suits patients who cannot receive iodinated or gadolinium products. New pediatric labels and approvals for additional indications are widening the user base. Manufacturers are investing in training for sonographers, and software that quantifies perfusion is improving confidence in results, which supports adoption in hospitals and imaging centers. Pharmacy teams value agents that are easy to prepare, and prefilled packaging shortens setup time between patients, which supports steady adoption.
⮞For example, in May 2026, the FDA cleared the ACIST Pro Diagnostic System, a variable-rate contrast management system for cardiac catheterization labs. The company cites data from its predecessor system showing about 45 milliliters less contrast per case. The clearance shows how suppliers are reducing iodinated contrast use per procedure.
By Modality, X-ray and CT Dominates the Contrast Media Market and Ultrasound Grows Fastest
X-ray and computed tomography account for most contrast use because CT is the workhorse of emergency and oncology imaging. A single CT examination often uses a large volume of an iodinated agent, which makes this modality the main driver of revenue. Wider availability of scanners in hospitals and outpatient centers is lifting examination counts. Multi-phase protocols for liver, pancreas and vascular studies increase the amount of agent used for each patient. Radiologists also use contrast for fluoroscopy and interventional guidance. Imaging departments plan their purchases around expected scan volumes, so growth in CT capacity translates directly into higher agent orders.
Ultrasound is the fastest growing modality as microbubble agents extend the reach of a low cost and radiation-free technology. Point of care systems and portable scanners allow contrast enhanced studies at the bedside and in outpatient clinics. Clinical guidelines now recommend contrast ultrasound for focal liver lesions and for cardiac chamber opacification in selected patients. Magnetic resonance imaging continues to expand in neurology and oncology, and gadolinium agents with higher relaxivity are allowing lower doses, which helps this modality keep a stable share. Sonographers and cardiologists are being trained on contrast protocols, and professional societies are issuing guidance that supports wider use in routine practice.
⮞In June 2026, Subtle Medical received FDA clearance for SubtleHD for CT, an image enhancement software, and said its technology is used on more than 1,300 scanners worldwide. The clearance shows how software is being paired with CT to support lower contrast dose protocols.
By Route of Administration, Intravascular Dominates the Contrast Media Market and Rectal Grows Fastest
Intravascular administration leads because most CT, MRI and angiography agents are injected into a vein or artery. Power injectors deliver precise volumes and flow rates, which supports consistent image quality. Hospitals prefer prefilled syringes and large bulk packs that reduce preparation time and waste. Intravascular products represent the highest priced agents, and regulatory approvals for new molecules are almost always for this route, so innovation spending is concentrated here. Radiology departments prefer standardized kits that combine the agent, tubing and injector interface, which simplifies workflows and supports long supply contracts.
Rectal administration is growing fastest from a small base as clinicians use contrast enemas and enteral protocols for pelvic, colorectal and pediatric assessment. Better formulations improve coating and patient comfort, and wider use of CT colonography is supporting demand. Oral agents remain important for abdominal CT, particularly for emergency evaluation of bowel disease. Suppliers are developing flavored and low volume products to improve patient acceptance, which supports steady use of non-injected routes. Pediatric and elderly patients benefit from enteral and rectal options in selected studies, so these routes keep a role even as injectable agents dominate.
⮞In April 2025, Beijing Beilu Pharmaceutical reported a Dutch Medicines Evaluation Board marketing authorisation for its iohexol injection at 350 milligrams of iodine per milliliter. The authorisation shows how Chinese makers are extending intravascular iodinated products into European markets.
By Application, Cardiovascular Disorders Dominates the Contrast Media Market and Oncology Grows Fastest
Cardiovascular disorders lead application demand because coronary angiography, stent placement, peripheral vascular studies and CT angiography all depend on contrast agents. Heart disease is the leading cause of death worldwide, and screening programs are expanding the number of cardiac CT examinations. Echocardiography with microbubbles is also used to assess heart function in patients with poor image windows. Interventional cardiology procedures continue to rise, and they often involve several injections in one session. Neurology and gastroenterology also draw large volumes, but cardiac and vascular studies need more repeat imaging, which keeps their consumption higher.
Oncology is growing fastest because cancer staging, treatment planning and response monitoring all rely on contrast enhanced CT and MRI. Rising cancer incidence and longer survival increase the number of follow-up scans per patient. Liver, brain and breast imaging use gadolinium agents, while body CT uses iodinated agents. Molecular imaging and theranostics add further demand for related diagnostic agents. Neurological disorders remain a large application, driven by stroke protocols and brain tumor assessment. Interventional oncology procedures, including liver embolization and tumor ablation guidance, further increase contrast use in this segment.
⮞For instance, in July 2026, Imagion Biosystems renewed and extended its collaboration with Siemens Healthineers for the Phase 1b/2 trial of MagSense, an MRI contrast agent for HER2 breast cancer. The trial shows continuing research on contrast agents for oncology imaging.
By End User, Hospitals and Clinics Dominates the Contrast Media Market and Diagnostic Imaging Centers Grows Fastest
Hospitals and clinics account for the largest share because they treat emergency, inpatient and oncology patients who require contrast enhanced imaging. They operate the highest number of CT scanners and interventional suites. Purchasing is done through tenders and group contracts, which favors suppliers with broad portfolios and reliable supply. Hospital pharmacies manage storage and dose tracking, and they increasingly adopt prefilled syringes and automated dose records to reduce waste and error. Larger systems consolidate buying across many sites, which helps hospitals secure better prices while keeping stocks of the main agents at all times.
Diagnostic imaging centers are growing fastest as health systems shift outpatient imaging away from hospitals to lower cost sites. These centers focus on CT and MRI for oncology follow-up, musculoskeletal and neurological studies. Large chains are expanding in the United States, India and China, and they negotiate volume discounts. Imaging centers value fast throughput and standard protocols, which supports demand for ready-to-use packaging and compatible injector systems. Teleradiology links and shared scanners among clinics also support the spread of contrast enhanced examinations beyond large academic hospitals.
⮞In September 2025, more than 74,000 patients in England waited over six weeks for a CT or MRI scan, according to analysis by the Royal College of Radiologists reported in December 2025. The backlog shows the pressure on hospital imaging capacity.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
74.91 |
|
Europe |
Germany |
24.38 |
|
Asia Pacific |
China |
41.72 |
|
Latin America |
Brazil |
46.53 |
|
Middle East & Africa |
Saudi Arabia |
28.69 |
North America Contrast Media Market Insights
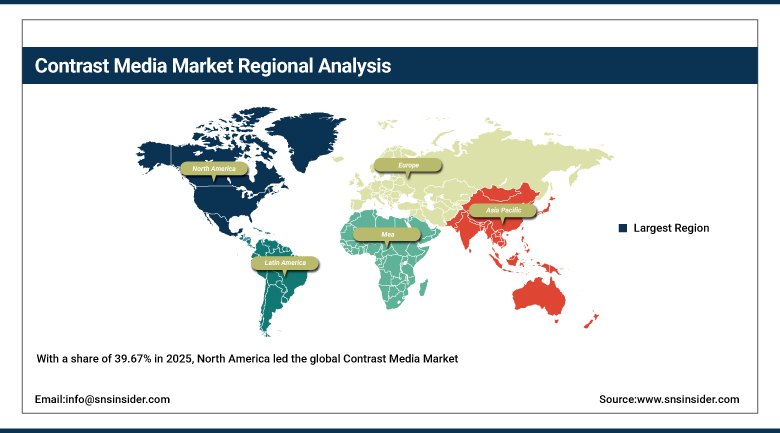
With a share of 39.67% in 2025, North America led the global Contrast Media Market. The United States provides most of the regional demand through a high number of CT and MRI examinations, advanced cancer care and a large interventional cardiology sector. Canada adds steady volumes through provincial health systems. Major suppliers operate regional plants and fill and finish sites, and they have expanded capacity since the iodinated contrast shortage of 2022. Group purchasing organizations shape pricing, which keeps competition among branded and generic suppliers active. The presence of leading academic centers speeds the adoption of new agents and protocols.
Regulatory approvals by the Food and Drug Administration of low dose gadolinium products and new ultrasound uses are changing the product mix. Radiology departments are adopting artificial intelligence reconstruction that lowers dose while preserving diagnostic image quality. Mexico adds growing imaging capacity through private hospital groups. Outpatient imaging centers are expanding, which shifts contrast use from hospitals to lower cost settings and increases demand for prefilled syringes and standardized packaging. Hospital mergers and large outpatient chains are increasing standardization of products, which favors suppliers with broad portfolios and consistent delivery.
⮞In November 2025, the International Contrast Ultrasound Society reported that the CMS final rule for 2026 raised Medicare payment for non-cardiac contrast-enhanced ultrasound to USD 358.35, effective January 1, 2026. The change improves the economics of ultrasound contrast in U.S. hospitals.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Contrast Media Market Insights
Europe is the second largest region, with Germany, France, the United Kingdom, Italy and Spain leading demand. Several of the leading contrast media makers are headquartered in the region, including Bayer in Germany, Guerbet in France and Bracco in Italy. National health systems purchase through tenders, and price reductions have limited revenue growth. Aging populations and cancer screening programs support steady imaging volumes. Germany has a large installed base of CT and MRI scanners, which sustains consumption. Pharmacovigilance is strict, and safety reviews influence labeling and clinical practice across member states within months of new findings.
European regulators have restricted linear gadolinium agents, which moved MRI practice toward macrocyclic products. The Medical Device Regulation and pharmaceutical supply rules add compliance costs. Nordic countries produce iodinated agents in Norway, and new capacity investments aim to reduce dependence on single sites. Eastern European countries are expanding scanner access, which adds demand for generic iodinated products. Radiology societies promote dose optimization, which encourages the use of lower concentration formulas. Large university hospitals in Germany, France and the United Kingdom also lead clinical trials for new MRI agents, which helps local suppliers launch products early.
⮞For instance, in November 2025, NHS England reported 8,345,600 CT scans in 2024/25 within its annual imaging dataset. The volume shows the scale of contrast-enabled imaging demand in a European public system.
Asia Pacific Contrast Media Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 8.14% during 2026-2035. China, Japan, India, South Korea and Australia lead regional demand. China is the largest market in the region, and local makers have gained volume through national procurement and the essential drug list. Japan has a high number of CT and MRI scanners per capita and a large older population. India is expanding diagnostic chains, and domestic makers supply generic iodinated and gadolinium products. Large hospital groups in major cities are adding advanced CT and high field MRI systems, which raises the use of contrast agents in oncology and neurology.
Rising cancer and cardiovascular disease, growing insurance coverage and new hospital construction are lifting imaging volumes. South Korea has several local suppliers and exports to neighboring markets. Southeast Asian countries are adding scanners, which creates demand for affordable generic agents. International suppliers are building local plants and partnerships to keep pace with price pressure. Governments are also supporting domestic manufacturing of high-value agents, which is shifting competition in the region. Contract manufacturers in the region also supply active ingredients and finished vials to global brands, which links regional capacity to global supply.
⮞In July 2026, Guerbet reported Asia revenue of EUR 87.7 million for the first half of 2026, a decline of 5.0%. The result shows the pricing pressure and procurement changes facing multinational suppliers in the region.
MEA & Latin America Contrast Media Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Public health systems and private hospital groups purchase through tenders, and import dependence exposes prices to currency changes. Growth is supported by expanding scanner access in private clinics and rising cancer detection. Local distribution partners are important for international suppliers because they manage registration, storage and delivery across large countries. Private laboratories and diagnostic chains in São Paulo and Mexico City are growing, and they negotiate contrast supply directly with international suppliers.
In the Middle East and Africa, Saudi Arabia and the United Arab Emirates lead demand through new hospitals, medical cities and health tourism. South Africa has a developed private imaging sector, while many other African countries have limited scanner access. Government healthcare programs in the Gulf encourage adoption of advanced imaging, and suppliers are signing distribution agreements with regional partners. Budget limits slow growth in lower income countries, yet generic iodinated agents are improving access. Medical tourism and new hospital projects in Dubai and Riyadh add demand for premium low osmolar and macrocyclic agents.
⮞In July 2026, Bracco received approval in Mexico for VUEWAY (gadopiclenol), which the company says is now approved in 38 countries. The approval shows the expansion of low dose MRI agents in Latin America.
Market Dynamics
Growth Drivers: Rising Imaging Volumes and Chronic Disease
Rising chronic disease is the main driver of contrast media demand. Cancer, cardiovascular disease and neurological disorders require imaging for diagnosis, treatment planning and follow-up. Longer survival increases the number of scans per patient over time. Population aging in Japan, Europe and North America adds to the pool of patients who need frequent imaging. Each CT or MRI examination that uses an agent creates a direct sale, so scan growth turns quickly into revenue for suppliers. Each new scanner installed in a hospital raises the base of potential injections, and consumption rises as radiologists add multi-phase protocols.
Technology advances also lift volumes. Faster CT scanners, photon-counting detectors and high-field MRI create higher resolution images that depend on contrast agents for tissue differentiation. New low dose agents and injector protocols make contrast examinations safer for patients with kidney disease, which widens the eligible population. Screening programs for lung, heart and liver disease and the expansion of outpatient imaging centers are adding further examinations in both developed and emerging economies. Emerging economies add scanners rapidly, and growth in insurance coverage lets more patients receive contrast enhanced studies.
⮞In July 2026, GE HealthCare reported second quarter Pharmaceutical Diagnostics revenue of USD 843 million. The result reflects strong demand for contrast media and related diagnostic agents.
Restraints: Safety Concerns and Supply Disruptions
Safety concerns restrain use of certain agents. Contrast-induced kidney injury is a risk with iodinated products in patients with impaired kidney function, and nephrogenic systemic fibrosis is linked to some gadolinium agents. Retention of gadolinium in the brain and other tissues has led regulators to restrict linear agents and require stronger warnings. Radiologists therefore avoid contrast when possible and choose non-contrast techniques, which reduces the number of agent doses sold. Regulators monitor adverse events closely, and label changes can shift clinical practice quickly.
Supply disruptions are a second restraint. Iodine and gadolinium inputs are concentrated in a few countries, and production of finished agents relies on a small number of sites. The shutdown of a major plant in 2022 caused shortages in the United States and forced hospitals to ration contrast. Price pressure from tenders and generics also limits margins, and new plant investments require long approval periods. These factors moderate the pace of market growth. Procurement tenders reward low prices, so suppliers may delay investment when margins narrow. Approval timelines for new sites and products are long, and any quality issue at a single plant can interrupt supply to many hospitals at once.
⮞For example, in 2022, the shutdown of GE HealthCare's Shanghai plant, which made about 80% of its iodinated contrast, led to shortages across U.S. hospitals. The episode shows the concentration risk in iodinated supply.
Opportunities: Low Dose Agents and Gadolinium-Free Alternatives
Low dose gadolinium agents present a significant opportunity. High relaxivity drugs make possible use of smaller amounts of gadolinium without any deterioration of picture quality, addressing the concern directly. Hospitals are ready to switch to these agents based on clinical evidence of equal efficacy, while several new products were already approved by regulators. The manufacturers who get early approval in big markets will gain market share from older agents and establish long-term ties with radiology associations. Pediatric labeling and half-dose indications expand the patient base and make switching to newer products a clear choice for hospitals.
Other opportunities include gadolinium-free agents, microbubble agents and artificial intelligence. Manganese and iron-based MRI agents are currently under development or were approved, targeting the patients with kidney diseases. The software that helps to construct images based on small amounts of contrast material can be added to the portfolio of agents. The growth of emerging markets with increasing availability of scanners creates demand for cost-effective products. Companies, which possess both safe molecules and good supply chains, will have an edge. Collaboration between drug makers and software companies is forming the bundles of molecules with picture enhancing software. Hospitals will be able to implement standardized procedures
⮞In October 2024, Bracco and Subtle Medical received FDA clearance for AiMIFY, deep learning software that boosts contrast enhancement on brain MRI up to two times the effect of a single labeled gadolinium dose. The clearance shows software extending the value of lower doses.
Recent Developments:
-
In January 2025, GE HealthCare invested USD 138 million in its Cork, Ireland contrast media manufacturing site. The expansion adds 25 million patient doses of annual capacity by the end of 2027 and supports supply reliability for iodinated agents.
-
In October 2025, Azurity Pharmaceuticals received FDA approval for Ferabright (ferumoxytol), the first iron-based contrast agent indicated for MRI of the brain. The product adds a non-gadolinium option for brain imaging.
-
In August 2026, Lantheus received FDA approval for Tauklarify, a tau PET imaging agent for Alzheimer's disease. The label is supported by trials with more than 500 subjects and widens the company's neurology diagnostic portfolio.
-
In July 2026, Jiangsu Hengrui Pharmaceuticals announced that its ioversol injection was added to China's 2026 National Essential Drugs List, effective September 1, 2026. The listing improves access to domestically produced iodinated contrast in public hospitals.
Contrast Media Market Key Players
-
Bayer AG
-
GE HealthCare Technologies Inc.
-
Bracco Imaging S.p.A.
-
Guerbet
-
Lantheus Holdings, Inc.
-
Jiangsu Hengrui Pharmaceuticals Co., Ltd.
-
Beijing Beilu Pharmaceutical Co., Ltd.
-
Azurity Pharmaceuticals, Inc.
-
J.B. Chemicals & Pharmaceuticals Ltd.
Contrast Media Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.57 Billion |
| Market Size by 2035 | USD 12.29 Billion |
| CAGR | CAGR of 6.46% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Iodinated Contrast Media, Gadolinium-Based Contrast Media, Microbubble Contrast Media, Barium-Based Contrast Media, and Other Products) • By Modality (X-ray and CT, MRI, and Ultrasound) • By Route of Administration (Intravascular, Oral, Rectal, and Other Routes) • By Application (Cardiovascular Disorders, Neurological Disorders, Oncology, Gastrointestinal Disorders, and Other Applications) • By End User (Hospitals and Clinics, Diagnostic Imaging Centers, and Other End Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bayer AG, GE HealthCare Technologies Inc., Bracco Imaging S.p.A., Guerbet, Lantheus Holdings, Inc., Jiangsu Hengrui Pharmaceuticals Co., Ltd., Beijing Beilu Pharmaceutical Co., Ltd., Azurity Pharmaceuticals, Inc., J.B. Chemicals & Pharmaceuticals Ltd. |

Frequently Asked Questions
Key players include Bayer AG, GE HealthCare, Bracco Imaging, Guerbet, Lantheus Holdings, Jiangsu Hengrui Pharmaceuticals, Beijing Beilu Pharmaceutical, Azurity Pharmaceuticals and J.B. Chemicals & Pharmaceuticals.
Key opportunities include low dose gadolinium agents, gadolinium-free MRI agents, microbubble products for ultrasound and growing scanner access in emerging markets.
Rising imaging volumes driven by cancer, cardiovascular disease and population aging are the main growth factor, supported by wider CT and MRI access and new low dose agents.
By Product, the Iodinated Contrast Media segment dominated the market in 2025 with an estimated 66.91% share, supported by routine CT, angiography and interventional procedures.
North America dominated the market with a share of 39.67% in 2025, driven by high CT and MRI volumes, advanced cancer care and early adoption of new agents.
