
Artificial Hip Joint Market Report Scope & Overview:
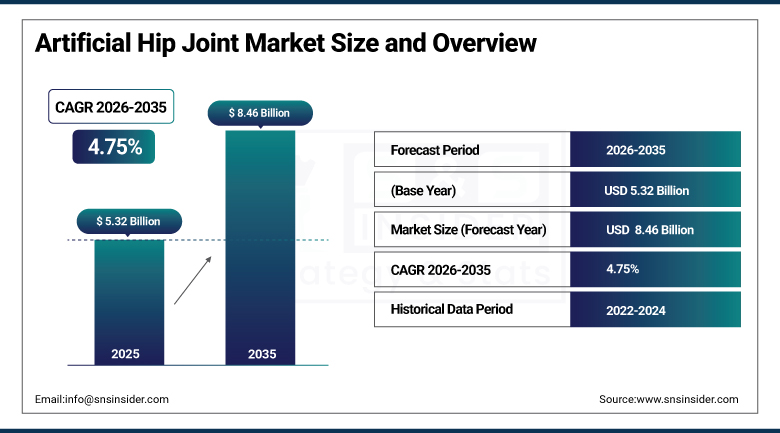
The Artificial Hip Joint Market was valued at USD 5.32 Billion in 2025 and is expected to reach USD 8.46 Billion by 2035, growing at a CAGR of 4.75% from 2026-2035.
Artificial hip joints represent a fundamental product line in orthopedic reconstructive surgery, comprised of femoral stems, acetabular cups, and wear surfaces that serve to provide movement and reduce pain in people suffering from osteoarthritis, rheumatoid arthritis, and hip fractures due to trauma. The ongoing increase in life expectancy rates throughout the world, higher levels of obesity, and growing numbers of degenerative joint disorders have only been serving to expand the number of patients who require surgery in order to restore their hip joints. Hospitals, orthopedic centers, and ambulatory surgical centers all depend upon this equipment to restore joint function and reduce pain in the long run. The market will continue to grow due to increasing adoption of robotic-assisted surgery systems, innovation in the area of wear-resistant bearing materials, and government funding of orthopedic care facilities.
On October 30, 2024, Zimmer Biomet announced the broad commercial launch of its Z1 Femoral Hip System at the American Association of Hip and Knee Surgeons annual meeting. The triple-taper femoral system pairs with the company's G7 Acetabular System to provide surgeons with a versatile, streamlined total hip arthroplasty solution.
To Get more information On Artificial Hip Joint Market - Request Free Sample Report
Artificial Hip Joint Market Trends:
-
Rising adoption of robotic-assisted and handheld surgical impaction systems improving implant placement precision.
-
Growing preference for ceramic bearing surfaces offering lower wear rates and reduced ion release.
-
Expanding use of antibacterial and iodine-treated implant coatings addressing periprosthetic joint infection.
-
Increasing migration of primary hip procedures toward ambulatory surgical center settings.
-
Rising integration of AI-powered fluoroscopy and surgical guidance platforms into total hip arthroplasty.
-
Growing manufacturer investment in triple-taper femoral stem systems supporting anatomical fit flexibility.
U.S. Artificial Hip Joint Market Overview:
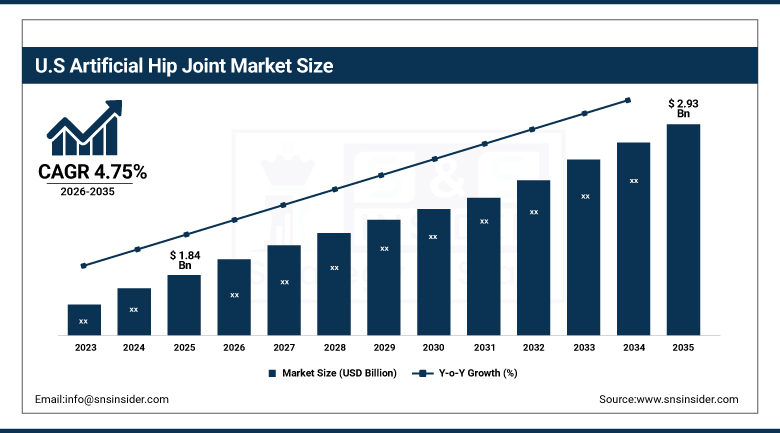
The U.S. Artificial Hip Joint Market was valued at USD 1.84 Billion in 2025 and is expected to reach USD 2.93 Billion by 2035, growing at a CAGR of 4.75% from 2026-2035.
Domestic demand is still driven by the presence of a large and aging base of patients who require hip reconstruction, along with a quick uptake of the latest surgical tools in hospitals and ambulatory care centers. Key players are launching automated impactor devices and triple taper femoral implants, while the pipeline for domestic regulatory approvals is very active.
On February 8, 2024, Zimmer Biomet introduced HAMMR, an automated Hip Impaction System for bone preparation and implant placement during hip replacement surgery. The company stated that the device strengthens its portfolio of automated surgical instruments, helping surgeons achieve customized control, precision, and energy levels during total hip arthroplasty.
Artificial Hip Joint Market Segment Analysis:
-
By Material Type, the Metal-on-Polyethylene segment dominated the market with a 44.60% share in 2025, while the Ceramic-on-Ceramic segment is the fastest growing with a CAGR of 7.85% during 2026-2035.
-
By Fixation Type, the Cemented segment dominated the market with a 52.30% share in 2025, while the Hybrid Fixation segment is the fastest growing with a CAGR of 7.40% during 2026-2035.
-
By Application, the Primary segment dominated the market with an 81.70% share in 2025, while the Revision segment is the fastest growing with a CAGR of 6.95% during 2026-2035.
-
By End-User, the Hospitals segment dominated the market with a 58.40% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of 7.60% during 2026-2035.
By Material Type, Metal-on-Polyethylene Dominates the Market and Ceramic-on-Ceramic Grows Fastest
Metal-on-Polyethylene bearings dominated the market in 2025, a position built on decades of accumulated clinical evidence, predictable wear characteristics, and a cost structure that continues to make this combination the default specification across the vast majority of primary hip procedures worldwide. Surgeons favour this bearing combination precisely because it delivers dependable long-term performance without demanding the specialised manufacturing tolerances or elevated component costs that harder bearing surfaces require, a combination that keeps the format relevant even as more advanced material categories continue to expand around it. This everyday reliability, spanning community hospitals through large academic medical centers, keeps metal-on-polyethylene central to routine hip reconstruction across virtually every healthcare setting globally, sustaining recurring procurement even as surgeon preference gradually shifts toward newer bearing technology for younger, more active patients.
Ceramic-on-Ceramic bearings are projected to be the fastest-growing material category over the forecast period. Younger and more active patients increasingly favour this bearing combination for its markedly lower wear rates and reduced metal ion release relative to conventional alternatives, while continued advancement in ceramic manufacturing processes keeps reducing the fracture risk that historically limited broader adoption. As surgeons increasingly extend hip replacement candidacy to younger patients expecting decades of implant longevity, this segment continues to pull ahead of traditional bearing categories in overall percentage growth even as metal-on-polyethylene retains the larger overall procedure volume.
By Fixation Type, Cemented Dominates the Market and Hybrid Fixation Grows Fastest
The cemented fixation system was dominant in the year 2025. The experience in the use of this method in the clinic, the immediate stability and compatibility with older patients who have lower bone density still make it a strong position holder in the wider range of fixation techniques, especially in areas where the training of surgeons is still based on this method. This method has been used by hospitals and clinics for older patients and revision surgery, as well.
Hybrid Fixation, which combines a cemented femoral stem with an uncemented acetabular cup, is expected to grow fastest among fixation categories over the forecast period. This approach continues to gain favour as surgeons seek to combine the proven femoral-side stability of cemented technique with the theoretical longevity benefits of cementless acetabular fixation. This segment continues to expand as younger and moderately active patients increasingly present favourable bone quality for uncemented acetabular fixation while still benefiting from the reliability of cemented femoral technique. Continued rollout of surgeon training programs is expected to keep reinforcing hybrid fixation's growth relative to fully cemented or fully uncemented approaches.
By Application, Primary Dominates the Market and Revision Grows Fastest
Primary hip replacement procedures dominated the market in 2025. Initial joint reconstruction for patients with osteoarthritis, rheumatoid arthritis, and traumatic hip fractures remains the single largest driver of overall procedure volume worldwide, spanning both elective and urgent surgical contexts across virtually every healthcare system globally. This foundational clinical role continues to sustain primary procedures as the largest application category by a clear margin, even as revision surgery continues gaining ground as a growing share of the installed implant base reaches the end of its functional service life.
Revision procedures are projected to expand fastest over the forecast period. A growing population of patients who received primary implants one to two decades ago are now presenting with implant wear, loosening, or periprosthetic joint infection requiring surgical revision, giving surgeons a steadily expanding pool of technically demanding cases to address. As implant registries continue tracking long-term device performance and surgeons gain better visibility into failure patterns, revision procedures continue closing the gap with primary surgery in overall market demand.
By End-User, Hospitals Dominates the Market and Ambulatory Surgical Centers Grows Fastest
Hospitals dominated the market in 2025. The scale and complexity of cases handled within hospital orthopedic departments, spanning elective primary surgery through complex revision procedures and extended inpatient recovery monitoring, continues to require the broadest and most comprehensive surgical infrastructure of any single care setting. This breadth of clinical capability, combined with the sheer patient volume that major hospital systems process daily, continues to sustain hospitals as the clear leading end-user category across the broader market.
Ambulatory Surgical Centers are expected to be the fastest-growing end-user category over the forecast period. A steady shift of lower-complexity primary hip procedures toward outpatient settings continues pulling demand away from traditional inpatient care, as both providers and payers increasingly favour the lower cost base these facilities typically offer relative to full hospital admission for appropriately selected, healthier patients. This structural shift toward outpatient delivery is expected to continue reshaping end-user demand patterns well beyond the current forecast horizon.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
82.60% |
|
Europe |
Germany |
31.90% |
|
Asia Pacific |
China |
37.40% |
|
Latin America |
Brazil |
46.80% |
|
Middle East & Africa |
United Arab Emirates |
33.50% |
North America Artificial Hip Joint Market Insights
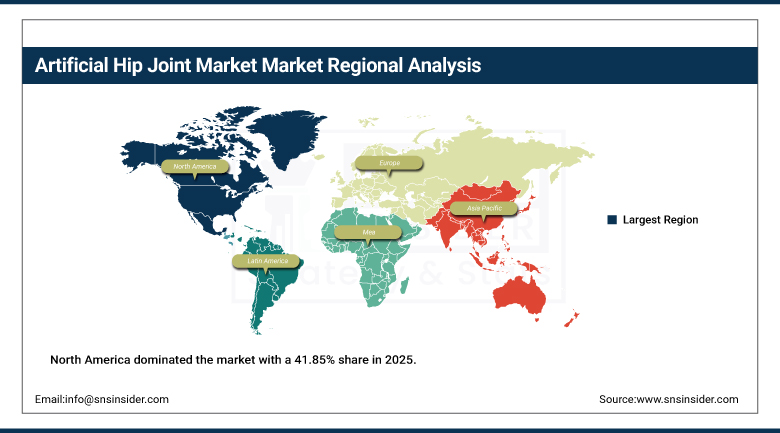
North America dominated the market with a 41.85% share in 2025. A substantial and ageing patient population, a dense concentration of leading implant manufacturers headquartered within the region, and swift regulatory clearance for next-generation surgical instrumentation continue to anchor this leadership position across both hospital and ambulatory care settings. Robotic-assisted and handheld impaction systems keep extending well beyond flagship academic medical centers into community hospitals and outpatient surgical facilities, as surgeons and health systems alike grow increasingly comfortable relying on automated instrumentation rather than fully manual technique alone, reinforcing the region's position at the technological forefront of this industry.
Canada contributes steady incremental demand as its provincial health systems continue widening surgical access to hip reconstruction across both urban and rural communities. Continued investment in robotic-assisted platforms and antibacterial implant coatings across the broader region is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets that continue building out orthopedic care infrastructure from a considerably smaller existing base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Artificial Hip Joint Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 7.30% during 2026-2035, supported by rising healthcare spending, expanding hospital infrastructure, and growing public awareness of joint replacement surgery across an enormous and rapidly ageing population base. China continues to anchor regional demand as hospital networks expand orthopedic surgical capability across both established urban medical centers and rapidly developing regional healthcare facilities, supported by sustained government investment in modernising the country's broader hospital infrastructure and expanding insurance coverage for joint replacement procedures.
India's expanding hospital infrastructure and rising osteoarthritis incidence continue adding meaningful regional growth as domestic providers extend surgical capability into previously underserved areas. Japan and South Korea contribute further depth through established, technically advanced healthcare systems, with regional manufacturers notably active in ceramic bearing and robotic-assisted instrumentation development, positioning the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Artificial Hip Joint Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established orthopedic implant manufacturers and continued advancement in ceramic bearing technology developed specifically for younger, more active patients. Germany's substantial hospital and manufacturing base anchors regional demand, supported by a well-developed reimbursement framework that continues to favour early adoption of next-generation hip reconstruction technology across both public and private healthcare providers operating throughout the country and neighbouring markets.
The United Kingdom, France, and other major European markets contribute consistent demand as national health systems keep extending advanced surgical technology into routine orthopedic practice. Continued clinical registry data collection across the region keeps informing implant selection and surgical technique refinement, reflecting the region's role as both an established manufacturing base and a mature, steadily growing end market for hip reconstruction technology.
MEA & Latin America Artificial Hip Joint Market Insights
The Middle East & Africa market is supported by growing healthcare infrastructure spending across the United Arab Emirates and Saudi Arabia, where rising osteoarthritis prevalence continues to lift demand for modern joint reconstruction equipment across both public hospital networks and an expanding private healthcare sector. Regional governments continue channeling substantial investment into expanding orthopedic care access, including dedicated joint replacement centres designed to reduce reliance on overseas treatment for complex cases.
Latin America's market is anchored by Brazil, where a sizeable domestic healthcare sector sustains steady equipment demand across both public and private hospital systems. Mexico contributes further incremental growth as healthcare access continues to widen across the broader region, though adoption of the most advanced ceramic and robotic-assisted systems across Latin America as a whole still lags meaningfully behind more established markets in North America and Europe.
Market Dynamics:
Growth Drivers: Ageing Population and Rising Osteoarthritis Prevalence
Increasing prevalence of osteoarthritis is the key factor driving the growth in the market, boosted by rising expenditure on healthcare, aging population, and increasing obesity, which further expands the pool of patients requiring surgical hip reconstruction procedures globally. Moreover, the forecast made by WHO stating that the number of people aged above 60 will double from 2015 to 2050 remains a driving force behind long-term demand as this demographic change leads to higher patient base for joint replacements.
Growing adoption of robotic-assisted surgical platforms represents a second major driver, supported by hospital capital investment and rising surgeon demand for implant placement precision that extends well beyond traditional manual technique. Increasing prevalence of periprosthetic joint infection, paired with rising demand for antibacterial implant coatings capable of reducing revision rates, continues to reinforce sustained market expansion across both established Western healthcare systems and rapidly developing markets.
Restraints: High Implant Costs and Product Recall Risk
High implant and instrumentation costs remain a genuine restraint on market growth, as advanced systems built around robotic-assisted surgery and ceramic bearing technology continue to command premium pricing that smaller facilities and price-sensitive markets can struggle to justify against tighter capital budgets. This cost barrier particularly affects smaller clinics and hospitals operating in emerging markets, where the upfront investment required for the most sophisticated available systems can meaningfully exceed what many facilities can reasonably allocate toward orthopedic equipment in any given budget cycle.
Product recall risk presents a further restraint, as historical recalls of certain metal-on-metal bearing systems continue shaping surgeon and patient caution around newer bearing technology despite substantial subsequent improvements in manufacturing quality control. This requires manufacturers to sustain substantial ongoing clinical evidence generation and post-market surveillance investment, spanning implant registries, long-term outcome tracking, and regulatory reporting requirements that can meaningfully complicate new product introduction timelines.
Opportunities: Robotic-Assisted Surgery and Antibacterial Coating Innovation
Continued advancement of robotic-assisted and AI-powered surgical guidance platforms offers a substantial opportunity, as vendors securing regulatory clearance for tools improving implant placement accuracy and reducing complication rates stand to capture meaningful new demand from hospitals seeking more consistent surgical outcomes. Hospitals increasingly view these platforms not as a novelty feature but as a genuine operational necessity capable of reducing revision rates while improving overall implant longevity for patients undergoing total hip arthroplasty.
The continued development of antibacterial and iodine-treated implant coatings presents a further avenue for growth, as manufacturers work to address periprosthetic joint infection, one of the most costly and clinically significant complications in orthopedic surgery. This innovation pathway continues to lower long-term revision risk for patients while giving manufacturers a genuine clinical differentiator relative to conventional, uncoated implant surfaces.
Recent Developments:
-
In October 2024, Zimmer Biomet acquired OrthoGrid, a medical technology company focused on artificial intelligence-driven surgical guidance systems for total hip replacement, including the Hip AI fluoroscopy-based surgical assistance product.
-
In April 2025, Smith+Nephew reported early clinical progress for its CATALYSTEM Primary Hip system alongside its first-quarter financial results.
-
In May 2025, Zimmer Biomet reported a 0.9% increase in first-quarter hip revenue, citing strong surgeon response to its Z1 Triple-Taper Femoral Hip System and HAMMR Automated Impactor.
-
In September 2025, Zimmer Biomet received Japan PMDA approval for its iTaperloc Complete and iG7 Hip System, described as the world's first orthopedic implants with iodine technology designed to help address periprosthetic joint infection.
Artificial Hip Joint Market Key Players
-
Johnson & Johnson (DePuy Synthes)
-
Zimmer Biomet Holdings, Inc.
-
Corin Group
-
Exactech, Inc.
-
Lima Corporate S.p.A.
-
MicroPort Orthopedics Inc.
-
Aesculap, Inc. (B. Braun)
-
Medacta International SA
-
Waldemar Link GmbH & Co. KG
-
Enovis Corporation
-
Conformis, Inc.
-
Meril Life Sciences Pvt. Ltd.
-
Adler Ortho S.r.l.
-
Peter Brehm GmbH
-
JRI Orthopaedics Limited
-
FH Orthopedics
-
EVOLUTIS
-
Signature Orthopaedics
Artificial Hip Joint Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.32 Billion |
| Market Size by 2035 | USD 8.46 Billion |
| CAGR | CAGR of 4.75% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Metal-on-Polyethylene, Ceramic-on-Ceramic, Ceramic-on-Polyethylene, and Metal-on-Metal) • by Fixation Type (Cemented, Uncemented, and Hybrid) • by Application (Primary and Revision), End-User (Hospitals, Ambulatory Surgical Centers, and Orthopaedic Clinics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Johnson & Johnson (DePuy Synthes), Smith & Nephew plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., Corin Group, Exactech, Inc., Lima Corporate S.p.A., MicroPort Orthopedics Inc., Aesculap, Inc. (B. Braun), Medacta International SA, Waldemar Link GmbH & Co. KG, Enovis Corporation, Conformis, Inc., Meril Life Sciences Pvt. Ltd., Adler Ortho S.r.l., Peter Brehm GmbH, JRI Orthopaedics Limited, FH Orthopedics, EVOLUTIS, Signature Orthopaedics |
Frequently Asked Questions
Key players include Johnson & Johnson (DePuy Synthes), Smith & Nephew, Stryker Corporation, Zimmer Biomet Holdings, Corin Group, Exactech, Lima Corporate, MicroPort Orthopedics, Aesculap, and Medacta International, among others.
Continued advancement of robotic-assisted and AI-powered surgical guidance platforms and the continued development of antibacterial and iodine-treated implant coatings represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by rising osteoarthritis prevalence and an ageing population, combined with growing adoption of robotic-assisted surgical platforms improving implant placement precision.
By Application, Primary procedures dominated the market with an 81.70% share in 2025, reflecting their role as the foundational driver of overall hip reconstruction volume.
North America dominated the market with a 41.85% share in 2025, supported by a substantial ageing patient population and a dense concentration of leading implant manufacturers headquartered within the region.
